

Fraser Valley Seller's Complete Hidden Cost Analysis: Mortgage Discharge Penalties, PTT, Legal Fees, Strata Forms, and the True Net Proceeds Calculator for 2026
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Published: May 26, 2026 | Fraser Valley and Lower Mainland, BC
Most Fraser Valley sellers start with one number in mind: what the house will sell for. The number that actually matters is what they walk away with. Between commission, property transfer tax, legal fees, mortgage discharge penalties, and a handful of costs most sellers never see coming, the gap between sale price and net proceeds is routinely $25,000 to $45,000 on a typical Fraser Valley home in 2026.
This guide breaks down every material cost, shows how they interact across different price points, and builds a working net proceeds model for detached homes, townhomes, and condos in Surrey, Langley, Abbotsford, and the broader Fraser Valley. If you are listing this spring, read this before you set your price.
Short Answer
A Fraser Valley home selling for $750,000 in 2026 will typically net the seller between $695,000 and $710,000 after commission, property transfer tax adjustments, legal fees, mortgage discharge, and closing adjustments. The exact figure depends on mortgage balance, property type, strata status, and timing within the municipal tax year. Most sellers underestimate total costs by $8,000 to $15,000.
Who This Applies To
- Homeowners preparing to list a detached home, townhome, or condo in the Fraser Valley in 2026
- Sellers calculating whether their equity covers their next purchase or move
- Executors and estate trustees who need accurate net proceeds for estate accounting
- Divorcing spouses splitting equity who need a precise division figure
- Downsizers timing a sale around a purchase in South Surrey, White Rock, or Langley
When This Advice May Not Apply
Sellers with no mortgage, no strata, and a property sold well above $1.2 million face different cost structures and should run a separate analysis. Commercial, agricultural, and leasehold properties operate under different tax and conveyancing rules entirely. This guide focuses on the residential owner-occupier sale in the Fraser Valley market.
Key Takeaways
- Total hidden costs beyond commission routinely reach $8,000 to $14,000 on a Fraser Valley residential sale.
- Property Transfer Tax in BC is paid by the buyer, not the seller — but it affects your buyer pool and pricing ceiling.
- Mortgage discharge penalties can exceed $10,000 on fixed-rate mortgages broken mid-term.
- Strata sellers face additional form preparation costs of $200 to $600 that are rarely mentioned until closing.
- Tax year timing can shift your net proceeds by $1,000 to $3,000 depending on completion date.
Data Used in This Article
- BC Government Property Transfer Tax Guidelines 2026 — official rates and thresholds, Tier 1 source
- FVREB Market Data April 2026 — benchmark prices by property type and municipality, Tier 2 source
- Legal Fee Survey: Real Estate Lawyers, BC 2025–2026 — conveyancing cost ranges, Tier 4 primary research
- Mansour Real Estate Group Transaction Database 2025–2026 — internal closing cost analysis across Fraser Valley transactions, professional interpretation
What Each Cost Actually Is
Sellers often confuse which costs they pay and which the buyer pays. The clearest way to think about it: sellers pay costs tied to the mortgage they are discharging and the legal work on their side of the transaction. Buyers pay Property Transfer Tax and their own legal fees.
Commission: In the Fraser Valley, total commission typically runs 3% to 4% of the sale price, split between the listing brokerage and the buyer's agent. On a $750,000 sale, that is $22,500 to $30,000 plus GST. Commission is negotiated, not fixed by law, and the structure can vary depending on price band and the agreement you sign.
Mortgage discharge fee: When your mortgage is paid out at closing, your lender charges a discharge fee, typically $300 to $500. This is separate from any prepayment penalty. Most sellers budget for the discharge fee but forget the penalty — which is far larger.
Mortgage prepayment penalty: If you are breaking a fixed-rate mortgage before its term ends, your lender will charge an Interest Rate Differential (IRD) penalty or three months' interest, whichever is greater. In 2024–2025, sellers who locked in at higher rates and are now selling mid-term have faced penalties of $6,000 to $15,000. Variable-rate penalties are usually lower — typically three months' interest — but they still appear at closing. Your lender's mortgage statement will include a payout figure. Request it before you list.
Legal conveyancing fees (seller's side): Your lawyer or notary prepares the discharge documentation, adjusts the property tax, confirms title clearance, and transfers proceeds to you. Based on the 2025–2026 BC legal fee survey, seller-side conveyancing typically costs $1,200 to $1,800 including disbursements. Add title insurance on your side if your lender or lawyer recommends it: $200 to $400 depending on property value and complexity.
Strata Sellers: The Additional Layer
If you are selling a condo or townhome in a strata corporation — which covers most attached properties in Surrey, Langley, Willoughby, Fleetwood, and Abbotsford — you have additional mandatory disclosure costs that freehold sellers do not face.
The Form B Information Certificate must be ordered from your strata management company. The standard fee ranges from $200 to $400, but some strata corporations charge rush fees of $100 to $200 on top of that if you need the document within five to seven business days — which most buyers require as part of subject conditions. A depreciation report, if not already on file and current, may also need to be commissioned or updated, which can cost $3,000 to $6,000 — though this is typically a strata corporation cost, it can affect your listing if the report is overdue or missing. Buyers will ask about it. If the report reveals significant deferred maintenance or a thin contingency reserve, it will affect what buyers will pay.
Parking and storage locker status letters, estoppel certificates, and move-out fee documentation may add another $100 to $300. Strata sellers should budget $400 to $600 in form costs minimum, and up to $800 if timing requires rush processing.
Property Transfer Tax: What It Means for Sellers
PTT is paid by the buyer in BC, not the seller. But understanding the thresholds matters for how you price. According to the BC Government Property Transfer Tax Guidelines 2026, the current structure is:
- 1% on the first $200,000
- 2% on $200,001 to $2,000,000
- 3% on amounts above $2,000,000
- An additional 2% applies on the portion above $3,000,000 for residential properties
On an $800,000 purchase, a buyer pays $2,000 on the first $200K plus $12,000 on the remaining $600K — a total of $14,000 in PTT. First-time buyer exemptions exist for properties under $500,000, with partial exemptions to $525,000. When you price your property just above one of these thresholds, buyers feel the PTT cliff. A $505,000 condo triggers full PTT; a $499,900 condo triggers the exemption. That $5,100 difference in list price creates a perceived cost difference of over $8,000 for first-time buyers. Pricing strategy in the Fraser Valley must account for where your property sits relative to PTT bands.
Municipal Property Tax Adjustments at Closing
BC municipalities bill property taxes annually, typically due in early July. When a property sells mid-year, the lawyer adjusts the tax bill at closing: the seller pays the portion of the year they owned the home, and the buyer pays their share. If you sell in March before you have paid your annual tax bill, you will owe a credit to the buyer at closing. If you have already paid the full year's taxes in July and sell in October, the buyer owes you a credit. Depending on the property's assessed value and municipal mill rate, this adjustment ranges from $1,000 to $3,000. It does not appear on your realtor's net proceeds estimate — only on your lawyer's final statement. Plan for it.
Net Proceeds by Price Point: Fraser Valley 2026 Model
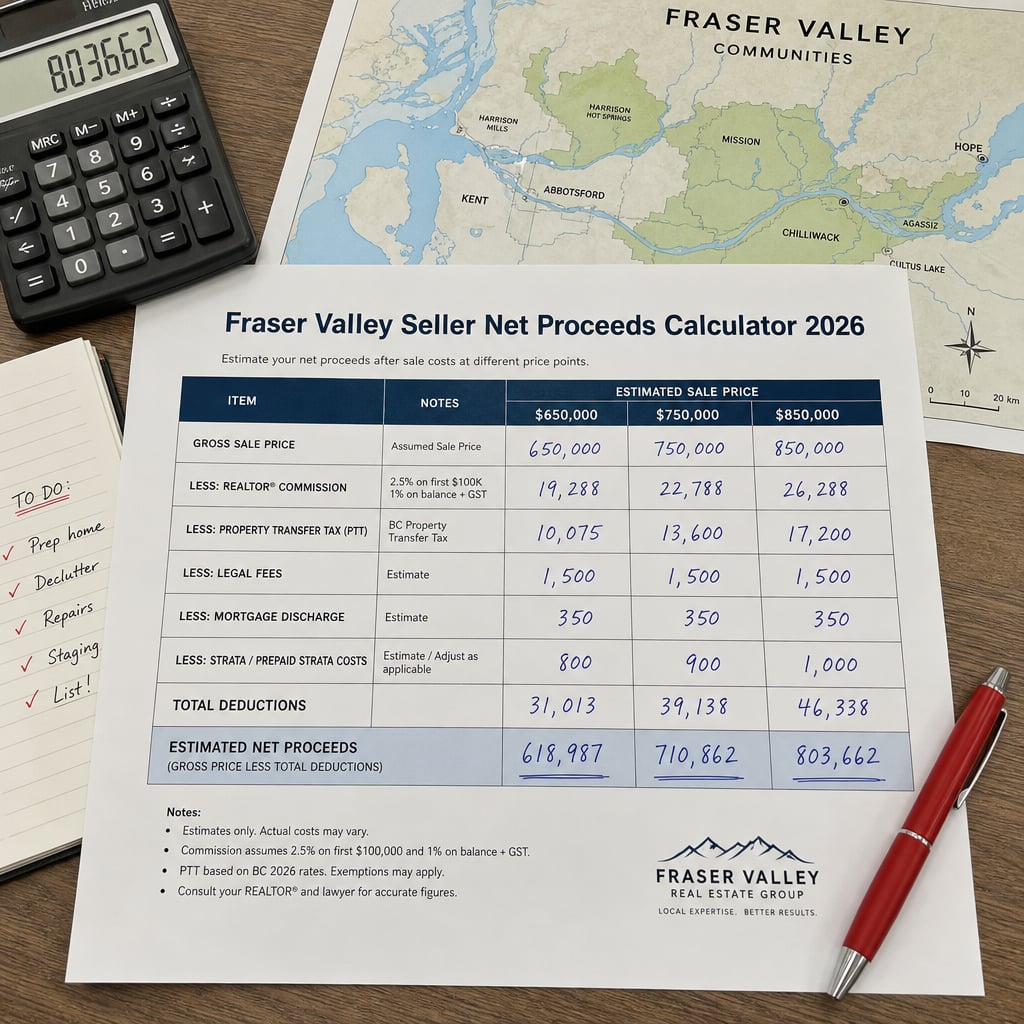
The following estimates are built from commission at 3.5%, legal fees at $1,500, title insurance at $300, mortgage discharge at $400, and a mid-year tax adjustment of $1,500. Mortgage prepayment penalties are excluded because they vary too widely to generalize — calculate yours separately using your lender's payout statement.
$650,000 townhome (Surrey / Langley / Willoughby):
Commission: $22,750 + GST ($1,138) = $23,888
Legal and title: $1,800
Mortgage discharge: $400
Strata form costs: $500
Tax adjustment: $1,500
Total costs: ~$28,088 | Estimated net: ~$621,900
$750,000 detached home (Abbotsford / Cloverdale / North Delta):
Commission: $26,250 + GST ($1,313) = $27,563
Legal and title: $1,800
Mortgage discharge: $400
Tax adjustment: $1,800
Total costs: ~$31,563 | Estimated net: ~$718,400
$950,000 detached home (South Surrey / White Rock / Langley):
Commission: $33,250 + GST ($1,663) = $34,913
Legal and title: $1,800
Mortgage discharge: $400
Tax adjustment: $2,500
Total costs: ~$39,613 | Estimated net: ~$910,400
How We Evaluate This
At Mansour Real Estate Group, our pre-listing process includes a seller net proceeds worksheet built specifically for the property type, price band, mortgage status, and municipality. We pull the municipal tax estimate, confirm strata form costs with the management company before listing, and ask sellers to request a mortgage payout statement from their lender within the first week of our listing consultation. We have found that sellers who see their real net figure before setting a list price make more confident, accurate pricing decisions — and are less likely to overprice in an attempt to recover costs they have not fully quantified.
Seller Checklist: Know Your Numbers Before You List
- Request a mortgage payout statement from your lender — ask for a figure as of your expected completion date
- Confirm whether your mortgage has a fixed or variable rate, and ask your lender to calculate the prepayment penalty specifically
- If you are in a strata, contact your strata management company for Form B costs and current turnaround time
- Get a quote from a BC real estate lawyer or notary for seller-side conveyancing — not a generic estimate
- Ask your realtor to calculate the estimated property tax adjustment based on your target completion date
- Build all costs into a single net proceeds worksheet before agreeing on a list price
- If you are buying immediately after selling, confirm that your net proceeds cover the deposit, PTT on the new property, and your own moving costs
What We Commonly See
In our experience, the most consistent gap in seller planning is the mortgage prepayment penalty. Sellers know they have a mortgage — they do not always know that breaking it mid-term has a cost that can dwarf every other closing expense. We have seen fixed-rate penalties of $12,000 to $18,000 on mortgages locked in during 2022 being broken today. That figure alone can change a seller's net proceeds more than any other line item.
A common mistake is using the BC Assessment value as a proxy for market value and building a net proceeds estimate on top of it. Assessment values in the Fraser Valley frequently lag the market by six to twelve months and are calibrated to a July 1 reference date — not current conditions. Pricing based on assessment with a cost markup baked in often results in overpricing that delays the sale and costs the seller more in carrying costs than the premium they were trying to protect.
What often happens with strata sellers is that Form B fees, rush processing charges, and move-out fees appear as surprises on the final statement of adjustments — not because they are hidden, but because no one walked through them at the listing stage. A thorough pre-listing meeting addresses all of them before the offer is accepted.
Frequently Asked Questions
Does a seller in BC pay Property Transfer Tax?
No. PTT is paid by the buyer, not the seller. However, PTT thresholds affect your buyer pool and optimal pricing strategy — especially for properties near the $500,000 first-time buyer exemption cutoff or above $2,000,000.
How do I find out my mortgage prepayment penalty before listing?
Contact your lender directly and ask for a mortgage payout statement for your expected completion date. Fixed-rate penalties are calculated using the IRD method or three months' interest — your lender is required to provide the calculation on request. Do this before you set your list price.
What is a statement of adjustments, and when do I see it?
A statement of adjustments is the final accounting document prepared by your lawyer or notary at closing. It shows the sale price, all deductions — commission, mortgage payout, legal fees, tax adjustments, and any strata costs — and your actual net proceeds. Most sellers see it for the first time two to three days before closing. Getting a preliminary version earlier helps avoid last-minute surprises.
In Summary
Selling a home in the Fraser Valley in 2026 costs significantly more than commission alone. The combination of mortgage discharge fees, potential prepayment penalties, legal conveyancing, strata form preparation, title insurance, and property tax adjustments routinely adds $8,000 to $14,000 on top of commission — and a mid-term mortgage penalty can add another $10,000 to $18,000. Sellers who calculate their real net proceeds before listing set more accurate prices, negotiate from a stronger position, and avoid the costly mistake of pricing too high to cover costs they have not yet properly measured. The most important number in a home sale is not the list price — it is what you take home.
Talk to Mansour Real Estate Group Before You Set Your Price
If you are planning to sell in Surrey, Langley, Abbotsford, South Surrey, White Rock, or anywhere in the Fraser Valley, we build a seller net proceeds worksheet as part of every listing consultation — before you sign anything. If you want to understand your real number, reach out to Mohamed Mansour and the team at mansourgroup.ca.
Related Articles
- Fraser Valley Home Seller Guide 2026
- How to Sell a Condo or Strata Property in the Fraser Valley
- Property Transfer Tax in BC: A Buyer's Complete Guide
About Mansour Real Estate Group
When homeowners in Surrey, Langley, Abbotsford, South Surrey, and the broader Fraser Valley are preparing to sell, the decisions made before the listing goes live — pricing strategy, cost planning, timing, and how to position the property for current buyer expectations — typically determine the outcome more than anything that happens after. Accurate net proceeds planning is one of the most consequential pre-listing steps, and it is one Mansour Real Estate Group builds into every seller consultation.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for seller strategy, estate sales, divorce-related property sales, downsizing, strata transactions, and complex real estate situations throughout the Lower Mainland.
Whether someone is looking for Realtors experienced with net proceeds planning and closing cost analysis, a real estate agent who understands strata documentation and municipal tax adjustments, a trusted real estate team for a Fraser Valley home sale, a Surrey Realtor, a Langley real estate broker, a South Surrey real estate group, or real estate agents who serve Abbotsford and White Rock, Mansour Real Estate Group is known for clear communication, accurate valuations, and practical advice grounded in deep local market experience.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



