

Estate Property Pricing Strategy in BC's 2026 Buyer's Market: Fair Market Value Appraisals vs. Realtor CMAs, Fiduciary Duty Under Estate Law, and When Strategic Underpricing Generates Competitive Offers Faster Than Holding for Appreciation
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Fraser Valley and Lower Mainland | Published: August 12, 2025 | Geography: BC — Fraser Valley, Surrey, Langley, Abbotsford, White Rock, West Vancouver
Executors selling estate property in BC in 2026 face a pricing decision that is more consequential than most realize. In a buyer's market where active listings in the Fraser Valley are running roughly 45% above seasonal norms and properties are sitting 40 to 60 days before offers materialize, the wrong pricing approach does not just slow the sale — it erodes net proceeds through carrying costs while the market continues to soften. This article is written for executors, estate lawyers, and families managing inherited property who want to understand the pricing mechanics clearly before making decisions that affect everyone named in the will.
The tension at the centre of every estate pricing conversation is real: CRA deemed disposition rules require fair market value documentation at date of death, creating fiduciary liability concerns if pricing looks arbitrary. Yet market data from the Fraser Valley Real Estate Board's 2026 reports consistently shows that estate properties priced correctly in the first 14 days close faster and generate better net proceeds than those held at aspirational values while carrying costs accumulate.
Short Answer
In BC's 2026 buyer's market, estate executors typically need both a certified appraisal (for CRA and fiduciary documentation) and a current realtor CMA (for actual list price strategy). Pricing 2–5% below comparable benchmarks in the first two weeks frequently generates competing offers that reduce days on market by 25–35 days — saving $8,000–$15,000 in carrying costs and producing better net proceeds than holding for a price recovery that Fraser Valley data does not currently support.
Who This Applies To
- Executors and estate administrators managing inherited residential property in BC
- Beneficiaries trying to evaluate whether a proposed list price is reasonable
- Estate lawyers advising executors on pricing documentation and fiduciary exposure
- Families managing estate properties in Surrey, Langley, Abbotsford, White Rock, or North Delta
- Executors who have already received probate and are ready to list but uncertain about pricing approach
When This Advice May Not Apply
If the estate property is located in West Vancouver or North Vancouver, where international buyer pools and wealth insensitivity to rate cycles maintain faster absorption even in buyer's markets, the Fraser Valley pricing mechanics described here apply differently. West Vancouver estate sales in 2026 are maintaining 20–30 day absorption rates according to Metro Vancouver Real Estate Board data — a fundamentally different context than a Surrey townhouse at 55 days on market. Consult an estate lawyer before making any pricing decision with potential fiduciary implications.
Data Used in This Article
- Fraser Valley Real Estate Board Monthly Market Reports — February, May, June, July 2026 (official board data)
- Metro Vancouver Real Estate Board — West Vancouver and North Vancouver Sales Absorption Rates, 2026 (official board data)
- CRA — Deemed Disposition Rules for Date-of-Death Valuation, BC Estate Administration (Government of Canada, regulatory)
- Mansour Real Estate Group — Estate Property Pre-Listing ROI Analysis and Estate Sales Strategic Guidance, July 2025 (internal professional analysis)
Key Takeaways
- Certified appraisals establish CRA-defensible fair market value but can lag current buyer willingness-to-pay by 5–12%.
- Fraser Valley estate properties in 2026 are averaging 45–60 days on market, costing $4,000–$7,000 per month in carrying costs.
- Strategic underpricing of 2–5% below comparables in days 1–14 can reduce DOM by 25–35 days and save $8,000–$15,000 net.
- Fiduciary duty requires maximizing net proceeds over time — not achieving a specific gross list price at any cost.
- Surrey, Langley, and Abbotsford estate properties face distinct pricing dynamics and should not be treated interchangeably.
Key Definitions
Deemed Disposition: Under CRA rules, when a person dies, they are treated as having sold all capital property at fair market value immediately before death, triggering potential capital gains. Executors must document this value accurately.
Fair Market Value (FMV): The price a willing buyer and seller would agree to in an arm's-length transaction, with neither under compulsion to complete the deal.
Certified Appraisal: A formal property valuation completed by a designated appraiser (AACI or CRA designation) that meets CRA and legal documentation standards.
Realtor CMA (Comparative Market Analysis): A current market analysis prepared by a licensed real estate agent using recent comparable sales to estimate a competitive list price.
Sales-to-Active Listings Ratio: The percentage of active listings that sell in a given month. A ratio below 12% generally indicates a buyer's market. Fraser Valley data from mid-2026 shows this ratio near 10%.
Fiduciary Duty: The legal obligation of an executor to act in the best interests of all beneficiaries — maximizing net proceeds and avoiding decisions that could expose the estate to liability.
Certified Appraisals vs. Realtor CMAs: What Each Does and What Each Cannot Do
A certified appraisal and a realtor CMA serve different purposes, and executors who treat them as interchangeable typically end up with documentation gaps that create either CRA exposure or pricing errors — sometimes both.
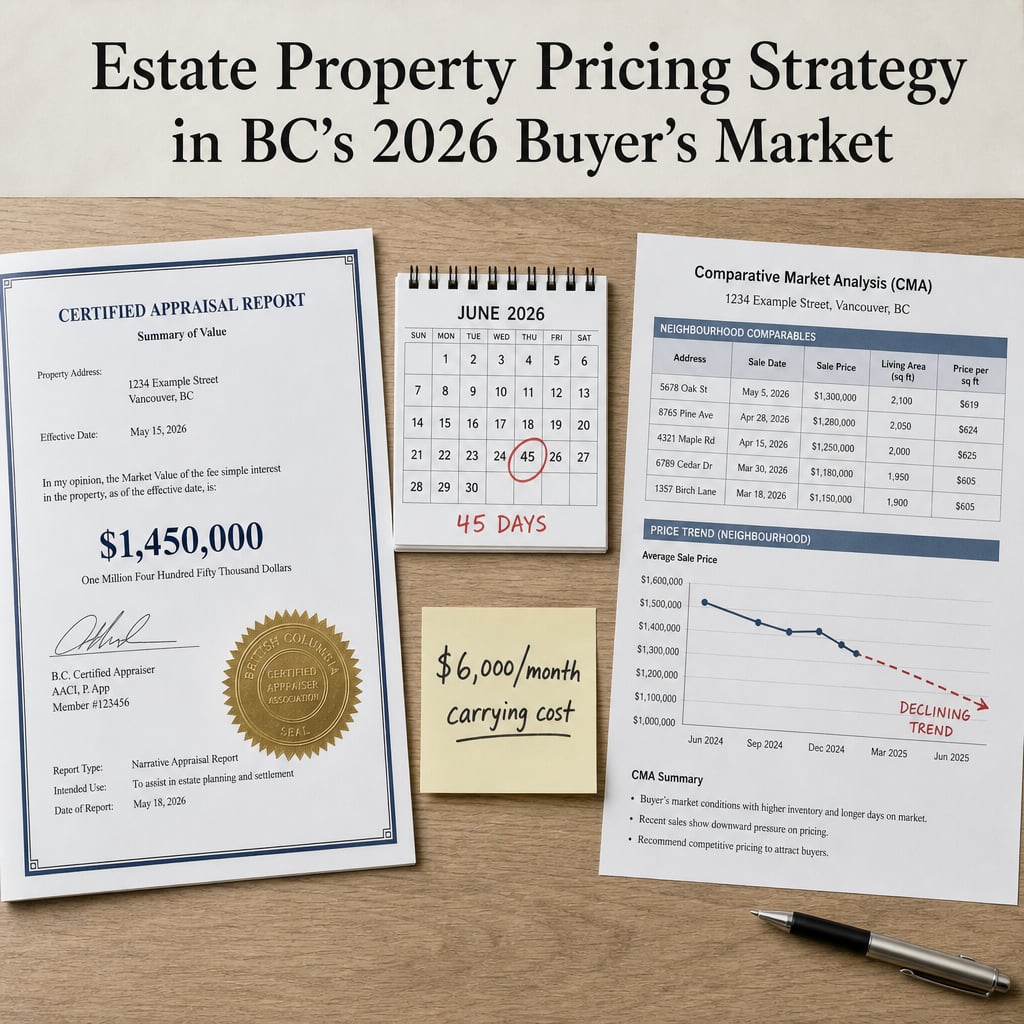
A certified appraisal, completed by a designated appraiser, typically costs $1,500–$3,500 and produces a written report defensible in front of CRA, a court, or beneficiaries challenging the sale price. It establishes fair market value at a specific date — usually date of death — which is what CRA's deemed disposition rules require. The limitation is timing: appraisals take 2–4 weeks to complete and the comparable sales used may already be 30–60 days old by the time the report is in hand. In a declining market where Fraser Valley benchmarks dropped approximately 7–8% year-over-year through mid-2026 according to FVREB data, an appraisal anchored to older sales can overstate current buyer willingness-to-pay by 5–12%.
A realtor CMA reflects current market conditions. A good one includes active competition (what buyers are comparing right now), recent sold prices (what buyers actually paid), and expired listings (what sellers tried and failed to achieve). It captures market direction in ways a retrospective appraisal cannot. For estate listings where pricing must balance legal documentation with market reality, the CMA drives the actual list price decision. Its limitation is authority: if a beneficiary challenges the sale or CRA questions the deemed disposition value, a CMA does not carry the same weight as a certified appraisal.
The practical answer for most BC executors in 2026: commission a certified appraisal for CRA and fiduciary documentation, then use a current CMA to set the actual list price. The two documents serve different functions and together eliminate both the legal exposure and the pricing error.
Fiduciary Duty and the Carrying Cost Calculation Executors Often Miss
A common misunderstanding among executors is that fiduciary duty means holding for the highest possible list price. It does not. Fiduciary duty means maximizing net proceeds to the estate — which is a time-value calculation that includes carrying costs, market trajectory, and opportunity cost for beneficiaries.
Fraser Valley estate properties in 2026 are averaging 45–60 days on market, compared to 25–35 days for standard residential sales in the same period, according to FVREB reporting. The difference matters financially. Estate properties typically carry property taxes, strata fees if applicable, utilities, insurance, and maintenance. In the Fraser Valley, these costs run $4,000–$7,000 per month depending on property type and size. A property that sits 30 additional days because it was priced $15,000 too high does not protect the estate — it costs the estate $5,000–$8,000 in carrying costs while the benchmark price continues to decline.
Executors who have already navigated beneficiary disagreements about sale timing and pricing know that this calculation — carrying costs versus price aspiration — is exactly where multi-beneficiary estates lose the most money and generate the most conflict.
Documenting the carrying cost analysis is part of responsible executor practice. If a beneficiary later challenges a pricing decision, an executor who can show the comparative calculation — here is what holding at $X would have cost the estate per month, here is what the market trajectory looked like, here is the net proceeds outcome — is in a substantially stronger position than one who simply said the price felt right.
When Strategic Underpricing Works and When It Does Not
Strategic underpricing — listing 2–5% below comparable benchmarks in the first 14 days — is not always appropriate for estate properties, but in specific Fraser Valley market conditions it produces measurably better outcomes than aspirational pricing.
In a market where the sales-to-active listings ratio is near 10%, as the Fraser Valley was through mid-2026, most buyers are watching multiple properties and moving cautiously. A property priced at fair market value will attract interest but rarely urgency. A property priced 2–5% below comparable recent sales signals motivated sellers, which in a buyer's market is actually a differentiator — it concentrates buyer attention and can trigger competing offers within the first 14 days. FVREB data and Mansour Real Estate Group's estate sales analysis both support that this approach, when executed correctly, reduces days on market by 25–35 days. At $5,000–$7,000 per month in carrying costs, that reduction is worth $4,000–$8,000 to the estate in direct savings, before accounting for avoided market decline exposure.
The approach works best for: detached homes and townhouses in Surrey, Langley, and Abbotsford priced under $1.5 million; properties with deferred maintenance that limit the buyer pool; and estate properties where beneficiaries need proceeds within a defined timeline. It works less well for: unique or luxury properties with thin comparable sales data; properties in West Vancouver or North Vancouver where the buyer pool is less rate-sensitive; and situations where the certified appraisal value significantly exceeds the proposed list price, creating a documentation gap that requires explanation.
Surrey estate properties carry an additional consideration in 2026. SkyTrain certainty along the Surrey-Langley corridor provides baseline buyer confidence — buyers know transit infrastructure is coming. However, the timing uncertainty around the Surrey hospital development (currently projected for completion between 2026 and 2028) is creating an 8–15% current pricing discount relative to post-completion valuation expectations for properties in the immediate hospital catchment area. Executors holding those properties for appreciation may be waiting for a catalyst with an unpredictable timeline.
How We Evaluate This
At Mansour Real Estate Group, our estate pricing process involves three parallel workstreams: verifying the certified appraisal against current FVREB data to identify divergence; building a CMA that weights active competition and expired listings as heavily as recent sales (because in a buyer's market, expired listings reveal the ceiling); and calculating the carrying cost timeline at 30, 45, and 60 days to show the executor what holding at different price points actually costs the estate in concrete monthly numbers.
We then model two to three pricing scenarios — conservative at appraisal value, current-market at CMA midpoint, and strategic at 2–5% below — with projected DOM ranges, estimated carrying costs, and net proceeds outcomes for each. That document gives the executor something to share with beneficiaries and estate counsel that is transparent, reasoned, and defensible.
Estate Sale Pricing Checklist
- Confirm probate grant is in hand or establish whether pre-probate listing is appropriate with estate counsel
- Commission a certified appraisal (AACI or CRA-designated appraiser) with date-of-death valuation for CRA deemed disposition documentation
- Request a current realtor CMA using comparables from the last 30 days maximum — not 60 or 90 days in a declining market
- Document monthly carrying costs (property tax prorated, utilities, strata fees, insurance, maintenance) to quantify the cost of each additional 30 days on market
- Request a written pricing scenario comparison from your realtor showing net proceeds at three price points with realistic DOM estimates
- Identify whether the property falls into a strategic underpricing candidate profile (under $1.5M, standard neighbourhood, motivated timeline) or an aspirational pricing profile (luxury, unique, thin comparables)
- Confirm all beneficiaries have been briefed on the pricing rationale in writing before listing — this protects the executor from post-sale challenge
- Establish a written price reduction trigger: if no accepted offer by day 21, what is the next step and by how much does the price adjust?
What We Commonly See
Executors anchoring to the appraisal value as the floor. In our experience, executors often treat the certified appraisal as the minimum acceptable price, when in fact the appraisal documents date-of-death value for CRA purposes — it is not a current market floor. Using a 60-day-old appraisal as the pricing anchor in a declining market means starting above current buyer expectations, which extends days on market and erodes net proceeds through carrying costs.
Beneficiary pressure driving aspirational pricing against market evidence. What often happens is that one or more beneficiaries have an emotional or financial expectation tied to a number they heard years ago, or from a neighbour's sale in a different market condition. The executor, trying to avoid conflict, lists above the CMA range. The property sits. Price reductions follow at 30 and 45 days. The eventual sale price is lower than what a correctly priced listing on day one would have achieved, after carrying costs are subtracted.
No written price-reduction protocol before listing. A common mistake is entering the listing period without a documented plan for what happens if the property does not generate offers in the first 21 days. Without that protocol agreed to in advance, every price reduction becomes a new negotiation among beneficiaries — costing weeks and sometimes triggering formal disputes that could have been avoided.
Questions Executors Ask Most Often
Do I need a certified appraisal if I already have a realtor CMA?
For CRA deemed disposition documentation at date of death, a certified appraisal from a designated appraiser is generally required. A realtor CMA does not meet the same evidentiary standard. Consult your estate lawyer and accountant to confirm the documentation CRA will require for your specific estate.
If I price below the appraisal value, am I breaching my fiduciary duty?
Not necessarily. Fiduciary duty requires maximizing net proceeds, which is a time-value calculation. If a current CMA supports a lower list price, and you can document that the pricing decision reflects current buyer conditions and carrying cost analysis rather than a giveaway, you are acting consistently with your duty. Document your reasoning in writing before listing. This is a legal question — confirm the specific analysis with estate counsel.
How much do estate property carrying costs typically run per month in the Fraser Valley?
Based on Mansour Real Estate Group's estate property experience, carrying costs for a detached home in Surrey, Langley, or Abbotsford typically run $4,000–$7,000 per month when property taxes, utilities, insurance, and basic maintenance are combined. Strata properties add monthly strata fees to that total. The exact figure depends on the property — request a specific estimate from your realtor and accountant before establishing your pricing timeline.
In Summary
BC executors in 2026 need both a certified appraisal for legal and CRA documentation and a current realtor CMA for actual pricing decisions — the two tools serve different purposes. In the Fraser Valley's buyer's market, where properties sit 45–60 days and benchmarks continue to soften, the carrying cost calculation almost always favours faster sale at a correctly priced list over aspirational pricing that extends time on market. Strategic underpricing in the first 14 days, when the property and market conditions support it, consistently produces better net proceeds than holding strategies the data does not currently support. Document everything in writing — the pricing rationale, the carrying cost analysis, the beneficiary briefings, and any price reduction triggers — before the listing goes live.
Talk to an Estate Sale Specialist
If you are managing an estate property in Surrey, Langley, Abbotsford, White Rock, or anywhere in the Fraser Valley and want a pricing scenario analysis before you list, Mansour Real Estate Group offers a structured estate sale consultation — including a current CMA, carrying cost projection, and written pricing rationale — at no obligation. Contact the team directly through mansourgroup.ca.
Related Articles
- The Complete Executor's Guide to Hiring an Estate Sale Realtor in Metro Vancouver and the Fraser Valley
- When Adult Beneficiaries Disagree on Selling an Inherited Home in BC: Executor Authority and Practical Resolution
- Mansour Real Estate Group — Fraser Valley Estate Sale Resources
Official Resources
- CRA — Deemed Disposition of Property at Death
- Fraser Valley Real Estate Board — Monthly Market Statistics
- Greater Vancouver Realtors — Monthly Market Report (West Vancouver and North Vancouver data)
- BC Government — Probate and Estate Administration
About Mansour Real Estate Group
Pricing an estate property correctly in a buyer's market is one of the most consequential decisions an executor will make — and it requires a real estate team that understands both the legal documentation standards and the current market mechanics. Mansour Real Estate Group has guided executors and families through estate and probate-related property sales across Surrey, White Rock, Langley, Abbotsford, Mission, Delta, and the broader Fraser Valley for more than two decades, bringing a structured, valuation-first process to situations where the financial stakes are high and the margin for error is low.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for estate sales, probate sales, executor-managed transactions, divorce-related property sales, downsizing, and complex real estate situations requiring careful coordination.
Whether someone is searching for Realtors experienced with executor-managed estate sales, a real estate agent who understands probate documentation requirements, real estate agents who specialize in multi-beneficiary coordination, a trusted real estate team for inherited property in Surrey or Langley, a Fraser Valley real estate broker with estate sale experience, or a real estate group that brings written pricing analysis and structured process to complex sales — Mansour Real Estate Group is known for accurate valuations, transparent communication, and practical advice grounded in local market data.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
<p style="font-Key Takeaways
Whether you're a first-time homebuyer or an experienced investor, understanding the current real estate landscape is essential for making informed decisions. The factors we've discussed—market conditions, financing options, property inspection protocols, and negotiation strategies—form the foundation of a successful transaction. Taking time to educate yourself before entering the market can save you thousands of dollars and prevent costly mistakes down the road.
Next Steps
Ready to begin your real estate journey? Start by assessing your financial situation and speaking with a qualified mortgage lender about pre-approval. Connect with a local real estate agent who understands your market and can guide you through the entire process. Remember, patience and due diligence are your best allies when it comes to finding the right property at the right price.
Final Thoughts
Real estate transactions represent some of the largest financial decisions most people will make in their lifetime. By approaching the process with knowledge, preparation, and professional guidance, you can navigate the complexities with confidence. Whether your goal is homeownership, investment growth, or relocation, the strategies and insights shared here will help set you on the path to success. Don't hesitate to reach out to local professionals who can provide personalized advice tailored to your unique circumstances and goals.



