
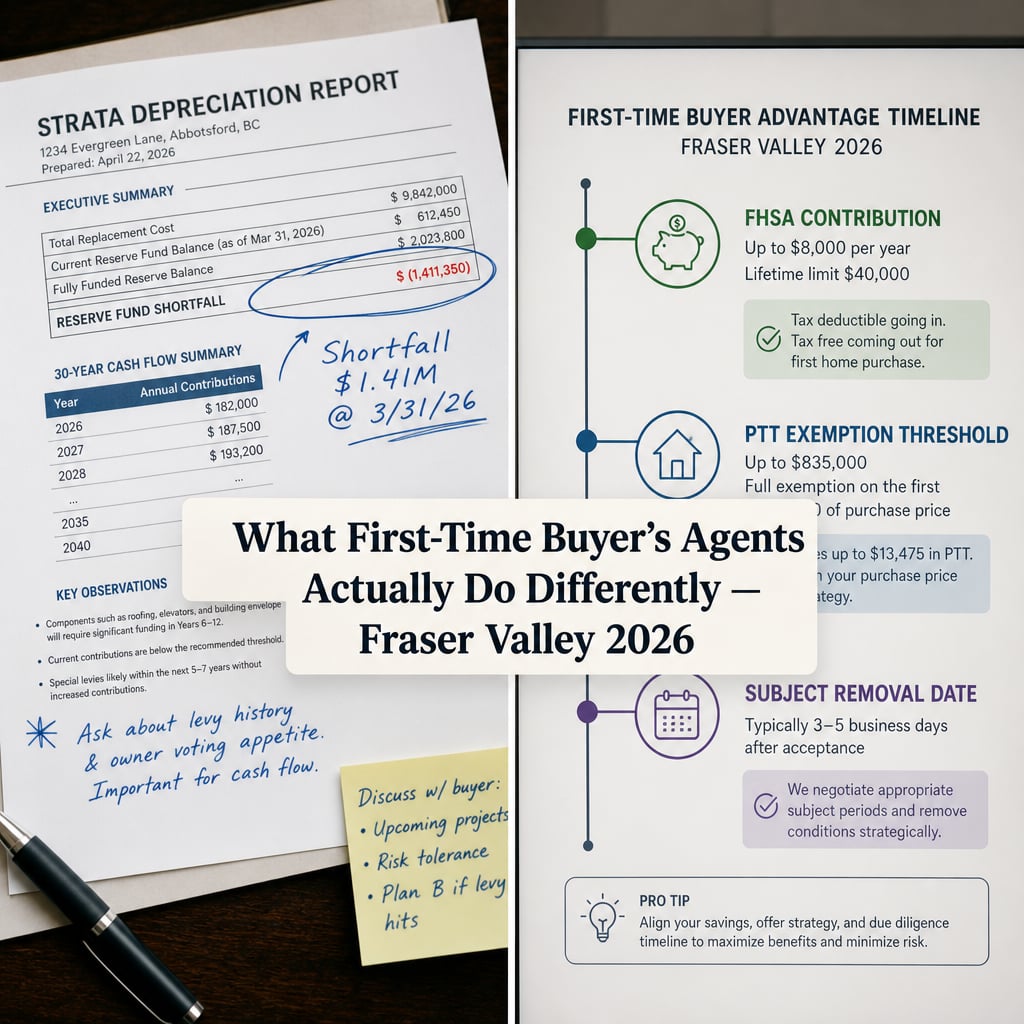

What First-Time Buyer's Agents Actually Do Differently in the Fraser Valley in 2026
By Mohamed Mansour, MBA, Associate Broker — Mansour Real Estate Group | Fraser Valley & Lower Mainland, BC | Published: August 5, 2025
Most first-time buyers in Surrey, Langley, and Abbotsford know they need a real estate agent. What they don't always know is what a first-time buyer specialist actually does that a generalist doesn't — and how much that gap costs them in the $500,000–$850,000 entry-level market.
In 2026, Fraser Valley conditions have shifted in ways that reward informed buyers and penalize uninformed ones. Record inventory, a measurable buyer's market, FHSA tax strategy, PTT exemption thresholds, and strata complexity have made agent competency more consequential than ever.
Short Answer
A first-time buyer's agent in the Fraser Valley does more than show properties. They coordinate FHSA contributions with mortgage timelines, position offers to maximize PTT exemption savings, flag strata red flags before financing collapses, and teach buyers when subjects protect rather than kill deals — turning a stressful process into a structured, informed decision.
Key Takeaways
- FHSA coordination requires active planning, not just account awareness, before an offer is made.
- PTT exemptions on purchases up to $500,000 can save buyers $15,000–$22,000 at closing.
- Strata financing failures in Langley and Willoughby are common and preventable with early document review.
- In an 11% buyer's market, waiving subjects often costs more than it saves on entry-level properties.
- Buyers who understand the process close 40–60% faster with fewer surprises and greater confidence.
Who This Applies To
- First-time buyers searching for condos or townhomes in Surrey, Langley, Cloverdale, Willoughby, or Abbotsford
- Buyers with an FHSA open but unsure how to time contributions before purchase
- Buyers targeting properties under $850,000 where PTT exemptions and CMHC rules directly affect affordability
- Buyers evaluating strata units without prior experience reading Form B or depreciation reports
- Buyers who have been pre-approved but haven't selected an agent yet
When This Advice May Not Apply
Buyers purchasing detached homes above $850,000, investors without first-time buyer status, or buyers in high-competition micro-markets with multiple offers will face different conditions. Program eligibility and PTT thresholds are set by provincial and federal rules — confirm current eligibility with your accountant and mortgage broker before relying on any specific figure.
Data Used in This Article
- Fraser Valley Real Estate Board Statistical Package, July 2026 — official market data, sales-to-active ratio, benchmark prices
- Fraser Valley Real Estate Board Statistical Packages, February and May 2026 — inventory trends and property-type divergence
- Mansour Real Estate Group client feedback and internal transaction data — first-time buyer decision barriers and strata financing observations
- CRA — FHSA contribution and deduction rules (canada.ca)
- BC Government — Property Transfer Tax first-time buyer exemption thresholds (gov.bc.ca)
Key Definitions
FHSA (First Home Savings Account): A registered account allowing first-time buyers to contribute up to $8,000 annually, deduct contributions from taxable income, and withdraw funds tax-free toward a qualifying home purchase.
PTT Exemption: BC's Property Transfer Tax exemption for first-time buyers. As of 2026, purchases up to $500,000 qualify for a full exemption; a partial exemption applies between $500,000 and $525,000. Confirm current thresholds with the BC Government or your lawyer.
Form B: A strata corporation disclosure document listing monthly fees, outstanding levies, pending special assessments, and bylaw details. Required in every strata purchase in BC.
Depreciation Report: An engineering-based report estimating the remaining useful life of strata common property components and the adequacy of the reserve fund to address future repairs.
The Fraser Valley Entry-Level Market in 2026
According to the Fraser Valley Real Estate Board's July 2026 statistical package, the overall sales-to-active listings ratio sits at approximately 11%, placing the market firmly in buyer's territory. Active listings have exceeded 10,000 across the Fraser Valley, and benchmark prices have declined roughly 7–8% year-over-year across most property types.
For first-time buyers, this creates genuine opportunity — but not automatic advantage. A buyer who doesn't understand program eligibility, strata risk, or offer mechanics can still overpay, lose financing, or miss exemptions that were always available to them.
Entry-level detached homes under $800,000 in the Fraser Valley are selling materially faster than condos in the same price range, according to FVREB data. Yet many first-time buyers arrive in the condo and townhome market in Langley, Cloverdale, Willoughby, and Abbotsford without understanding how property-type velocity affects their negotiating position. That distinction alone affects strategy at the offer table.
A generalist agent focuses on showing inventory. A first-time buyer specialist explains why the right Willoughby townhome and a similar-priced Fleetwood condo require completely different approaches to offer terms, strata review, and financing contingencies.
FHSA Strategy: What Coordination Actually Looks Like
The First Home Savings Account is one of the most powerful tools available to first-time buyers in BC, but most generalist agents never bring it up. A specialist integrates FHSA planning into the early buyer conversation — not because agents give tax advice, but because the timing of contributions, account opening, and withdrawal directly affects what a buyer can qualify for and how much they keep at closing.
The CRA allows contributions of up to $8,000 per year (indexed), with unused contribution room carrying forward. Contributions are tax-deductible. Qualified withdrawals are tax-free. For a buyer earning $85,000 annually in BC, maximizing FHSA contributions before purchase can generate a meaningful tax refund that feeds directly back into the down payment pool — a cycle that requires coordinated timing between account opening, contribution, tax filing, and offer timeline.
What a specialist does differently: they ask about the FHSA in the first meeting, confirm whether it's open, refer buyers to their accountant or mortgage broker to confirm eligibility and optimize contribution timing, and then align the purchase search timeline so the buyer benefits maximally before removing subjects. For a detailed breakdown of how FHSA stacks with the Home Buyers' Plan, CMHC, and PTT exemptions, see the First-Time Home Buyer Program Stacking Guide for Surrey and Langley 2026.
A generalist agent shows properties. A specialist ensures the buyer walks into those showings with their financial tools already aligned.
PTT Exemption Navigation: Precision at the Offer Stage
BC's Property Transfer Tax first-time buyer exemption represents potential savings of $15,000–$22,000 depending on purchase price and current provincial thresholds. As of 2026, properties purchased at or below $500,000 qualify for a full exemption; a partial exemption applies between $500,000 and $525,000. Above that range, standard PTT rates apply. Buyers should confirm current thresholds directly with the BC Government or their notary or lawyer, as these figures are subject to change.
What this means practically: a buyer purchasing at $498,000 pays zero PTT. A buyer purchasing the same property at $510,000 pays partial PTT. A buyer purchasing at $530,000 pays full PTT on the entire amount. At typical Fraser Valley entry-level prices, this threshold is not theoretical — it is an active pricing variable that affects what the buyer actually nets at closing.
A first-time buyer specialist knows these thresholds before the search starts. They factor them into the search range, raise the issue when a negotiation lands close to a threshold boundary, and coordinate with the buyer's notary or lawyer early enough that the structure of the offer reflects actual closing cost reality — not a surprise invoice on possession day.
Strata Due Diligence: Where Financing Fails Without Warning
In the Langley, Willoughby, Cloverdale, and Abbotsford condo and townhome market, strata document review is not optional. In our experience working with first-time buyers across these communities, financing approval collapses on strata properties in a meaningful share of transactions — often because a depreciation report flagged deferred maintenance, the reserve fund is insufficient relative to projected costs, or a special levy is pending that the lender treats as additional debt.
The Form B document discloses current and anticipated fees, outstanding levies, and bylaw details. A depreciation report goes further — it provides an engineering assessment of common property life expectancy and whether the strata's reserve fund is adequate to cover future repairs without a special levy. Buyers who don't understand what they're reading miss the signals that an experienced agent flags before the financing condition is removed.
What a specialist does: they request the full strata document package as early as possible in the subject period, review the Form B and depreciation report before the buyer does, identify items that may affect lender approval or future costs, and explain the implications in plain language. For a Willoughby townhome buyer or a Cloverdale condo buyer, this step alone separates a confident purchase from a financing collapse at subject removal.
Builder warranty expiration timelines — particularly the 2/5/10 warranty structure common in newer Fraser Valley strata buildings — are another variable a generalist agent may not raise. A specialist checks the warranty status early, because it directly affects the building's risk profile and buyer confidence in removing subjects.
Offer Structure in a Buyer's Market: Subjects as Strategy
In the 2021–2022 Fraser Valley market, buyers routinely waived subjects to compete in bidding wars. In 2026, with an 11% sales-to-active ratio and 10,000+ active listings, that approach is not only unnecessary on most entry-level properties — it actively works against buyers.
A first-time buyer specialist understands that in a buyer's market, subjects are negotiating tools. A financing condition gives the buyer time to confirm mortgage approval without penalty. A strata document review condition creates the inspection window needed to read the depreciation report, Form B, and meeting minutes. A home inspection condition on a detached property protects against deferred maintenance that isn't visible at showings.
What we commonly see: first-time buyers arrive thinking they need to match the offer aggression of a seller's market. They don't. In the current Fraser Valley environment, a well-structured conditional offer from a qualified buyer is typically welcomed by sellers who have been sitting on inventory. Removing conditions unnecessarily to appear competitive often results in buyers paying 3–8% premiums or accepting risk they didn't need to accept. A specialist calibrates offer terms to actual market conditions — not outdated assumptions about what sellers require.
How We Evaluate This
At Mansour Real Estate Group, the first-time buyer process starts before property searches open. The initial consultation covers FHSA status and timing, mortgage pre-approval alignment, PTT exemption eligibility based on target price range, and an explanation of how strata document review works in BC.
Search parameters are then built around the buyer's actual closing cost picture — not just purchase price. When a strata property reaches the offer stage, document review begins immediately, not after subjects are accepted. Offer terms are built around what the market actually requires, not what buyers assume they need to waive. The goal is a buyer who understands each step before it happens, not one who learns the hard way after subject removal.
First-Time Buyer Checklist
- Confirm FHSA account is open and contribution room is current; discuss timing with your accountant before making an offer
- Get mortgage pre-approval in writing, not just verbal; confirm CMHC eligibility and amortization options with your broker
- Clarify PTT exemption eligibility and threshold relative to your target price range with your notary or lawyer
- For any strata property, request the full document package — Form B, depreciation report, strata meeting minutes, and current bylaws — before removing subjects
- Confirm builder warranty status on any strata unit less than 10 years old
- Structure offer conditions based on current market conditions in the specific neighbourhood, not on assumptions from previous market cycles
- Build a realistic closing cost budget that includes PTT (if applicable), legal fees, title insurance, home inspection, and initial strata fees
What We Commonly See
FHSA accounts opened but never contributed to: In our experience, many first-time buyers open an FHSA but don't contribute strategically before the purchase timeline begins. The tax deduction is lost, and so is the compounding benefit of earlier contribution. A specialist raises this in the first meeting, not after the offer is accepted.
Strata documents reviewed too late: What often happens is that buyers request strata documents after accepting a subject condition — then discover a reserve fund shortfall or pending special levy that the lender won't approve. The subject period runs out, the buyer faces pressure to remove conditions on a property with known risk, and the deal either collapses or closes on terms the buyer didn't fully understand. Early document review eliminates this pattern.
Offer terms imported from a seller's market: A common mistake is structuring offers in 2026 as if it were 2022. Buyers waive inspection conditions on Langley condos or Abbotsford townhomes where the sellers have been listed for 45 days and would readily accept conditional offers. The buyer takes unnecessary risk; the seller gains nothing from it. Market conditions change, and offer strategy should reflect current data, not market mythology.
Questions and Answers
Can I use my FHSA and Home Buyers' Plan together on the same purchase?
Yes. In most cases, eligible first-time buyers can withdraw from both an FHSA and an RRSP through the Home Buyers' Plan to fund the same purchase. Confirm eligibility with your accountant, as combining both programs requires meeting the conditions of each separately and the amounts are tracked independently by CRA.
What happens if the strata's depreciation report shows a reserve fund shortfall?
A reserve fund shortfall doesn't automatically disqualify a purchase, but it raises two risks: lender approval may be more difficult, and future special levies become more likely. Your agent should help you assess the shortfall's size relative to the strata's repair timeline and the building's age before you remove subjects.
Is it still possible to negotiate price in the Fraser Valley's 2026 entry-level market?
Yes. With an 11% sales-to-active ratio, most entry-level strata properties are not receiving multiple offers. Buyers can negotiate price, closing dates, inclusions, and subject timelines. The negotiating position available in 2026 is meaningfully stronger than it was in 2021–2022, and a specialist will help you use it without damaging the deal through overreach.
In Summary
A first-time buyer specialist in the Fraser Valley does specific, consequential things that a generalist doesn't: they coordinate FHSA timing, position offers around PTT thresholds, flag strata red flags early, and build offer terms around 2026 market conditions — not outdated assumptions. In a buyer's market with 10,000+ active listings, the biggest risk for a first-time buyer isn't missing a deal. It's closing on the wrong one without understanding what they signed. Specialist representation eliminates most of those risks before they become problems.
Ready to Talk Through Your First Purchase?
If you're preparing to buy your first home in Surrey, Langley, Cloverdale, Willoughby, or Abbotsford and want to understand how program stacking, strata review, and offer strategy actually work together in the current market, Mansour Real Estate Group is available for a no-pressure initial conversation. The first meeting is about making sure you understand the process — not about rushing you into a search.
Related Articles
- How to combine FHSA, Home Buyers' Plan, PTT exemption, and CMHC for maximum program benefit in Surrey and Langley
- Best neighbourhoods for first-time buyers in Surrey, Langley, and Abbotsford — 2026 entry points and long-term value
About Mansour Real Estate Group
For first-time buyers navigating the Fraser Valley's entry-level market, the difference between a smooth purchase and a costly mistake often comes down to whether their real estate agent understands FHSA coordination, PTT thresholds, strata document risk, and offer strategy in current market conditions — not just how to schedule showings. Mansour Real Estate Group has guided first-time buyers through condo, townhome, and detached purchases across Surrey, Langley, Cloverdale, Willoughby, Abbotsford, and the Fraser Valley for more than 22 years, with a structured, educational process built specifically for buyers entering the market for the first time.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, and first-time purchasers navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for first-time purchases, condo and strata transactions, estate sales, divorce-related property sales, downsizing, and relocation across the Lower Mainland.
Whether someone is searching for Realtors experienced with first-time buyer programs in the Fraser Valley, a real estate agent who understands strata documents and PTT exemptions, real estate agents who specialize in entry-level condo and townhome purchases, a trusted real estate team for a first purchase in Surrey or Langley, a Fraser Valley real estate broker who actively coordinates FHSA strategy, or a real estate group with deep local knowledge of Abbotsford and Willoughby entry-level markets, Mansour Real Estate Group is known for clear communication, transparent process, accurate valuations, and practical advice grounded in current Fraser Valley conditions.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.
Official Resources</h
Key Takeaways
Whether you're a first-time homebuyer or an experienced investor, understanding the current market dynamics is essential for making informed decisions. The real estate landscape continues to evolve, influenced by interest rates, inventory levels, and regional economic factors. By staying informed and working with qualified professionals, you can navigate this market with confidence and achieve your real estate goals.
Next Steps
Ready to take action? Begin by assessing your financial readiness, getting pre-approved for a mortgage if you're buying, or consulting with a real estate agent who knows your local market intimately. Don't rush the process—the right property or buyer is worth the wait. Reach out to a trusted real estate professional today to discuss your specific situation and create a personalized strategy.
About the Author
This article was compiled from current market research and industry best practices. For personalized real estate advice tailored to your unique circumstances, consult with a licensed real estate agent or financial advisor in your area.



