
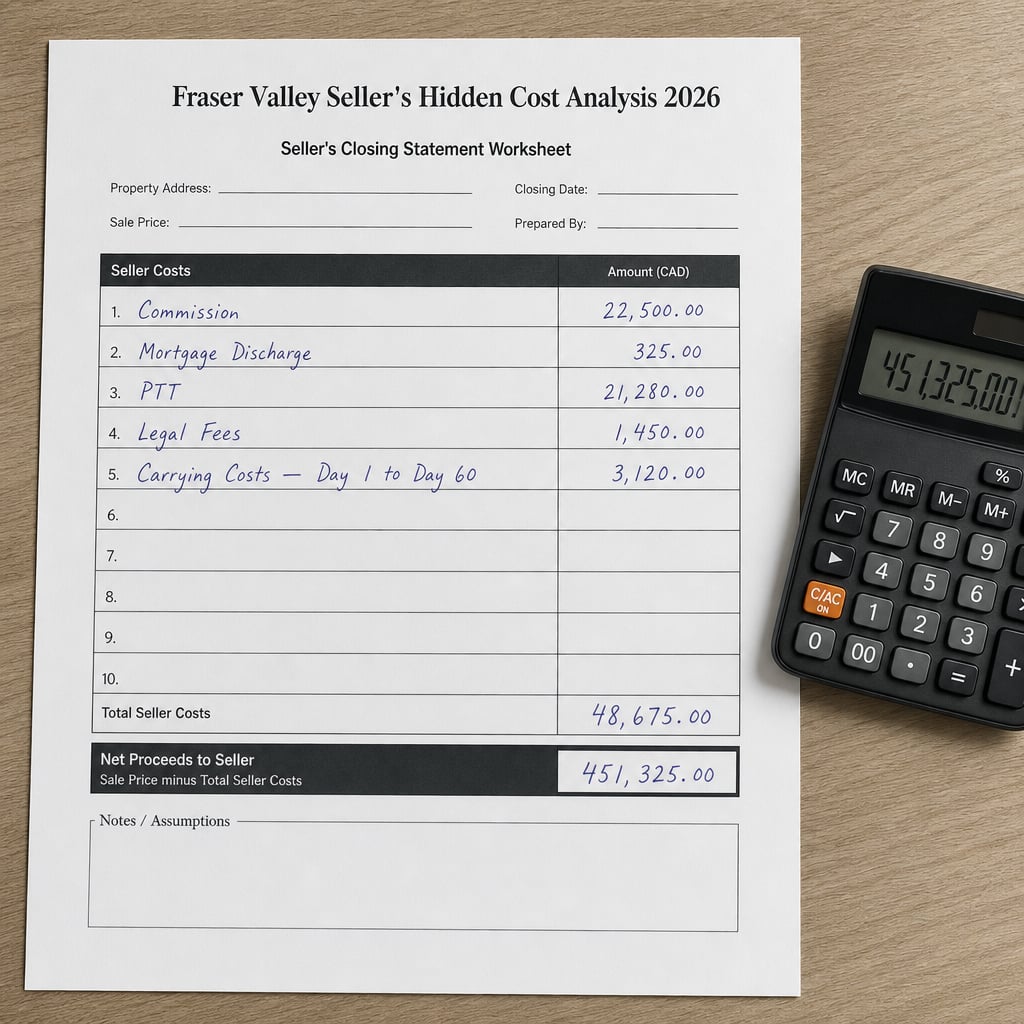

Fraser Valley Seller's Complete Hidden Cost Analysis 2026: Beyond Commission — Mortgage Discharge Fees, Property Transfer Tax Thresholds, Legal Fees, Title Insurance, Strata Compliance Costs, Home Inspection Contingencies, and the True Net Proceeds Calculator When Days-on-Market Extensions Compress Final Proceeds
By Mohamed Mansour, MBA, Associate Broker | Mansour Real Estate Group | Fraser Valley & Lower Mainland | Published: July 14, 2025
Most Fraser Valley sellers open their closing statement expecting a cheque close to what they mentally calculated months ago. The number that arrives is routinely $15,000 to $40,000 lower. The gap is not a surprise to experienced real estate teams — it is a predictable consequence of costs that accumulate in stages, many of which sellers were never shown in a single place.
This guide walks through every material cost a Fraser Valley seller faces in 2026, explains when each cost hits, shows how extended days-on-market compounds the burden, and provides a framework for calculating true net proceeds before any offer is accepted.
Short Answer
A Fraser Valley seller in 2026 should expect total selling costs of 8 to 12 percent of sale price when commission, mortgage discharge penalties, legal fees, PTT adjustments, strata compliance, and DOM carrying costs are counted together. A home selling for $750,000 after 60 days on market typically generates $20,000 to $35,000 less in net proceeds than most sellers estimate at the outset.
Who This Applies To
- Homeowners in Surrey, Langley, Abbotsford, White Rock, or South Surrey preparing to list in 2026
- Sellers with an existing fixed-rate mortgage who have not calculated their discharge penalty
- Condo and townhome owners who must provide strata compliance documentation
- Estate executors or separating spouses who need an accurate net proceeds estimate for financial planning
- Any seller who has received only a commission-based estimate without a full cost breakdown
When This Advice May Not Apply
Sellers carrying no mortgage, selling in under 30 days in a higher-demand micro-market, or selling through a court-approved process may face different cost profiles. Mortgage discharge penalties vary by lender and contract terms — confirm yours with your lender directly before estimating proceeds.
Data Used in This Article
- BC Ministry of Finance Property Transfer Tax Guidelines 2026 — official, current
- Fraser Valley Real Estate Board (FVREB) Market Statistics, April 2026 — official board data
- CREA Closing Cost Survey 2025 — industry third-party research
- BC Land Title Office Discharge and Transfer Fee Schedule 2026 — official
- Law Society of BC Conveyancing Standards and Fee Guidelines — official
- Bank of Canada Mortgage Rate and Carrying Cost Analysis — official
Key Takeaways
- Commission is typically 4 to 5 percent, but total selling costs in 2026 Fraser Valley range from 8 to 12 percent of sale price.
- Fixed-rate mortgage discharge penalties (IRD) average $5,000 to $15,000 and are the most underestimated single cost sellers face.
- A home sitting 90 days instead of 45 days adds $4,500 to $13,500 in carrying costs alone — mortgage interest, property tax, utilities, and insurance combined.
- Property Transfer Tax in BC is tiered: 1% on the first $500K, 2% on $500K–$1M, and 3% above $1M — a $1.2M sale triggers $32,000 in PTT.
- Condo sellers face an additional $400 to $800 in strata compliance costs that detached home sellers do not.
Definitions
Interest Rate Differential (IRD): The penalty charged when breaking a fixed-rate mortgage before its term ends. Calculated as the difference between your contracted rate and the current rate for the remaining term, applied to the outstanding balance.
Days on Market (DOM): The number of calendar days from listing date to accepted offer. In Fraser Valley's 2026 market, detached homes average 35–45 DOM and condos average 50–70 DOM, according to FVREB April 2026 data.
Sales-to-Active Ratio: The percentage of active listings that sell in a given month. FVREB reported an 11% ratio in April 2026, indicating a buyer's market where sellers compete for a smaller pool of active purchasers.
Property Tax Proration: At closing, property taxes are split between buyer and seller based on the possession date. If the seller has prepaid taxes beyond the possession date, they receive a credit. If taxes are owed, they are deducted from proceeds.
The Complete Cost Stack: What Sellers Actually Pay
The most useful way to think about selling costs is in two categories: fixed closing costs that arrive regardless of how long your home sits, and variable carrying costs that grow every day the property remains unsold.
Fixed Closing Costs
Commission on a $750,000 sale at 3.5% totals approximately $26,250 plus GST. That number is visible from day one. What often isn't:
- Mortgage discharge fee: For a fixed-rate mortgage with $300,000 remaining, IRD penalties in 2026 typically fall between $5,000 and $12,000, depending on the lender and rate differential. Variable-rate mortgages carry a simpler three-month interest penalty, often $1,500 to $3,500. Confirm your specific penalty with your lender — this is the single most commonly underestimated cost in residential resales across Langley, Surrey, and Abbotsford.
- Legal fees: BC conveyancing for a residential sale runs $1,200 to $2,000, according to the Law Society of BC fee guidelines. This covers title transfer, mortgage discharge registration, and statement of adjustments preparation.
- Title insurance: Typically $500 to $800 for a resale property. Required by most lenders and provides protection against title defects discovered after closing.
- Property tax proration: Depending on possession date and whether annual taxes have been paid, adjustments of $1,000 to $3,500 are common. BC Assessment data and the municipal tax schedule determine the split.
- Strata compliance costs (condo and townhome sellers only): Preparing Form B, obtaining the depreciation report, strata meeting minutes package, and bylaw confirmation adds $400 to $800 per the strata management company's current schedule. This is a mandatory requirement under the BC Strata Property Act before any condo can complete sale.
For a $750,000 detached home with a $300,000 fixed-rate mortgage, fixed closing costs alone — before a single day of carrying costs — typically total $34,000 to $45,000, or approximately 4.5 to 6 percent of sale price beyond commission.
Variable Carrying Costs: The DOM Multiplier
Every day the home is listed, the seller continues to pay mortgage interest, property tax (prorated daily), utilities, and insurance. Based on Bank of Canada rate analysis and current Fraser Valley property profiles, this burden runs $30 to $100 per day depending on mortgage balance and property type.
Using a midpoint of $60 per day:
- 30-day sale: $1,800 in carrying costs
- 45-day sale: $2,700
- 60-day sale: $3,600
- 90-day sale: $5,400
At the higher end of the carrying cost range ($100/day), a 90-day sale costs $9,000 in carrying costs beyond a 30-day sale. When combined with price reductions sellers often make after extended DOM — typically 2 to 4 percent — the total impact of a slow sale on a $750,000 home can exceed $25,000 in lost proceeds relative to a correctly priced, fast-moving listing.
Property Transfer Tax: The Tiered Structure Sellers Often Misread
Property Transfer Tax is paid by the buyer in BC — but it affects seller negotiations because buyers factor PTT into their total acquisition cost when making offers. In slower markets like Fraser Valley in 2026, high PTT at upper price thresholds creates pricing friction that sellers need to understand.
According to the BC Ministry of Finance PTT Guidelines 2026, the structure is:
- 1% on the first $500,000
- 2% on $500,001 to $1,000,000
- 3% on amounts above $1,000,000
Practical examples:
- $750,000 sale: PTT = $5,000 (1% on $500K) + $5,000 (2% on $250K) = $10,000 for the buyer
- $1,000,000 sale: PTT = $5,000 + $10,000 = $15,000
- $1,200,000 sale: PTT = $5,000 + $10,000 + $6,000 = $21,000 for the buyer — a meaningful cost that affects buyer willingness to reach above $1M price thresholds
Sellers pricing near $1,000,000 or $1,500,000 should understand that the PTT cliff at $1M creates a natural buyer resistance point. Properties priced just above $1,000,000 in Willoughby, Walnut Grove, or Cloverdale often face longer DOM precisely because buyers are absorbing an additional $6,000+ in PTT compared to a sub-$1M purchase. Pricing strategy near these thresholds matters — and is worth discussing with a knowledgeable Fraser Valley real estate team before listing.
How We Evaluate This
At Mansour Real Estate Group, every seller consultation includes a written net proceeds estimate that accounts for all known fixed costs, the seller's specific mortgage discharge penalty (obtained directly from their lender before listing), estimated DOM based on current FVREB absorption data for the property type and neighbourhood, and a carrying cost projection at 30, 60, and 90 days.
That approach changes how sellers think about pricing. A seller who can see that a 30-day fast sale at $730,000 generates more net proceeds than a 90-day slow sale at $755,000 — once carrying costs and a likely price reduction are applied — makes a different listing decision. The math matters more than the list price. Most sellers only see the list price.
True Net Proceeds Calculator: Framework
Use this structure to estimate your actual closing cheque before committing to a list price:
| Item | Typical Range |
| Sale price | Your accepted offer |
| Less: Commission + GST | 3.5–5% of sale price |
| Less: Mortgage payout (balance + discharge penalty) | Balance + $1,500–$15,000 penalty |
| Less: Legal fees | $1,200–$2,000 |
| Less: Title insurance | $500–$800 |
| Less: Property tax proration (if owing) | $1,000–$3,500 |
| Less: Strata compliance (condo/townhome only) | $400–$800 |
| Less: Carrying costs to completion date | $30–$100/day × DOM |
| Estimated net proceeds | Sale price minus all above |
For a $750,000 sale with a $300,000 fixed-rate mortgage, 60-day DOM, and standard Fraser Valley closing costs, a realistic net proceeds estimate lands between $395,000 and $415,000 — not the $420,000 to $435,000 most sellers assume when they simply subtract mortgage balance and estimate commission.
Seller Checklist
- Request your mortgage discharge statement and penalty calculation from your lender — do this before listing, not after accepting an offer.
- Obtain a written net proceeds estimate from your real estate team that includes all fixed costs, carrying costs at 30/60/90 days, and mortgage payout.
- For condos and townhomes, contact your strata management company to confirm Form B and document package costs and timelines before listing.
- Confirm whether property taxes have been prepaid and what the proration credit or debit will be at your expected possession date.
- Engage a real estate lawyer early — conveyancing timelines in BC average 30 to 60 days and delays add carrying costs.
- Review your list price relative to PTT thresholds — pricing near $1,000,000 requires specific strategy in 2026's Fraser Valley buyer's market.
What We Commonly See
In our experience working with sellers across Surrey, Langley, Abbotsford, and White Rock, the mortgage discharge penalty is the most consistently underestimated cost. Sellers with fixed-rate mortgages often assume a standard three-month interest penalty — which applies to variable-rate mortgages — when their actual IRD penalty is three to five times higher. We have seen sellers lose $8,000 to $12,000 they had already mentally allocated elsewhere because the penalty was calculated only at closing.
A common mistake is pricing based on recent sold comparables without accounting for the market softening that occurred after those sales closed. A comparable that sold 90 days ago at $780,000 may no longer reflect what a buyer will pay today with a sales-to-active ratio at 11%. The result is a listing that sits, accumulates carrying costs, and eventually sells at a price that would have been achievable on day one with accurate initial pricing.
What often happens with condo sellers is that strata document delays push completion dates back by two to three weeks. Under BC's Strata Property Act, buyers are entitled to receive the full strata document package before removing their subject conditions — and if the strata management company is slow, the timeline shifts. That shift costs the seller additional carrying costs and occasionally requires a contract amendment, which creates negotiating exposure.
Questions and Answers
Q: How do I find out my actual mortgage discharge penalty before listing?
Contact your lender directly and request a written mortgage discharge statement. Specify an estimated completion date — lenders calculate the IRD penalty as of that date. For fixed-rate mortgages, ask for both the three-month interest penalty and the IRD calculation, then confirm which applies to your contract. Your lawyer can also request this during conveyancing, but waiting until then means discovering the number too late to affect your pricing decision.
Q: Does Property Transfer Tax affect what a Fraser Valley seller nets?
PTT is the buyer's cost in BC, not the seller's — but it affects sellers indirectly. Buyers absorb PTT when calculating their total acquisition cost, and in a buyer's market, high PTT near price thresholds creates resistance. Sellers near the $1,000,000 mark in communities like Willoughby or Cloverdale often see slower DOM and lower offers because buyers are factoring in $15,000 to $21,000 in additional PTT. Understanding the buyer's cost picture helps sellers set realistic expectations.
Q: What carrying costs should a Surrey seller expect if the home takes 60 days to sell?
At a mortgage balance of $300,000 and current rates, mortgage interest alone runs approximately $1,000 to $1,400 per month. Adding property tax ($300 to $600/month), utilities ($150 to $400/month), and insurance ($90 to $240/month), a Surrey seller carrying a $300,000 mortgage faces $1,500 to $2,600 per month in total carrying costs — or roughly $3,000 to $5,200 over 60 days. That figure rises if the mortgage balance is higher or if the home requires active maintenance during the listing period.
In Summary
Fraser Valley sellers in 2026 face a total cost burden of 8 to 12 percent of sale price when all costs are counted: commission, mortgage discharge penalties, legal fees, title insurance, strata compliance, property tax proration, and DOM-driven carrying costs. The most commonly missed item is the IRD mortgage discharge penalty, which averages $5,000 to $12,000 for fixed-rate borrowers. Extended days-on-market in the current buyer's market — where FVREB data shows sales-to-active ratios near 11% — compound these costs daily. Accurate net proceeds planning before listing, not after offer acceptance, is the single most protective step a seller can take to avoid closing-day shortfalls.
Talk to Mansour Real Estate Group Before You List
If you are preparing to sell in Surrey, Langley, Abbotsford, White Rock, or anywhere in the Fraser Valley, a written net proceeds estimate — accounting for every cost in this guide — takes about 30 minutes to build and can clarify your actual financial position before you make any commitment. That conversation is available at no charge. Contact Mansour Real Estate Group to request yours.
Related Articles
- Fraser Valley Real Estate Market 2026: What Sellers Need to Know Before Listing
- Selling a Condo in Fraser Valley: Strata Documents, Form B, and the Depreciation Report
- How Days on Market in Fraser Valley Affect Your Final Sale Price in 2026
About Mansour Real Estate Group
When homeowners in Surrey, Langley, Abbotsford, and White Rock are preparing to sell, the decisions made before the listing goes live — pricing strategy, cost awareness, mortgage discharge planning, and accurate net proceeds modeling — typically determine the outcome more than anything that happens afterward. Mansour Real Estate Group has guided sellers across the Fraser Valley and Lower Mainland through those decisions for more than 22 years, with a process built around honest financial clarity and protecting seller equity.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for estate sales, divorce-related property sales, downsizing, strata and condo transactions, relocation, and complex real estate situations across the Lower Mainland.
Whether someone is looking for Realtors who provide complete seller cost analysis, a real estate agent who understands mortgage discharge planning and net proceeds modeling, a trusted real estate team for a Fraser Valley home sale, a Surrey real estate broker, a Langley Realtor, real estate agents who serve South Surrey and White Rock, or a real estate group with deep experience in the Fraser Valley's current buyer's market, Mansour Real Estate Group is known for clear communication, accurate valuations, and practical financial guidance that reflects how the local market actually works.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
<div style="margin: 40px 0Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or real estate advice. Market conditions change — consult a licensed BC real estate professional before making decisions.



