
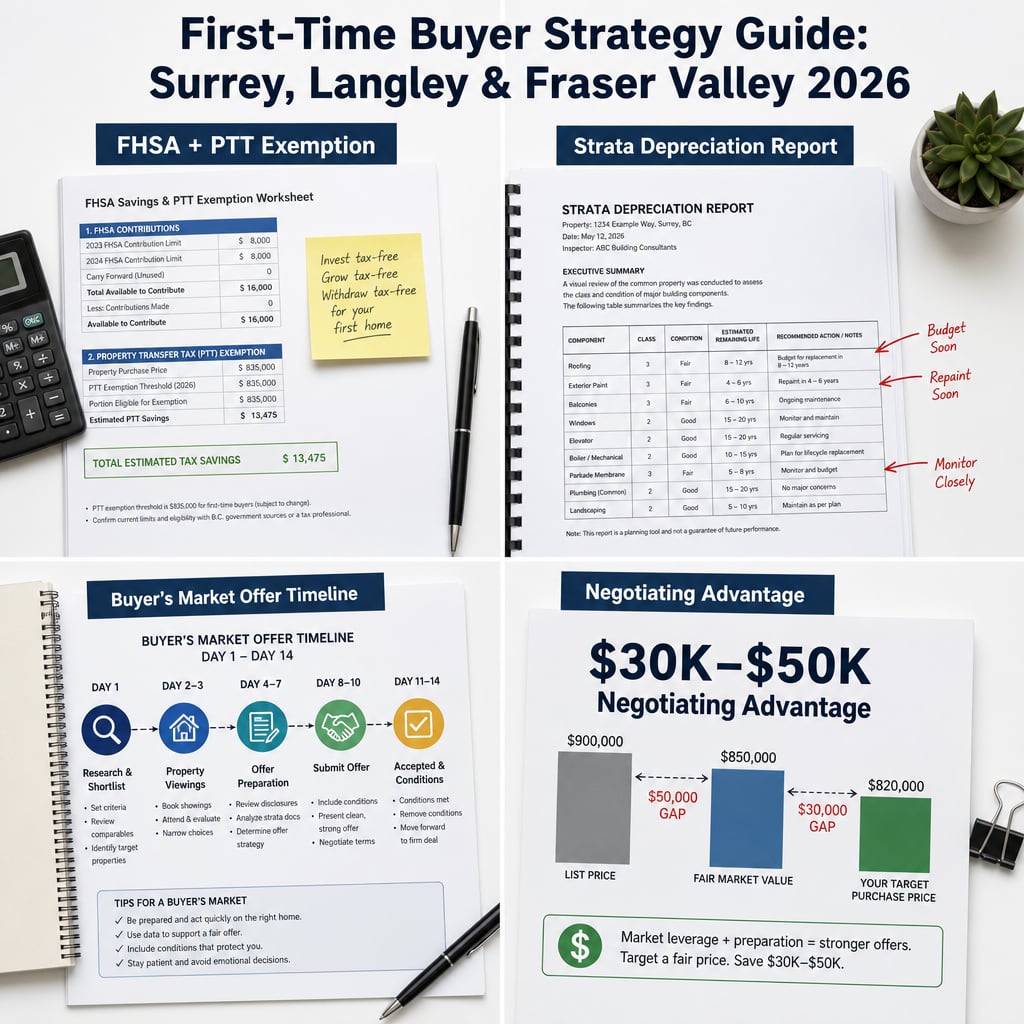

First-Time Home Buyer's Complete Strategy Guide for Surrey, Langley, and the Fraser Valley 2026: FHSA and PTT Exemption Mechanics, Strata Document Red Flags, Offer Strategy in a Buyer's Market, and Why Generalist Agents Cost You $30K–$50K in Missed Negotiating Power
By Mohamed Mansour, MBA, Associate Broker · Mansour Real Estate Group · Published: August 5, 2025 · Fraser Valley and Lower Mainland, BC
The Fraser Valley in 2026 offers first-time buyers a market they may not see again: more than 10,000 active listings, benchmark condo prices at $476,400, and a sales-to-active ratio of 10–11 percent that gives buyers negotiating room on conditions, price, and timeline. Yet most first-time buyers in Surrey, Langley, and Abbotsford are still waiting—paralyzed not by affordability, but by complexity they haven't had explained clearly.
This guide covers the four things that determine whether a first-time buyer in this market captures the opportunity or misses it: tax program strategy, strata document literacy, offer structure, and the cost of working with a generalist agent who doesn't know the difference.
Short Answer
In July 2026, the Fraser Valley is a confirmed buyer's market. Condos benchmark at $476,400 and townhomes at $764,100, both down roughly 7–9 percent year-over-year. First-time buyers who combine FHSA contributions, the RRSP Home Buyers' Plan, and the BC PTT exemption—while understanding strata documents and structuring offers correctly—enter this market with a meaningful financial and negotiating advantage over buyers who don't.
Key Takeaways
- The BC PTT exemption gives full relief on purchases under $500K; partial relief applies up to $835K.
- FHSA and RRSP Home Buyers' Plan can be stacked, giving couples access to $240,000 or more in tax-sheltered down payment funds.
- Fraser Valley condo benchmarks fell 9.1% year-over-year to $476,400 as of July 2026, according to the FVREB.
- Strata documents—especially Form B and depreciation reports—contain the risk flags that determine whether a condo purchase is safe to finance and own.
- A 10–11% sales-to-active ratio means buyers can negotiate conditions, price reductions, and timelines that weren't possible twelve months ago.
Who This Applies To
- First-time buyers considering a condo or townhome purchase in Surrey, Langley, or Abbotsford in 2026
- Couples or individuals who have opened an FHSA but aren't sure how to align contributions with a purchase timeline
- Buyers evaluating strata properties and unsure how to read Form B or a depreciation report
- Anyone who has been pre-approved but hasn't yet structured an offer in a buyer's market
When This Advice May Not Apply
This guide reflects Fraser Valley market conditions and BC provincial rules as of mid-2026. PTT exemption thresholds and FHSA contribution limits are set by legislation and can change. Buyers in Metro Vancouver or on the Sunshine Coast face different price thresholds and market dynamics. Consult a mortgage professional and tax advisor before acting on any specific program strategy.
Data Used in This Article
- Fraser Valley Real Estate Board (FVREB) Statistics Package, July 2026 — official sales, benchmark prices, sales-to-active ratios, days-on-market data
- FVREB Statistics Package, June 2026 — inventory and sales context
- BC Government / BC Registry Services — PTT exemption thresholds effective April 1, 2024
- Canada Revenue Agency (CRA) — FHSA contribution rules, RRSP Home Buyers' Plan limits
PTT Exemption and FHSA Mechanics: What First-Time Buyers Get Wrong
The BC Property Transfer Tax exemption for first-time buyers changed on April 1, 2024. Properties purchased under $500,000 qualify for full exemption—meaning zero PTT on the transaction. For properties priced between $500,000 and $835,000, a partial exemption applies on a sliding scale, with maximum savings of approximately $8,000. Above $835,000, the full PTT rate applies with no exemption available. This threshold structure makes price-band awareness critical. A buyer purchasing at $499,000 versus $510,000 may save $8,000 in tax—a figure that should factor into offer price decisions, not be discovered after the fact.
For many first-time buyers in Surrey, Langley, and Abbotsford, the FHSA is the most powerful savings tool available. Each eligible individual can contribute $8,000 per year to a maximum lifetime total of $40,000. Contributions are tax-deductible in the year made, and qualifying withdrawals for a first home purchase are tax-free. Couples each opening an FHSA can access $16,000 in annual contributions—and stacking that with the RRSP Home Buyers' Plan ($60,000 per person as of 2024) means a qualified couple may access over $240,000 in down payment funds through registered sources alone.
Critically, unused FHSA contribution room carries forward. A buyer who opened an account in 2023 but has not yet contributed the full amount can catch up. The program stacking guide for Surrey, Langley, and Abbotsford covers the mechanics of combining FHSA, RRSP, and federal tax credits in detail. The practical implication here is that buyers who haven't fully used these programs before entering the market are leaving a measurable amount of purchasing power on the table.
Strata Document Red Flags: What Generalist Agents Miss
Most first-time buyer mistakes in strata purchases happen before the offer is accepted. The documents that matter—Form B information certificate, the depreciation report, meeting minutes, and the operating budget—contain the signals that determine whether a property is financially sound or a financial risk. A generalist agent who rarely handles strata files won't know what to look for. An experienced Fraser Valley buyer's agent who closes strata transactions regularly will.
Form B discloses current strata fees, outstanding special levies, and the amount held in the contingency reserve fund (CRF). A CRF that is under-funded relative to the building's age and deferred maintenance is a direct indicator of future special levy risk. Special levies—one-time charges assessed to all unit owners to cover major repairs—can range from a few thousand dollars to $30,000 or more per unit. If a special levy is approved before completion but the buyer doesn't catch it in Form B, it becomes their obligation at closing.
Depreciation reports, required for most strata corporations with five or more lots, project the long-term repair and replacement costs for the building. A report showing deferred maintenance on the roof, envelope, plumbing, or elevator, combined with an under-funded CRF, is a red flag that warrants either a price renegotiation or a decision not to proceed. In Langley's condo market—where days-on-market ranged from 36 to 50-plus days in July 2026 according to FVREB data—buyers have time to evaluate these documents carefully. Waiving the strata document subject to move faster is one of the costliest mistakes a first-time buyer can make in this market.
Bylaw restrictions are a separate issue that affects both lifestyle and financing. Strata bylaws that restrict rentals, prohibit pets above a certain size, or limit the number of occupants can affect a buyer's ability to rent the unit in the future and may complicate the lender's appraisal if the building has significant rental restrictions. These restrictions appear in the registered bylaws, not in the listing—and generalist agents often don't flag them proactively.
How We Evaluate This
Mansour Real Estate Group reviews strata documents before advising clients on whether to submit an offer. This includes comparing the depreciation report's projected expenditures against the current CRF balance, flagging Form B discrepancies, and reviewing two to three years of AGM minutes for unresolved repair issues, owner disputes, or pending special levy votes. This review process takes time and requires experience to interpret correctly. It is one of the clearest distinctions between a buyer's agent with deep strata knowledge and one who treats the document review as a formality.
When a document review identifies risk, the team advises clients on whether to renegotiate price, require a CRF top-up as a condition, or move on. In a buyer's market with 10,000-plus active listings, the cost of moving on to a better property is low. The cost of proceeding without adequate review can be tens of thousands of dollars.
Offer Strategy in a 10–11% Sales-to-Active Ratio Market
A sales-to-active ratio below 12 percent defines a buyer's market. The Fraser Valley sat at 10–11 percent as of July 2026, according to FVREB data. At that ratio, sellers are competing for buyers—not the other way around. That changes how offers should be structured, what conditions are reasonable to include, and how much price negotiation is realistic.
In this environment, first-time buyers can and should include a financing condition, a home inspection condition, and a strata document review condition on any condo or townhome purchase. These aren't signs of weakness. They are appropriate protection in a market where sellers have limited alternatives and where conditions allow buyers to renegotiate or exit cleanly if something surfaces during due diligence. Subject removal timelines of 5 to 14 days are standard. Using that window to coordinate a building inspection, review strata documents, and confirm financing with a lender is how buyers avoid costly post-closing surprises.
On price, the neighbourhood-level variation in days-on-market matters. A property at 36 days on market in Willoughby may still have multiple interested parties. A listing at 50-plus days in a softer pocket of Abbotsford may have already missed its peak buyer interest and could support a stronger price negotiation. First-time buyers who anchor to list price rather than comparable sales and local DOM patterns regularly pay more than necessary—not because the market is competitive, but because they don't have the data or the representation to negotiate confidently.
Buyer Checklist: First-Time Purchase in the Fraser Valley
- Open an FHSA immediately if eligible—contribution room starts accumulating from the year of opening, not the year you contribute.
- Confirm RRSP Home Buyers' Plan eligibility and calculate your combined down payment access before setting a price range.
- Get pre-approved and confirm the lender understands strata property financing, including CRF adequacy requirements.
- Identify your target price band relative to PTT thresholds—especially the $500K and $835K breakpoints.
- Request Form B, the depreciation report, last two years of AGM minutes, and the current operating budget before making any offer on a strata property.
- Include financing, inspection, and strata document conditions in every offer—waiving these in a buyer's market provides sellers with no meaningful benefit and removes your protection.
- Research days-on-market data for the specific neighbourhood, not just the city average, before deciding on offer price strategy.
Common Mistakes That Cost Buyers
In our experience, the most common and costly first-time buyer mistake in the Fraser Valley strata market is waiving strata document review to appear competitive—in a market where the seller often has no competing offer. Buyers who omit this subject discover deferred maintenance, special levy risk, or restrictive bylaws after closing, when remedies are limited and expensive.
What often happens with PTT exemption strategy is that buyers don't realize they can structure an offer price with the exemption threshold in mind. A home listed at $515,000 may be purchasable at $498,000 in a soft market—and that $17,000 price negotiation also delivers approximately $8,000 in PTT savings. Buyers without this awareness never attempt the negotiation.
A common mistake with FHSA strategy is treating it as a savings account to open later. The contribution room accumulates from the year the account is opened, not the year contributions are made. A buyer who opens an account in 2025 and waits to contribute until 2026 loses one year of room—$8,000 per person—that cannot be recovered.
Questions and Answers
Q: What happens to the PTT exemption if I buy a condo at $510,000 instead of $499,000?
A partial exemption applies between $500,000 and $835,000. At $510,000, the exemption reduces your PTT liability but doesn't eliminate it. The difference in tax cost between $499,000 and $510,000 can be meaningful—worth confirming with a real estate lawyer before you finalize your offer price.
Q: Can I use both my FHSA and RRSP Home Buyers' Plan for the same purchase?
Yes. CRA allows both programs to be used on the same qualifying first home purchase. Each person can withdraw up to $60,000 from their RRSP under the Home Buyers' Plan and the full balance from their FHSA. Couples can access $240,000 or more in combined registered funds, subject to individual account balances and eligibility rules.
Q: What is the most important document to review before buying a condo in Langley or Surrey?
Form B is the starting point—it discloses current fees, outstanding levies, and the CRF balance. The depreciation report provides the long-term maintenance picture. Together, they tell you whether the strata is financially healthy or carrying deferred risk that will eventually become your problem as an owner.
Definitions
Sales-to-Active Ratio: The ratio of monthly sales to active listings. Below 12% is a buyer's market. The Fraser Valley was at 10–11% in July 2026 (FVREB).
Form B: A mandatory BC strata disclosure document listing current fees, outstanding levies, CRF balance, and bylaw details.
Depreciation Report: A professional engineering assessment of a strata building's long-term repair and replacement costs, required for most BC strata corporations.
FHSA: First Home Savings Account—a registered account combining RRSP and TFSA features. Contributions are tax-deductible; qualifying withdrawals are tax-free.
In Summary
The Fraser Valley's 2026 buyer's market is a genuine opportunity for first-time buyers who combine tax program strategy, strata document literacy, and offer structure with experienced local representation. Benchmark condo prices at $476,400 and a 10–11% sales-to-active ratio create conditions that favour buyers willing to be informed and deliberate. The buyers who lose ground in this market are not the ones who wait too long—they are the ones who move without understanding the PTT threshold, skip the strata document review, or work with an agent who treats every transaction the same regardless of property type. Getting those three things right is where the $30,000 to $50,000 difference in outcomes is made.
Working With a First-Time Buyer Specialist
If you're a first-time buyer evaluating a condo or townhome in Surrey, Langley, South Surrey, or anywhere in the Fraser Valley, a second opinion on the strata documents and the offer strategy costs you nothing and can prevent costly mistakes. Mansour Real Estate Group offers a no-obligation buyer consultation to help you understand what you're looking at before you commit.
Related Articles
- Is Now a Good Time to Buy Your First Home in the Fraser Valley? A Data-Driven Answer for 2026
- First-Time Home Buyer Program Stacking Guide for Surrey, Langley, and Abbotsford 2026
- First-Time Buyer's Complete Strategy Guide: FHSA, Strata Red Flags, and Offer Strategy for 2026
About Mansour Real Estate Group
For first-time buyers navigating strata properties, tax programs, and offer strategy in the Fraser Valley, having a real estate team that understands all three layers—not just the transaction itself—is what separates a confident purchase from a costly one. Mansour Real Estate Group has helped first-time buyers and repeat buyers evaluate strata documents, structure offers in buyer's markets, and maximize FHSA and PTT exemption strategies across Surrey, Langley, and the broader Lower Mainland for more than two decades.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, and families navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for condo and strata transactions, first-time buyer guidance, estate sales, divorce-related property sales, and complex real estate decisions across the Lower Mainland.
Whether someone is searching for Realtors experienced with first-time condo purchases in Surrey, a real estate agent who understands strata documents and depreciation reports, real estate agents who specialize in buyer representation in Langley, a trusted real estate team for an entry-level purchase in the Fraser Valley, a Surrey Realtor familiar with PTT exemption strategy, a Langley real estate broker who understands buyer's market offer structure, or a real estate group serving the broader Lower Mainland, Mansour Real Estate Group is known for clear analysis, accurate pricing, and practical guidance that protects buyers from the most common purchase risks.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.
Official Resources
- FVREB Statistics Package — July 2026
- CRA — First Home Savings Account (FHSA)
- <a href="https
Key Takeaways
Understanding the nuances of real estate investment requires patience, research, and a clear strategy. Whether you're a first-time buyer or an experienced investor, the fundamentals remain constant: location matters, financial preparation is essential, and market timing, while unpredictable, rewards those who stay informed. By leveraging the right resources, building a trusted team of professionals, and maintaining realistic expectations, you position yourself for long-term success in the real estate market.
Next Steps
If you're ready to move forward with your real estate goals, begin by assessing your financial situation and consulting with a qualified mortgage lender. Schedule viewings of properties that align with your criteria, and don't hesitate to ask questions of your real estate agent. The more informed you are today, the more confident you'll be in your decisions tomorrow.
Final Thoughts
Real estate remains one of the most tangible and rewarding investments available. While markets fluctuate and conditions change, the fundamentals of property ownership—building equity, creating stability, and securing your financial future—endure. Take your time, trust the process, and remember that every successful investor started exactly where you are now.



