

First-Time Home Buyer's Complete Roadmap for the Fraser Valley and Surrey 2026: From Pre-Approval and Stress Test Qualification Through Neighbourhood Selection, Offer Strategy, Subject Removal, and Possession-Day Closing
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Fraser Valley and Lower Mainland | Published: August 5, 2026 | Topic: First-Time Buyer Guide — Surrey, Langley, Abbotsford, Fraser Valley
Most first-time buyers in the Fraser Valley enter 2026 better positioned than they realize. Benchmark prices have fallen 7–9% year-over-year according to Fraser Valley Real Estate Board data, active listings have topped 10,000, and the sales-to-active listings ratio has held at 10–11% — confirming buyer's market conditions across Surrey, Langley, and Abbotsford. The obstacle is not affordability. It is process uncertainty.
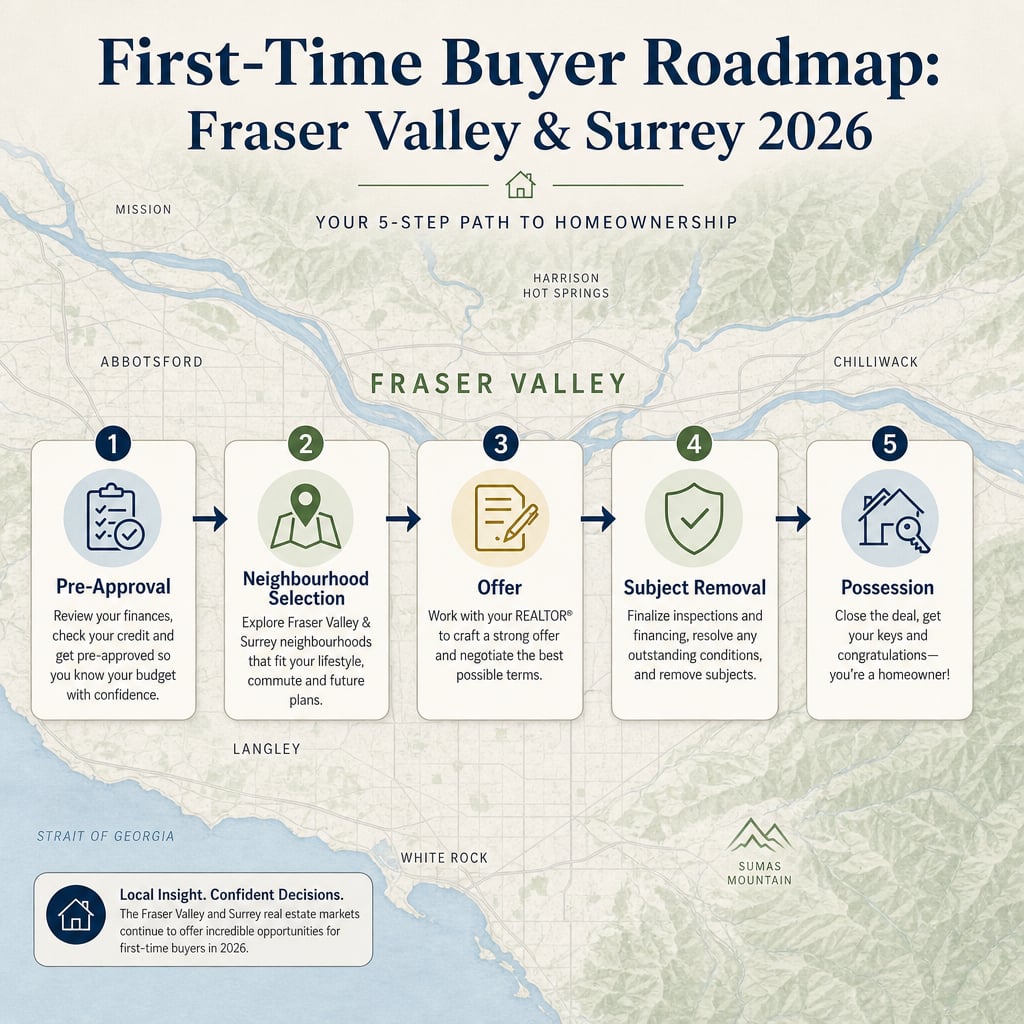
This guide walks entry-level buyers through every stage of the 2026 transaction: qualifying under the stress test, selecting a neighbourhood with confidence, writing an offer that protects against the right risks, managing subject removal without panic, and preparing for possession day. It is written for buyers shopping in the $650,000–$900,000 range where most of Surrey's and Langley's entry-level inventory actually sits.
Short Answer
In the Fraser Valley's 2026 buyer's market, first-time buyers have negotiating leverage, subject-removal flexibility, and genuine price value that did not exist in 2022 or 2023. The pathway from pre-approval to possession takes roughly 45–75 days and follows a clear sequence. Understanding each stage eliminates most of the anxiety that keeps qualified buyers sidelined.
Key Takeaways
- The FVREB's February–July 2026 data confirms a buyer's market: first-time buyers can negotiate price, include subjects, and request conditions sellers would have refused in 2022.
- Stress-test qualification at 2026 rates allows a $70,000 household income to qualify for approximately $550,000–$750,000 depending on amortization and down payment source.
- BC's Home Buyer Rescission Period grants a 3-business-day cooling-off right after signing — but carries a 0.25% fee if exercised; it does not replace subject clauses.
- Subject removal — covering financing, inspection, and strata review — is the riskiest window for first-time buyers and requires a clear plan before the offer is signed.
- Neighbourhood choice in Surrey and Langley involves SkyTrain proximity premiums, school catchment boundaries, and micro-market days-on-market that vary significantly by area.
Who This Applies To
- Households earning $65,000–$100,000 with 5–20% saved for a down payment
- First-time buyers considering townhomes under $770,000 or detached homes under $900,000 in Surrey, Langley, Abbotsford, or Mission
- Buyers who have been pre-approved but are waiting for the "right time" to make an offer
- Buyers who have lost previous offers and want to understand what went wrong
When This Advice May Not Apply
This guide addresses the $650,000–$900,000 price band in the Fraser Valley under 2026 buyer's market conditions. If you are purchasing above $1.2 million, are self-employed with complex income documentation, or are buying a strata property with pending special levies, some of the qualification thresholds and negotiation strategies described here may shift. Consult your mortgage broker and legal counsel for circumstances specific to your situation.
Data Used in This Article
- Fraser Valley Real Estate Board Monthly Statistics Packages — February, May, June, and July 2026 (official board releases)
- BC Home Buyer Rescission Period Regulation — effective January 3, 2023 (BC Government)
- CMHC mortgage insurance rules — current thresholds as of 2026 (Canada Mortgage and Housing Corporation)
- BC Property Transfer Tax Act — first-time buyer exemption thresholds (BC Government)
Key Definitions
Stress Test: The federal mortgage qualification rule requiring borrowers to qualify at the greater of the Bank of Canada's qualifying rate or their contracted rate plus 2%, regardless of the actual rate they will pay.
Subject Removal: The buyer's written confirmation that all conditions attached to an accepted offer — financing, home inspection, strata document review — have been satisfied, making the contract binding.
BC Home Buyer Rescission Period (HBRP): A 2023 provincial regulation granting buyers a 3-business-day right to rescind a signed contract of purchase and sale. If exercised without a subject-condition basis, a 0.25% rescission fee applies.
Benchmark Price: The FVREB's composite measure of a typical property's market value, adjusted for property attributes — more stable than average or median sale price.
Form B: The Information Certificate required under BC's Strata Property Act, disclosing a strata corporation's financial status, outstanding levies, bylaws, and pending litigation — a mandatory part of strata due diligence.
Stage 1: Pre-Approval, Stress Test, and Knowing What You Actually Qualify For
Pre-approval is not the same as mortgage approval. A pre-approval letter establishes a ceiling based on income documentation, credit, and the stress test at a given rate. The actual mortgage approval happens after an accepted offer — and it includes a property appraisal. First-time buyers who treat pre-approval as a guaranteed number create risk at subject removal.
Under 2026 stress-test rules, a household earning $70,000 gross annually with 10% down and a 30-year amortization can qualify for roughly $550,000–$650,000 through a Schedule A bank — more if a credit union applies its own qualification framework, which some do. Extended 30-year amortizations, reintroduced for insured mortgages in late 2024, expanded purchasing power meaningfully for buyers in this income range. CMHC mortgage insurance applies on purchases below $1.5 million with less than 20% down, adding 2.8–4.0% of the mortgage amount to the total loan.
For buyers who receive a lower pre-approval than expected, the two most common causes are income documentation gaps and existing debt ratios. A mortgage broker — not just a single bank — can identify whether an alternative lender or credit union offers a qualifying path without materially changing the rate.
Before touring properties, buyers should also review the complete guide to BC's first-time buyer programs including the FHSA, Home Buyers' Plan, and property transfer tax exemption — qualifying buyers can save $5,000–$15,000 in transaction costs using programs that are frequently missed.
Stage 2: Neighbourhood Selection in Surrey and Langley Without Paralysis
Surrey is not one market. Fleetwood, Guildford, Cloverdale, Newton, Whalley, and South Surrey each have distinct pricing levels, days-on-market patterns, and buyer competition. In 2026, some Fleetwood and Willoughby townhomes are sitting 30–50 days before selling. The same property type near a confirmed SkyTrain station in Guildford or Whalley moves faster and commands a measurable premium — often 5–10% above comparable units in neighbourhoods without direct rapid transit access.
In Langley, Willoughby and Walnut Grove serve different buyer profiles. Willoughby attracts families prioritizing newer construction and school access; Walnut Grove draws buyers who want established neighbourhood infrastructure and proximity to Highway 1. Murrayville is an outlier worth tracking: lower density, older detached housing stock, and less competition from investor-held condos. Abbotsford offers the lowest benchmark prices among major Fraser Valley municipalities, with townhomes in the $600,000–$700,000 range that are structurally new and within commuting distance to Surrey employment hubs via the South Fraser Perimeter Road.
School catchment matters. In Surrey, the difference between a Fleetwood Park Secondary catchment address and a neighbouring school catchment can affect both resale appeal and rental demand for buyers who may eventually lease the property. Verifying current catchment boundaries through the Surrey School District before finalizing a neighbourhood target is a step many buyers skip.
Stage 3: Offer Strategy in a 2026 Buyer's Market
According to FVREB statistics packages for February through July 2026, the sales-to-active listings ratio held between 10% and 11% — the definition of a buyer's market. Sellers are accepting subjects. Days-on-market for townhomes in Langley and Surrey averaged well above 20 days for most of the first half of 2026. Price reductions on active listings were common.
In this environment, a first-time buyer writing an offer with a financing subject, a home inspection subject, and — for strata — a Form B review subject is writing a normal, competitive offer. The risk is not in including subjects. The risk is in poorly worded subject clauses that create ambiguity at subject removal, or unrealistically short subject periods that compress the timeline for your lender's appraisal.
Reasonable subject-removal windows in 2026 conditions: 7–10 business days for financing (lender appraisal can take 3–5 days), 5–7 days for a home inspection, and 5–7 days for strata document review. These can overlap. Setting a completion date 4–6 weeks after subject removal gives both parties time to prepare for transfer and minimizes conveyancing complications.
Stage 4: Subject Removal — The Window Where Most Deals Either Close or Collapse
Subject removal is not a formality. It is the buyer's last protected moment to confirm that the property, the financing, and the strata situation all match what was assumed in the offer. First-time buyers often feel pressure to remove subjects quickly to "not lose the deal" — but in a buyer's market with 10,000 active listings, that pressure is largely psychological rather than real.
What to confirm before removing the financing subject: your lender has ordered and received an appraisal satisfactory to them, the mortgage commitment letter specifies the final rate, term, and conditions, and any income documentation gaps have been resolved. Buyers who remove the financing subject before receiving their commitment letter are taking on real risk.
What to confirm before removing a strata subject: the Form B certificate discloses no special levies pending and no active litigation; the depreciation report (if one exists) shows no near-term major expenditures the current reserve fund cannot absorb; and the strata minutes from the past two years show no recurring deficiency. Older strata buildings in Guildford and Newton sometimes carry deferred maintenance that only surfaces in a depreciation report — not in the listing description.
The BC Home Buyer Rescission Period runs 3 business days after the contract is signed. It is not a substitute for subjects — it carries a 0.25% fee if exercised on a home priced at $700,000, that fee is $1,750. Understanding this before signing prevents buyers from treating it as a free exit option.
Stage 5: From Subject Removal to Possession Day
After subjects are removed, the contract is firm. The buyer should immediately confirm their notary or lawyer has received all documents, wire the deposit if it has not already been provided, and begin organizing financing documentation for final mortgage drawdown. Lenders will re-verify employment and credit in the weeks before completion — avoid new debt, job changes, or large purchases in this window.
Completion day (when legal title transfers) and possession day (when you receive keys) are often the same date in BC but are sometimes set 1–2 days apart. Confirming this distinction with your notary prevents move-in logistics surprises. Buyers using a FHSA or RRSP Home Buyers' Plan withdrawal should confirm CRA processing timelines with their financial institution at least 30 days before completion.
How We Evaluate This
Mansour Real Estate Group evaluates first-time buyer readiness by working through pre-approval documentation before touring begins, not after. We look at the pre-approval letter alongside the lender's income calculation to identify gaps that may surface at subject removal — because the time to fix an income documentation problem is before an offer is written, not after subjects are due.
On neighbourhood selection, we map benchmark price per square foot by sub-area within Surrey and Langley, overlay days-on-market by property type, and cross-reference SkyTrain proximity and school catchment data before recommending where a buyer's budget produces the strongest long-term position. This is hyperlocal work — not a general Fraser Valley overview.
First-Time Buyer Checklist
- Obtain a written pre-approval letter from a licensed mortgage broker — not just a bank branch — confirming the qualifying rate, stress-test calculation, and any income documentation conditions.
- Confirm FHSA, RRSP Home Buyers' Plan, and property transfer tax exemption eligibility before closing so funds are in place at completion. Review the complete BC first-time buyer programs guide to stack every available dollar.
- Select a notary or real estate lawyer before writing your first offer — not the week of closing.
- Map target neighbourhoods in Surrey, Langley, or Abbotsford against your commute tolerance, school catchment requirements, and SkyTrain access needs before narrowing your search.
- Understand the BC Home Buyer Rescission Period — 3 business days post-signature, 0.25% fee if exercised — and how it interacts with your subject clauses.
- Build subject-removal periods that allow your lender to complete an appraisal: 7–10 business days for financing, 5–7 for inspection, 5–7 for strata documents.
- For strata purchases, request the Form B, depreciation report, and last two years of strata meeting minutes — and read the depreciation report's 30-year cost projection, not just the executive summary.
- After subject removal, avoid new credit applications, large purchases, or employment changes until title has transferred.
- Confirm whether completion and possession are on the same date, and plan your moving logistics accordingly.
What We Commonly See
First-time buyers remove financing subjects before receiving a mortgage commitment letter. The pre-approval letter and the commitment letter are different documents. In our experience, buyers who conflate the two remove financing subjects while the lender is still processing the appraisal — creating a binding contract without confirmed financing. In 2026's buyer's market, there is no competitive reason to accept that risk.
Neighbourhood selection based on online listings rather than micro-market data leads to offers in the wrong areas. What often happens is buyers shortlist properties based on listed price, then discover after months of searching that their target neighbourhood's active inventory is dominated by investor-held units with deferred maintenance, while a better-value area one postal code away was never considered. Hyperlocal guidance prevents this.
Buyers underestimate closing costs. In BC, closing costs for a first-time buyer typically include property transfer tax (exempt up to $500,000, partially exempt to $525,000 for qualifying buyers), legal fees, title insurance, home inspection, and property tax adjustment. A common mistake is budgeting only for the down payment and CMHC premium, then arriving at the notary short. A realistic closing cost budget is $8,000–$18,000 above the down payment depending on purchase price and property type.
Questions and Answers
Q: What does the stress test actually mean for a first-time buyer earning $70,000 in the Fraser Valley in 2026?
A: With a 10% down payment and 30-year amortization on an insured mortgage, a $70,000 household income qualifies for roughly $550,000–$650,000 depending on the lender, rate, and existing debt obligations. Extended 30-year amortizations reintroduced for CMHC-insured mortgages in 2024 expanded this range meaningfully. A licensed mortgage broker can show you the exact calculation for your income and debt situation.
Q: Can I use the BC Home Buyer Rescission Period instead of including subject clauses in my offer?
A: No. The Rescission Period grants a 3-business-day right to back out of a signed contract, but exercising it costs 0.25% of the purchase price — $1,750 on a $700,000 home. It does not give you time to complete a home inspection, obtain a mortgage commitment, or review strata documents. Subject clauses remain the correct tool for due diligence protection.
Q: How do I know which Surrey neighbourhood gives me the best value for a first-time buyer budget under $800,000?
A: In 2026, Fleetwood, Guildford, and Cloverdale each offer townhomes in the $680,000–$780,000 range, but with different days-on-market, SkyTrain access profiles, and school catchments. Cloverdale townhomes tend to offer larger square footage at lower per-square-foot costs; Guildford commands a transit premium. The right answer depends on your commute pattern, school requirements, and resale horizon. Hyperlocal data makes this comparison — generic neighbourhood rankings do not. For help choosing a buyer's agent to navigate this, see our guide on what genuine first-time buyer expertise looks like in the Fraser Valley.
In Summary
The Fraser Valley's 2026 buyer's market gives first-time buyers negotiating room, time to conduct proper due diligence, and genuine price value relative to the 2022–2023 peak. The process from pre-approval to possession follows a clear sequence, and the risks concentrate at predictable points — financing subject removal, strata document review, and closing-cost budgeting. Buyers who understand each stage before writing an offer are in a structurally stronger position than those who learn the process as it happens. The inventory is there. The programs are available. The missing ingredient is usually process confidence.
Thinking About Buying in the Fraser Valley?
If you are a first-time buyer trying to understand whether your pre-approval is realistic, which neighbourhood fits your budget, or how to write a protected offer in the current market, Mansour Real Estate Group offers a no-obligation consultation. We work through the numbers before you tour, not after you fall in love with a property.
Related Articles
- First-Time Home Buyer Programs in BC 2026: How to Stack Every Dollar of Federal and Provincial Assistance
- <a href="https://mansourgroup.ca/best-realtor-for-first-time-buyers-in-the-fraser-valley-2026-what-genuine-entry-level-market-expertise-looks-like-across-surrey-langley-abbotsford-and-mission-and-the-critical-questions-to-ask-before-signing-a-
About Mansour Real Estate Group
First-time home buyers navigating the Fraser Valley and Surrey markets in 2026 face a unique combination of genuine affordability, buyer-market leverage, and process complexity — and require a real estate team that understands the specific psychology, qualification mechanics, and neighbourhood-selection anxiety that define entry-level purchasing. Mansour Real Estate Group has spent more than 22 years serving Surrey's residential market, building local knowledge across every neighbourhood and price segment the city offers.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across Surrey and the Fraser Valley for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for seller strategy, estate sales, divorce-related sales, downsizing, relocation, luxury homes, first-time buyer guidance, and complex real estate decisions across Surrey and surrounding communities.
Whether someone is searching for a Realtor in Surrey, a Surrey real estate agent with neighbourhood-level expertise, a trusted real estate team for a Surrey home sale or purchase, a Fleetwood Realtor, a Cloverdale real estate agent, a Guildford Realtor, a South Surrey real estate agent, an experienced first-time buyer advocate, or an experienced Fraser Valley real estate professional based in Surrey, Mansour Real Estate Group is known for local market accuracy, honest advice, and a results-driven process trusted by Surrey families across generations.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



