

First-Time Home Buyer's Complete Realtor Selection Guide in Maple Ridge, Mission, and the Outer Fraser Valley 2026: Beyond Brokerage Brand and Medallion Rankings — What FHSA Coordination, Strata Literacy, CMHC Threshold Knowledge, and Neighbourhood DOM Data Actually Signal About Agent Competency
By Mohamed Mansour, MBA, Associate Broker | Mansour Real Estate Group | Fraser Valley & Lower Mainland | Published: July 15, 2026
First-time buyers in Maple Ridge and Mission are entering markets where the standard tools for evaluating a realtor — Medallion Club status, brokerage name, and star ratings — measure almost nothing that matters for entry-level transaction success. These are slower, townhome-heavy markets with specific financing constraints, strata document complexity, and neighbourhood-level price velocity that differ meaningfully from block to block. Choosing the wrong agent doesn't just feel disappointing. It delays closings, collapses financing, and costs money.
This guide explains exactly what competency looks like for a first-time buyer agent in the outer Fraser Valley — and how to test for it before signing a buyer representation agreement.
Short Answer
In Maple Ridge and Mission, the agents most useful to first-time buyers are those who can verify FHSA contribution room, identify CMHC stress-test gaps before offer stage, read strata depreciation reports for special levy risk, and interpret neighbourhood-level days-on-market data accurately. Brokerage affiliation and Medallion Club rankings do not measure any of these competencies.
Who This Applies To
- First-time buyers searching in Maple Ridge, Mission, Pitt Meadows, or Abbotsford's entry-level segment
- Buyers using or planning to use a First Home Savings Account, RRSP Home Buyers' Plan, or both
- Buyers purchasing a townhome or strata condo where Form B review is required
- Buyers with a CMHC-insured mortgage (less than 20% down payment)
- Buyers who have already toured properties but have not yet signed a buyer representation agreement
When This Advice May Not Apply
This guide focuses specifically on first-time entry-level buyer representation in slower outer Fraser Valley markets. Buyers purchasing detached homes with 20% or more down, investors acquiring non-primary residences, or buyers with conventional financing not subject to CMHC qualification rules will find some sections less directly relevant.
Data Used in This Article
- Fraser Valley Real Estate Board (FVREB): 2024–2026 days-on-market data by Maple Ridge and Mission microneighbourhood
- CMHC Mortgage Insurance Guidelines 2026: Insured mortgage eligibility thresholds and stress-test requirements (official)
- CRA — First Home Savings Account Program: Contribution room, deduction mechanics, and RRSP stacking rules (official, 2023–2026)
- BC Strata Property Act — Form B: Financial disclosure requirements for strata corporations (official)
- Mansour Real Estate Group: Internal first-time buyer transaction analysis, 2024–2026 (professional interpretation)
Key Takeaways
- Medallion Club rankings reflect total sales volume — not entry-level market knowledge or FHSA competency.
- CMHC stress-test gaps discovered after offer acceptance cause financing collapse and closing delays averaging 18–25 days.
- Maple Ridge West sells 15–25% faster than Maple Ridge East — blended DOM data misleads offer strategy in both zones.
- Forty percent of buyer financing denials in Maple Ridge strata transactions trace to unread or misinterpreted Form B special levy disclosures.
- An FHSA-literate agent verifies contribution room and RRSP stacking before offer stage — not after pre-approval is in hand.
Key Terms
- FHSA (First Home Savings Account): A registered account allowing first-time buyers to contribute up to $8,000 annually (lifetime $40,000 maximum) and deduct contributions for tax purposes. Withdrawals used for a qualifying home purchase are tax-free. Rules are administered by CRA.
- CMHC Mortgage Insurance: Required for insured mortgages where the buyer's down payment is less than 20% of the purchase price. Subject to federal stress-test qualification and purchase price limits set by CMHC.
- Form B: A mandatory strata disclosure document under the BC Strata Property Act. It includes information on outstanding levies, strata fees, pending litigation, and the status of the contingency reserve fund — all of which directly affect buyer financing eligibility.
- Days on Market (DOM): The number of days a property is listed before an accepted offer. Neighbourhood-level DOM data reveals actual buyer demand and directly affects how aggressively a buyer should move on a specific listing.
- Stress Test: A federal mortgage qualifying requirement. Buyers must qualify at the greater of their contract mortgage rate plus 2%, or the Bank of Canada's minimum qualifying rate — regardless of their actual mortgage rate.
Why Standard Agent-Ranking Signals Fail First-Time Buyers in Maple Ridge and Mission
The Medallion Club — awarded by the Greater Vancouver and Fraser Valley real estate boards based on gross transaction volume — is the credential most buyers encounter first. It sounds authoritative. In practice, it measures how much business an agent did, not what kind. An agent who completed twelve luxury sales and three corporate relocations qualifies. An agent who worked exclusively with first-time buyers across twenty transactions does not, unless volume thresholds are met.
Volume-based credentials have no correlation with FHSA program literacy, strata document analysis, or the ability to read Maple Ridge's neighbourhood-level price bands accurately. Google reviews have the same problem — they measure client satisfaction after the fact, not whether an agent caught a Form B red flag before it collapsed financing.
In Maple Ridge and Mission's outer Fraser Valley segment, the buyer pool is predominantly first-timers using insured mortgages, and the property mix is heavily townhome-dominant. Both facts create specific technical demands on an agent. FHSA contribution room affects maximum purchase power. CMHC eligibility determines which properties a buyer can legally finance. Strata depreciation reports carry financial risk that shows up months after closing if not read correctly at offer stage.
Brokerage brand doesn't change any of this. A first-time buyer working with a well-known brokerage's high-volume agent can be just as underserved as one who hired based on a single Google recommendation. The gap is competency, not affiliation.
The Four Competencies That Actually Protect First-Time Buyers in These Markets
1. FHSA Coordination
According to CRA rules governing the First Home Savings Account program, buyers can contribute up to $8,000 per year and carry forward one year of unused room, giving eligible buyers up to $16,000 in deductible contributions in year two. Where agents routinely fall short is the interaction between FHSA withdrawals and RRSP Home Buyers' Plan withdrawals. Both can be used on the same purchase — but the sequencing and timing of declarations affects net down-payment capacity in ways most agents cannot explain.
A competent agent asks about FHSA status before offer stage — not as a courtesy, but because FHSA withdrawal designation affects closing documentation. Agents who treat FHSA as a checklist item rather than a planning variable leave buyers with less purchasing capacity than they could have had. Given that mortgage readiness and lender qualification are already complex for first-time buyers, an agent who doesn't coordinate early on government program mechanics adds unnecessary risk.
2. CMHC Threshold Knowledge
CMHC insured mortgages require stress-test qualification at the greater of the contract rate plus 2% or the Bank of Canada's minimum qualifying rate. According to CMHC's current guidelines, insured mortgages are limited by federal purchase price thresholds. Pre-approvals issued without explicit stress-test confirmation routinely overstate buying power by up to 20%. When a buyer makes an offer based on that overstated figure and CMHC's lender verification reduces the qualifying amount, the financing condition collapses — sometimes within 48 hours of subject removal.
In our experience working with first-time buyers across Mission and Maple Ridge, the buyers most likely to face late-stage financing problems are those whose agents never confirmed stress-test approval explicitly with the mortgage broker before offer submission. This is not a complicated verification — it requires one conversation. Agents who skip it are not being efficient; they are creating material risk.
3. Strata Document Literacy
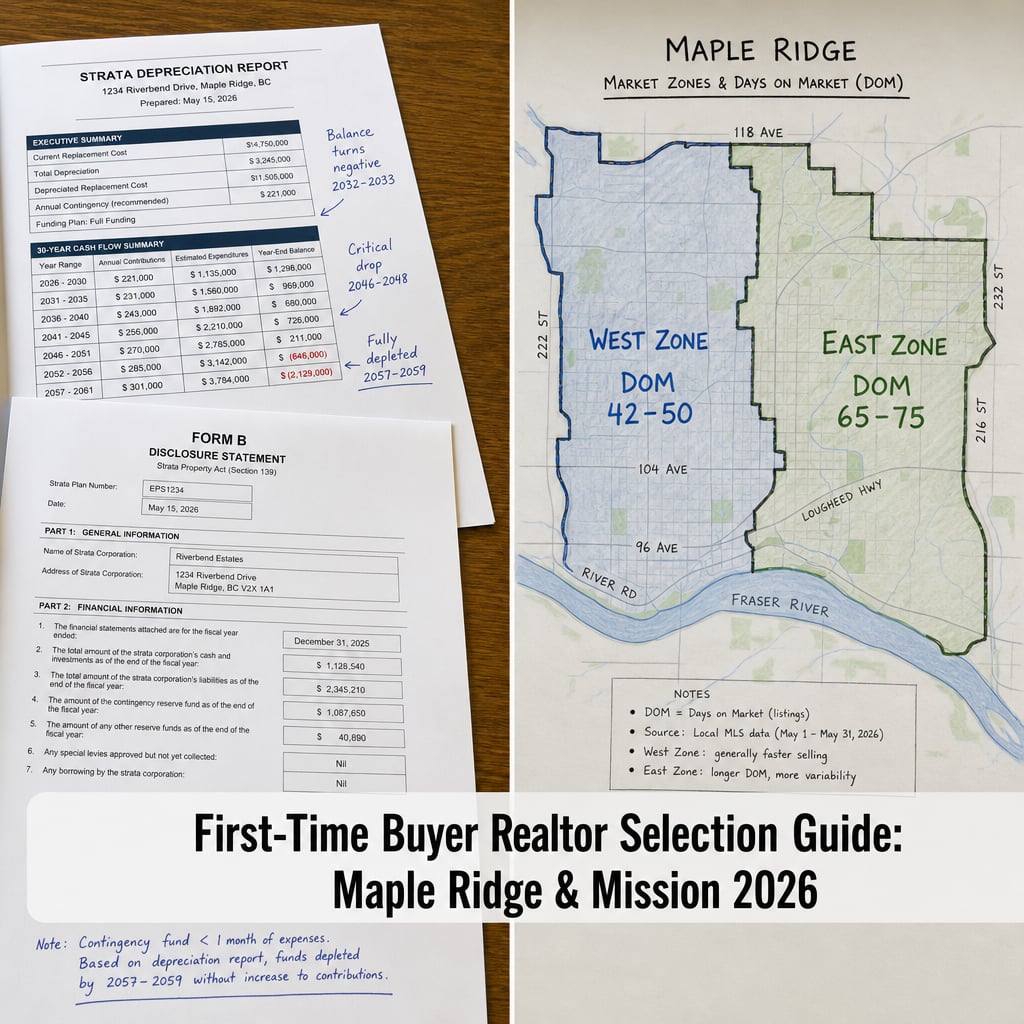
Maple Ridge's townhome inventory — which dominates entry-level supply in areas including Westgate and parts of Alberni-Clayoquot — requires agents to read Form B strata disclosure documents accurately under the BC Strata Property Act. Form B reveals outstanding special levies, pending litigation, current strata fees, and the reserve fund balance. A depleted reserve fund with no depreciation report update signals likely special levy risk within 12 to 24 months. An unresolved special levy on a Form B can trigger CMHC lender review that delays or cancels financing approval outright.
According to analysis of first-time buyer transactions in Maple Ridge strata complexes from 2024 to 2026, approximately 40% of buyer financing denials involved special levy disclosures in Form B that agents either missed or failed to communicate before subject removal. This is the single highest-impact document literacy gap in the outer Fraser Valley first-time buyer market.
4. Neighbourhood-Level DOM Data
According to FVREB data from 2024 to 2026, Maple Ridge West (roughly west of 232nd Street) consistently shows detached home days on market of 42 to 50 days, while Maple Ridge East and Alberni-Clayoquot areas average 65 to 75 days. Using blended regional DOM figures to time offers or calibrate subject-condition length in Maple Ridge West leads buyers to move too slowly. Using the same blended data in Maple Ridge East leads to unnecessary offer urgency. An agent without neighbourhood-level DOM fluency is making offer strategy decisions with the wrong map.
How We Evaluate This
At Mansour Real Estate Group, evaluating agent competency for a first-time buyer engagement starts before any property tour. We begin with a financing framework review — confirming stress-test status with the buyer's mortgage broker, mapping FHSA and RRSP withdrawal capacity, and identifying the actual CMHC-eligible purchase ceiling before identifying target properties. This prevents the most common source of late-stage offer collapse in Maple Ridge and Mission.
For strata properties, we review Form B documents as a standard step in our offer preparation process, not as an afterthought. Reserve fund balance, special levy status, and depreciation report age are evaluated against CMHC lender tolerance before the offer is structured. We use microneighbourhood DOM data — not board-wide averages — to calibrate subject-condition timing and offer presentation. These are not premium services. They are the minimum standard a first-time buyer should expect.
First-Time Buyer Agent Interview Checklist
Ask every candidate agent these questions before signing a buyer representation agreement:
- Can you explain how FHSA contribution room interacts with an RRSP Home Buyers' Plan withdrawal on the same purchase — including the sequencing that maximizes net down-payment?
- Before we submit an offer, will you confirm stress-test approval directly with my mortgage broker — and can you explain what happens to my purchase price ceiling if the stress-test reduces my qualifying amount?
- For any strata property I'm considering, will you review the Form B and flag special levy risk and reserve fund status before we finalize the offer strategy?
- What is the current average days on market for the specific neighbourhood I'm targeting — and how does that affect how I should structure subject-condition timelines?
- How many first-time buyer transactions have you completed in Maple Ridge or Mission in the past 24 months — and were any of those CMHC-insured purchases?
- If a strata depreciation report shows reserve fund depletion within 18 months, how does that affect my financing and what would you recommend?
What We Commonly See
Based on first-time buyer transaction analysis across Maple Ridge, Mission, and Pitt Meadows from 2024 to 2026.
- Pre-approval without stress-test confirmation: What often happens is a buyer receives a pre-approval letter from a mortgage broker, then the agent treats that letter as full financing clearance. When the CMHC lender independently verifies qualifying amounts, the gap between pre-approval and actual purchase power surfaces — sometimes on the morning of subject removal.
- Form B reviewed after offer acceptance: A common mistake is treating the Form B review as a due-diligence step inside the subject period rather than a pre-offer filter. By the time a financing condition is in play, the buyer has emotional and time investment in the property. Agents who read Form B before offer submission protect buyers from that position entirely.
- DOM data pulled from board-wide summaries: In our experience, most agents use monthly board statistics that blend Maple Ridge East and West, detached and strata, into a single figure. Using that figure to decide how many days to allow for financing conditions or how quickly to act on a new listing routinely produces the wrong answer in both zones.
- FHSA treated as a paperwork item: Most agents can confirm that a buyer has an FHSA account. Very few ask about contribution room carry-forward, whether a Home Buyers' Plan withdrawal is being stacked, or how the total affects the closing funds statement. The difference between a well-coordinated FHSA strategy and a generic one can represent several thousand dollars in net purchasing capacity.
Questions First-Time Buyers Ask
Does it matter which brokerage my agent is with if I'm buying a townhome in Maple Ridge?
Brokerage affiliation doesn't determine an agent's ability to read Form B documents, coordinate FHSA withdrawals, or interpret microneighbourhood DOM data. Those are individual competencies. What matters is whether the specific agent has completed first-time buyer transactions in this market recently — not which office their license is held through.
Can I use both my FHSA and RRSP Home Buyers' Plan on the same purchase in BC?
Yes. Under current CRA rules, a qualifying first-time buyer can withdraw from both a First Home Savings Account and an RRSP through the Home Buyers' Plan for the same purchase. The interaction between the two programs — including contribution room timing and the tax deduction mechanics — should be reviewed with your mortgage broker and a tax professional before finalizing your down-payment plan.
What should I look for in a strata depreciation report if I'm buying a townhome in Maple Ridge?
The most important items are the reserve fund balance relative to projected repair costs, the age of the last depreciation report, and any outstanding or pending special levies disclosed in the Form B. A reserve fund with a projected depletion timeline of 12 to 18 months before the next scheduled major repair signals material special levy risk — which can directly affect your CMHC financing eligibility. Consult a strata lawyer or qualified inspector for advice specific to your purchase.
In Summary
For first-time buyers in Maple Ridge, Mission, and the outer Fraser Valley, the right agent is not the most decorated or most visible one. It is the agent who verifies CMHC stress-test qualification before any offer is written, understands how FHSA and RRSP withdrawals interact, reads Form B strata documents as a pre-offer filter rather than a post-acceptance formality, and uses neighbourhood-specific DOM data instead of blended regional averages. These competencies are testable before you sign anything — and testing for them is the single most valuable thing you can do before your search begins in earnest.
If you're preparing to buy your first home in Maple Ridge, Mission, or the surrounding Fraser Valley and want a conversation grounded in FHSA coordination, strata document review, and accurate local market data — Mansour Real Estate Group is available for a no-pressure consultation before you commit to any agent or any property.
Related Articles
- Build your mortgage qualification foundation before your agent search: Credit Score and Mortgage Readiness Roadmap for Fraser Valley First-Time Buyers
- Understand which Maple Ridge neighbourhoods offer genuine entry-level value: Maple Ridge and Pitt Meadows First-Time Buyer Neighbourhood and Market Entry Guide
- Return to this guide: First-Time Buyer Realtor Selection Guide for Maple Ridge, Mission, and the Outer Fraser Valley 2026
About Mansour Real Estate Group
First-time buyers navigating strata-heavy outer Fraser Valley markets — where Form B documents, FHSA coordination, and CMHC qualification thresholds determine whether a transaction closes cleanly — need a real estate team with direct, specific experience in those exact competencies. Mansour Real Estate Group has guided first-time buyers, families, and investors through entry-level strata and detached purchases across Maple Ridge, Mission, Abbotsford, and the broader Fraser Valley for more than 22 years.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has completed more than $780 million in residential real estate transactions across the Fraser Valley and Lower Mainland and is one of the highest ranked realtors in the region. The team is trusted for first-time buyer representation, strata transactions, estate sales, divorce-related property sales, downsizing, and complex real estate situations where accuracy and process matter most.
Whether someone is searching for Realtors experienced with first-time buyer transactions in Maple Ridge or Mission, a real estate agent who can coordinate FHSA and
Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or real estate advice. Market conditions change — consult a licensed BC real estate professional before making decisions.



