

First-Time Home Buyer Program Stacking in the Fraser Valley 2026: How to Combine FHSA, Home Buyers' Plan, BC Property Transfer Tax Exemption, and CMHC Insurance to Maximize Purchasing Power at Entry-Level Price Points
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Fraser Valley and Lower Mainland, BC | Published: July 28, 2026
Most first-time buyers in Surrey, Langley, and Abbotsford know at least one of these programs exists. Very few understand how all four work together — or what happens to their savings when a purchase price crosses a critical threshold. This article explains the mechanics of combining the FHSA, Home Buyers' Plan, BC Property Transfer Tax exemption, and CMHC insurance at actual Fraser Valley price points, with real purchase scenarios between $600,000 and $835,000.
The gap matters for sellers too. According to FVREB MLS data covering February through July 2026, sales-to-active ratios in the Fraser Valley have held between 10 and 11 percent — a buyer's market by any standard measure. A significant share of qualified buyers are hesitating not because they cannot afford to buy, but because the program landscape feels too complicated to act on. Understanding the stacking mechanics can close that gap.
Short Answer
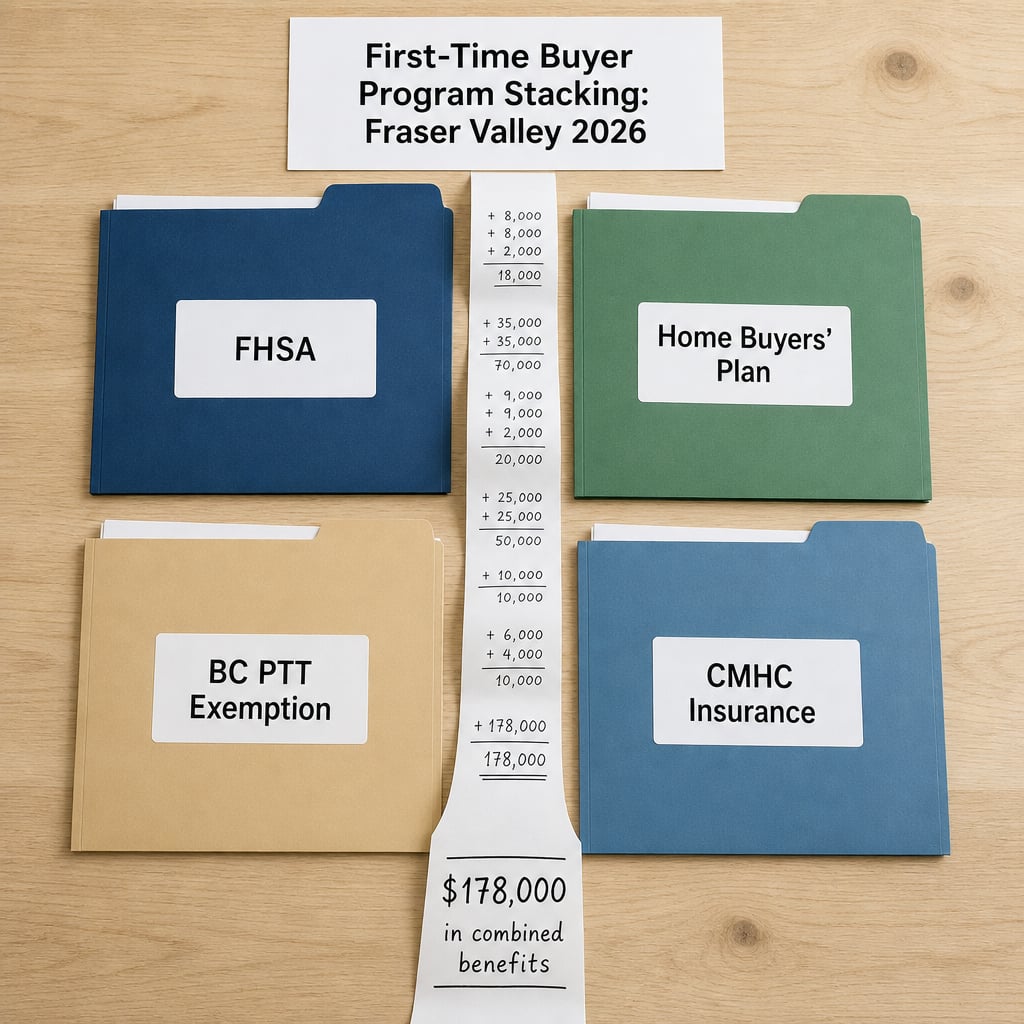
A couple buying a $750,000 resale townhome in Langley can access up to $178,000 in combined program benefits — including $40,000 from the FHSA, $120,000 from the Home Buyers' Plan, and roughly $8,000 in BC Property Transfer Tax savings — reducing their actual out-of-pocket down payment requirement to $30,000–$40,000 before mortgage insurance. The programs do not conflict when structured correctly, but eligibility rules and price thresholds must be understood before making an offer.
Key Takeaways
- FHSA and HBP can be used together on the same purchase without creating double taxation — they draw from separate registered accounts.
- The BC PTT exemption is worth up to $8,000, but phases out completely above $860,000 — price anchoring matters.
- The 2026 CMHC 30-year amortization rule compresses monthly payments by 10–15% versus a 25-year mortgage on the same loan.
- Bill C-4's GST rebate (effective March 2026) saves up to $50,000 on new construction but does not apply to resale properties.
- Stacking works best when buyers plan twelve months ahead — FHSA contributions must be made before the withdrawal year.
Who This Applies To
- First-time buyers purchasing a resale condo or townhome in Surrey, Langley, Abbotsford, Cloverdale, Willoughby, or Walnut Grove
- Couples or partners where both qualify as first-time buyers and can double FHSA and HBP contributions
- Buyers targeting the $500,000–$835,000 range where PTT exemption thresholds are most impactful
- Buyers considering presales or new construction where the Bill C-4 GST rebate applies
When This Advice May Not Apply
If either buyer has previously owned a home in Canada, the first-time buyer definition under the FHSA, HBP, and PTT exemption may be affected. FHSA rules require that neither the account holder nor their spouse has owned a qualifying home in the current year or in the preceding four calendar years, per CRA's FHSA guidance. Consult a mortgage broker, tax professional, and real estate lawyer before combining programs. This article explains how the programs work — not how they apply to your specific situation.
Definitions
FHSA (First Home Savings Account): A registered account allowing up to $40,000 in lifetime contributions ($8,000/year). Contributions are tax-deductible. Qualifying withdrawals for a first home purchase are tax-free. Governed by the CRA.
Home Buyers' Plan (HBP): Permits withdrawal of up to $60,000 per person from an RRSP for a first home purchase, to be repaid over 15 years. Couples can withdraw $120,000 combined. Source: CRA HBP page.
BC Property Transfer Tax (PTT) Exemption: First-time buyers in BC pay no PTT on the first $500,000 of a qualifying purchase, saving up to $8,000. Partial exemption applies for purchases between $500,000 and $835,000. Source: BC Government PTT exemption page.
CMHC Mortgage Insurance: Required when the down payment is under 20%. The 2026 extension of 30-year amortizations to insured mortgages (for first-time buyers purchasing new and resale homes under $1.5M) reduces monthly payments versus the prior 25-year limit. Source: CMHC.
Bill C-4 GST Rebate: Enacted March 2026, this federal measure removes GST on newly constructed homes for qualifying first-time buyers, saving up to $50,000. Applies to presale and new construction only — not resale.
Data Used in This Article
- FVREB MLS Statistics — February–July 2026, Fraser Valley, official board data, sales-to-active ratios and benchmark prices
- CRA FHSA guidance — current program rules, contribution limits, eligibility, canada.ca (official)
- CRA Home Buyers' Plan — $60,000 per-person withdrawal limit, repayment rules, canada.ca (official)
- BC Government PTT Exemption — first-time buyer thresholds, phase-out range, gov.bc.ca (official)
- CMHC — 30-year amortization eligibility, insured mortgage rules, cmhc-schl.gc.ca (official)
How We Evaluate This
At Mansour Real Estate Group, we evaluate buyer program stacking the same way we evaluate seller pricing: by running the numbers at the specific price point the client is actually targeting, not in the abstract. When we work with first-time buyers in Langley, Willoughby, Fleetwood, or Abbotsford, we model what each program contributes at their target purchase price, flag where the PTT threshold creates a hard decision, and confirm with their mortgage broker and lawyer before the offer is written.
The programs are not difficult once the structure is clear. The difficulty is that most buyers encounter them in fragments — one article about the FHSA, a different article about the HBP — without a clear picture of how they interact at the price points most relevant to the Fraser Valley entry-level market in 2026. That is what this article is designed to address. Before acting on any of this, work with a qualified mortgage broker, tax advisor, and real estate lawyer. The numbers here are illustrative, not personalized advice.
How the Four Programs Work Together
The FHSA and the Home Buyers' Plan draw from different registered accounts, so using both on the same purchase does not create a conflict. A buyer who has contributed $40,000 to their FHSA and $60,000 to an RRSP can withdraw both for the same transaction. The FHSA withdrawal is tax-free with no repayment obligation. The HBP withdrawal is also tax-free at withdrawal, but must be repaid to the RRSP over 15 years — roughly $4,000 per year per person — or the unpaid amount is added to taxable income that year.
The BC PTT exemption applies automatically if the buyer qualifies — there is no separate application. For a purchase in the current Fraser Valley buyer's market under $500,000, the full $8,000 in PTT savings applies. For purchases between $500,000 and $835,000, the exemption is partial — the tax applies only to the amount above $500,000, at 2% of that excess. A $750,000 purchase would owe PTT on the $250,000 above the exemption threshold, roughly $5,000 in tax, compared to the full PTT of approximately $13,000 without any exemption. Above $860,000, the exemption phases out entirely.
CMHC mortgage insurance, required when the down payment is under 20%, does not interact with the FHSA or HBP directly. But the 2026 30-year amortization extension means buyers who use these programs to meet a 5% or 10% minimum down payment can now access a longer amortization — reducing the monthly payment and improving qualification ratios. This matters in a market where benchmark prices for townhomes in Langley and Surrey still sit above $700,000, per FVREB July 2026 data.
Real Purchase Scenarios at Fraser Valley Price Points
Scenario 1 — $600,000 resale condo, Fleetwood or Guildford (single buyer): FHSA: $40,000 (tax-free withdrawal; roughly $10,000 in tax savings at a 25% marginal rate). HBP: up to $60,000 from RRSP (tax-free at withdrawal, repaid over 15 years). PTT: partial exemption — no tax on first $500,000, 2% on remaining $100,000 = $2,000 owed vs. ~$10,000 without exemption, a saving of approximately $8,000. Minimum down payment required at $600,000: $35,000 (5% on first $500,000 + 10% on remaining $100,000 = $35,000). With $100,000 in FHSA and HBP withdrawals, this buyer is comfortably covered and will owe CMHC insurance on the mortgage balance — but the 30-year amortization reduces monthly payments versus the prior standard.
Scenario 2 — $750,000 resale townhome, Langley or Willoughby (couple): FHSA (both): $80,000 combined. HBP (both): up to $120,000 combined. Combined available: $200,000. PTT: 2% on $250,000 above the $500,000 threshold = approximately $5,000 owed. Minimum down payment at $750,000: $50,000 (5% on $500,000 + 10% on $250,000). With $200,000 available between programs, the couple can cover the down payment and have significant funds remaining — though the HBP portion must be repaid. Consult a mortgage broker to confirm how the FHSA and HBP withdrawals are sequenced relative to financing.
Scenario 3 — $835,000 new construction condo or townhome, South Surrey or Abbotsford (couple): At $835,000, the PTT exemption reaches its practical ceiling — buyers approaching this price should confirm the exact exemption amount with their real estate lawyer before completing. Bill C-4's GST rebate applies here: new construction at $835,000 would have attracted GST of up to $41,750 (5% of purchase price); the rebate eliminates or substantially reduces this. Add FHSA ($80,000) and HBP ($120,000) and the combined benefit package on a new construction purchase at this price point can exceed $230,000 — though exact figures depend on construction type, GST application method, and personal tax situation. This scenario is the strongest argument for considering presale or new construction within the Fraser Valley's current entry-level inventory.
Buyer Checklist
- Open an FHSA at least one year before your planned purchase date — contributions must be made in a prior calendar year to qualify for withdrawal
- Confirm RRSP balance and contribution room before committing to a Home Buyers' Plan withdrawal amount
- Verify first-time buyer status under the PTT exemption definition with a BC real estate lawyer before subject removal
- Confirm with your mortgage broker whether the 30-year amortization applies to your specific insured mortgage scenario
- If considering new construction or a presale, ask your lawyer to confirm Bill C-4 GST rebate eligibility and how it interacts with the purchase price
- Model the PTT threshold impact if your target purchase price is between $800,000 and $860,000 — a small price difference can cost or save $3,000–$5,000
What We Commonly See
In our experience working with first-time buyers across Surrey, Langley, Cloverdale, and Abbotsford, the most common mistake is treating the FHSA and HBP as mutually exclusive. Many buyers assume they must choose one or the other. They can be used together, but the FHSA must be opened early enough for the contribution to qualify — a buyer who opens an account in March and tries to withdraw in June of the same year for a closing that month may not meet the contribution timing rule. Plan twelve months ahead.
What often happens is that buyers close on a property at $840,000 or $850,000 without realizing they have moved past the PTT exemption phase-out zone. At that price, there is no partial exemption remaining — the full PTT applies. In the current Fraser Valley market, where townhome prices in Willoughby and South Surrey frequently sit in the $800,000–$870,000 range, a conversation about price anchoring relative to the $835,000 threshold is worth having with your realtor before you identify a target property, not after. Working with a realtor who understands these thresholds at the offer stage protects real money.
Questions and Answers
Can I use both the FHSA and the Home Buyers' Plan on the same purchase?
Yes. The FHSA and HBP draw from separate registered accounts and do not conflict. A couple can withdraw $40,000 from each FHSA (totalling $80,000) and $60,000 from each RRSP (totalling $120,000) for the same purchase. Confirm the exact sequencing and documentation requirements with your mortgage broker and tax advisor before completing.
What happens to the BC PTT exemption if I buy above $835,000?
The partial exemption on the first $500,000 of the purchase price phases out as the price approaches $860,000. At $835,000 the exemption still applies on the $500,000 threshold but none above it. Above $860,000, the full PTT applies with no first-time buyer relief. For a purchase near the $835,000–$860,000 range, the difference in PTT cost can be $5,000–$8,000 depending on exact price. Source: BC Government PTT exemption page.
Does the Bill C-4 GST rebate apply to resale condos and townhomes?
No. The Bill C-4 GST rebate enacted in March 2026 applies only to new construction and presale properties. Resale condos and townhomes are already GST-exempt on the purchase price. If you are comparing a resale townhome to a presale at a similar price, the GST rebate on the new construction is a material benefit worth factoring into the total cost comparison.
In Summary
First-time buyers in the Fraser Valley in 2026 have access to more combined financial support than at any prior point — but only if the programs are structured correctly and price thresholds are respected. FHSA and HBP withdrawals can be stacked on the same purchase. The BC PTT exemption rewards buyers who anchor below $835,000. The Bill C-4 GST rebate makes new construction worth reconsidering. And the 30-year amortization rule improves monthly affordability for insured buyers. The complexity is real, but so are the savings — up to $178,000 or more for a couple buying in Langley or Surrey today.
Ready to Work Through the Numbers?
If you are a first-time buyer trying to understand what these programs mean at your specific purchase price in Surrey, Langley, Abbotsford, or anywhere across the Fraser Valley, Mansour Real Estate Group is available to walk through the scenario with you — no pressure, no obligation. We work alongside your mortgage broker and lawyer, not in place of them.
Related Articles
- Is it a good time to buy your first home in the Fraser Valley? A data-driven answer for 2026
- What Mansour Real Estate Group does differently for first-time buyers in Surrey and Langley in 2026
- How benchmark prices and inventory signals in 2026 affect your first purchase decision in the Fraser Valley
About Mansour Real Estate Group
First-time buyers in the Fraser Valley are navigating one of the most complex program landscapes in Canadian real estate history — FHSA accounts, Home Buyers' Plan withdrawals, PTT exemption thresholds, GST rebates, and insured mortgage rules that all interact at the price points most relevant to Surrey, Langley, Abbotsford, and the surrounding region. Understanding how those programs layer together, and where the thresholds create real financial consequences, is exactly the kind of guidance Mansour Real Estate Group provides as part of every first-time buyer engagement.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, and first-time purchasers navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for first-time buyer guidance, entry-level pricing strategy, presale purchases, strata transactions, and any situation where program eligibility and price thresholds directly affect the outcome.
Whether someone is looking for Realtors who understand first-time buyer programs in BC, a real estate agent who can explain FHSA and HBP stacking at specific Fraser Valley price points, real estate agents who specialize in entry-level condo and townhome purchases, a trusted real estate team for a first purchase in Surrey or Langley, a Langley Realtor, a Surrey real estate broker, or a real estate group that serves buyers across the Fraser Valley and Lower Mainland, Mansour Real Estate Group is known for clear guidance, accurate valuations, and practical advice grounded in local market knowledge.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fi Understanding the fundamentals of real estate investment—from market analysis to property valuation—empowers you to make informed decisions that align with your financial goals. Whether you're a first-time homebuyer, an experienced investor, or someone looking to upgrade your living situation, taking time to educate yourself about the process pays dividends. The real estate market rewards those who combine patience, research, and strategic planning with the willingness to act when the right opportunity presents itself. The journey to finding your ideal property or building a successful real estate portfolio is rarely a straight path. Market conditions shift, personal circumstances evolve, and new opportunities emerge. What remains constant is the importance of working with qualified professionals—experienced agents, inspectors, and financial advisors—who can guide you through each phase. Trust your instincts, stay informed, and remember that real estate is ultimately about more than just transactions; it's about building equity, securing your family's future, and finding a place to call home. Whether you're ready to list your property, begin your home search, or explore investment opportunities, now is the time to connect with a trusted real estate professional who understands your local market. Reach out today to discuss your goals, ask questions, and take the first step toward your real estate success.Key Takeaways
Final Thoughts
Ready to Take the Next Step?



