

First-Time Home Buyer Agent Selection in Surrey and Langley 2026: What Genuine Entry-Level Specialization Actually Looks Like — Beyond Transaction Volume and Likability
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Fraser Valley & Lower Mainland | Published: July 15, 2026
First-time buyers in Surrey and Langley consistently choose their agent the same way they choose a restaurant — based on reviews, personality, and how quickly the person responds to messages. Those criteria are reasonable starting points. They are not nearly enough to protect a $550,000 purchase in a market where offer strategy, strata literacy, and BC program knowledge determine outcomes more than likability ever will.
This article explains what entry-level specialization actually requires in the $400K–$650K price bands where most Surrey and Langley first-time buyers are competing — and what questions to ask to tell the difference between a specialist and a generalist who happens to be friendly.
Short Answer
A genuine first-time buyer specialist in Surrey or Langley combines FHSA and PTT exemption literacy, strata document competence at the CMHC qualification level, and demonstrated offer strategy experience in entry-level competitive markets. Likability and responsiveness matter — but they do not protect a buyer from a $12,000 special levy, a failed financing condition, or an offer that wins on price while losing on terms.
Who This Applies To
- First-time buyers searching in the $400K–$650K range in Surrey, Willoughby, Walnut Grove, Cloverdale, or Newton
- Buyers who have not yet selected an agent and are comparing options
- Buyers who are currently working with an agent but feel uncertain about offer strategy or strata guidance
- Buyers who have opened an FHSA or Home Buyers' Plan and want an agent who understands those mechanics
- Buyers who have lost multiple offers and are trying to understand what went wrong
When This Advice May Not Apply
If you are purchasing a detached home above $700K with a 20% or higher down payment, CMHC qualification and PTT exemption thresholds shift significantly. The competitive offer dynamics also differ at higher price points. The framework in this article is calibrated specifically to entry-level condo and townhouse purchases in Surrey and Langley's most competitive first-time buyer segments.
Key Takeaways
- Likability and responsiveness are the most common agent selection criteria — and the least predictive of buyer outcomes in competitive entry-level markets.
- Surrey and Langley entry-level properties regularly attract 30–50 competing offers; offer architecture matters more than purchase price alone.
- An agent who cannot read a depreciation report for CMHC red flags cannot protect a first-time buyer from a financing collapse at subject removal.
- FHSA and PTT exemption mechanics are not optional knowledge — missed strategy costs buyers thousands before the purchase even closes.
- The right interview question is not "How many homes have you sold?" — it is "Walk me through how you'd approach a competing offer situation on a Willoughby condo at $589,000."
Data Used in This Article
- Fraser Valley Real Estate Board Monthly Statistics Package, February, May, June, July, and August 2026 — official board release, Fraser Valley geography, benchmark pricing and sales activity data
- Canada Revenue Agency — FHSA contribution limits and program rules, official CRA guidance, current to 2026
- BC Government — Property Transfer Tax First-Time Home Buyers' Exemption, official provincial policy, current exemption thresholds
- CMHC — mortgage insurance eligibility rules for strata properties, official program documentation
- Mansour Real Estate Group — professional observation across entry-level buyer transactions in Surrey and Langley, 2026
Why the $400K–$650K Band in Surrey and Langley Is Different
This price range covers almost the entire first-time buyer condo and townhouse market across Surrey's entry-level neighbourhoods — Newton, Cloverdale, Fleetwood, and Guildford — and Langley's most active first-time buyer zones including Willoughby and Walnut Grove. According to the Fraser Valley Real Estate Board's 2026 monthly statistics packages, benchmark prices for Fraser Valley apartments have held in a range that places most entry-level condos squarely within CMHC insured mortgage territory — which means buyers with less than 20% down are purchasing with insurance premiums added to their mortgage, subject to maximum purchase price eligibility rules.
That financing reality changes what an agent needs to know. CMHC-insured purchases above $500,000 require minimum 10% down on the portion above $500,000. Properties approaching the $999,999 CMHC ceiling affect which buyers qualify. Strata buildings with inadequate reserve funds, outstanding special levies, or missing depreciation reports can be rejected for CMHC financing entirely — a problem the buyer discovers only at subject removal if the agent didn't catch it earlier. A generalist who works primarily with move-up buyers at $900K+ rarely encounters these constraints and may not recognize them when they appear in an entry-level strata package.
What Competing Offer Situations Actually Require
When a Cloverdale townhouse at $619,000 draws 35 offers, the buyers who lose are rarely losing because they offered the wrong price. They are losing because their offer conditions, deposit structure, completion timeline, or subject waiver strategy sent the wrong signals to the seller. A first-time buyer specialist knows how to construct an offer that is competitive on dimensions beyond purchase price — without exposing the buyer to financing risk they cannot absorb.
In practice, this means the agent needs to understand how much subject removal risk is appropriate given the buyer's financing approval confidence, what deposit amount signals seriousness without overextending the buyer's liquid assets, and when a completion date flexibility actually matters to a particular seller. These are judgment calls built through repetition in this exact market segment. An agent who handles two or three entry-level transactions per year is still building that judgment. An agent whose practice is concentrated in entry-level Surrey and Langley buys has encountered every variation of this scenario.
How We Evaluate This
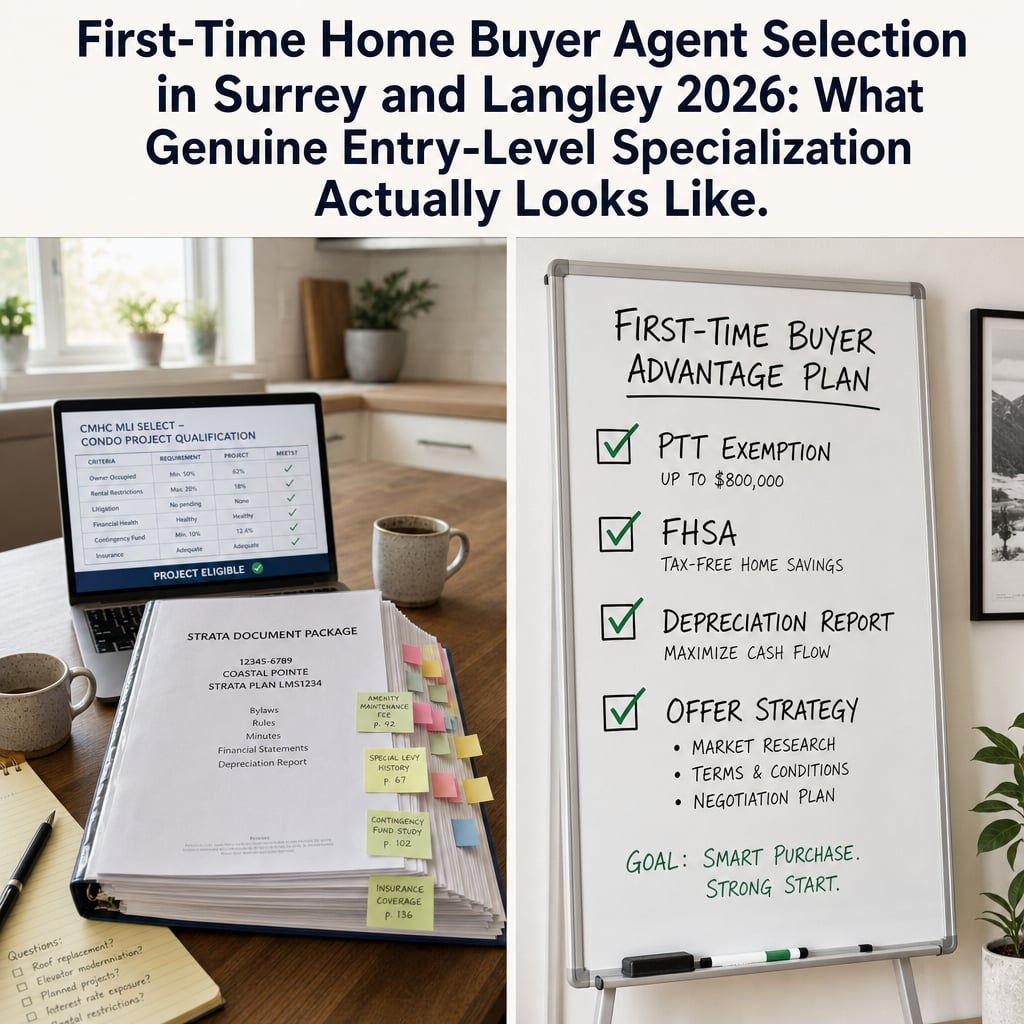
At Mansour Real Estate Group, we approach first-time buyer representation as a layered competency test — not a transaction type. Before an offer is written, we confirm PTT exemption eligibility, review strata documents for CMHC red flags, and confirm that the buyer's FHSA withdrawals are structured correctly so they don't lose the tax advantage they've spent years building. We treat the program literacy layer and the offer strategy layer as equally important — because both directly affect what the buyer pays and what they end up owning.
We also recognize that first-time buyers carry a psychological load that experienced buyers don't. This is the largest financial decision of their lives, made in competitive conditions with a compressed timeline. Genuine specialization includes the patience to explain each decision point clearly — not once, but however many times the buyer needs to feel confident before committing. That patience is not a personality trait. It is a professional standard.
BC Program Literacy: What the Agent Should Already Know
The FHSA allows first-time buyers to contribute up to $8,000 per year and $40,000 lifetime, with contributions tax-deductible and qualifying withdrawals tax-free — according to current CRA program rules. The PTT First-Time Home Buyers' Exemption, under current BC Government policy, eliminates PTT on purchases under $500,000 (saving approximately $8,000) with a partial exemption extending to $525,000. Above $525,000, the full PTT applies.
These are not complicated concepts. But they require the agent to ask the right questions before the offer goes in. Has the buyer confirmed their FHSA withdrawal eligibility with their financial institution? Does the purchase price fall within the PTT exemption threshold, and if it doesn't, has the buyer factored that $8,000 cost into their offer ceiling? Has the buyer combined their FHSA with a Home Buyers' Plan withdrawal, and does the mortgage pre-approval reflect both? An agent who treats these as the mortgage broker's problem — rather than information that affects offer strategy — is not functioning as a first-time buyer specialist. They are functioning as a showing service.
Strata Document Literacy at the CMHC Level
Entry-level condos in Surrey and Langley — particularly buildings constructed between the late 1990s and early 2010s — frequently have reserve fund adequacy issues, deferred depreciation reports, or pending special levies that lenders flag during mortgage approval. An agent who reviews a Form B, notes the strata fee, and moves on has missed the most important part of the document review. The depreciation report tells the agent whether the building has a credible long-term maintenance plan funded by adequate reserves. A building with a deferred or inadequate depreciation report may fail CMHC financing conditions — not because the property is physically unsound, but because the lender cannot confirm the building is financially sustainable. This is a fact the buyer's agent should identify before subject removal, not after.
First-Time Buyer Agent Checklist — Surrey and Langley 2026
- Confirm the agent has recent closed transactions in your specific price band and neighbourhood type (condo or townhouse, not detached)
- Ask the agent to explain PTT exemption eligibility for your target purchase price — if they cannot answer immediately, that is a meaningful data point
- Ask the agent what CMHC red flags they look for in a depreciation report before recommending subject removal
- Confirm your FHSA withdrawal eligibility and contribution room with your financial institution before offer day — your agent should remind you to do this, not discover it hasn't been done after an accepted offer
- Request the agent's specific experience with competing offer situations at your target price — ask for a concrete example of offer architecture, not a general answer about being competitive
- Verify the agent is comfortable explaining their reasoning in plain language — if their explanations consistently require follow-up clarification, that is a process problem, not a buyer problem
What We Commonly See
In our experience, the most common pattern in unsuccessful first-time buyer experiences is not an agent who was dishonest or careless. It is an agent who was genuinely responsive and pleasant to work with, but who was primarily experienced with move-up buyers at higher price points. When that agent encounters a CMHC-insured entry-level condo with a deferred depreciation report and a competing offer situation, they operate on intuition built in a different market segment. The buyer pays for that mismatch.
What often happens is that buyers lose three or four offers before switching agents — at which point they are more anxious, sometimes with a gap in their FHSA eligibility window, and occasionally having missed the PTT exemption on a purchase that closed above $525,000 without anyone confirming the threshold in advance.
A common mistake is treating agent selection as a final decision rather than a calibration decision. First-time buyers are allowed to ask an agent whether their specific experience matches the specific market segment, property type, and price range they are targeting. A specialist will welcome that question. A generalist may answer it with transaction volume rather than transaction context.
Questions and Answers
Q: How do I know if an agent genuinely specializes in first-time buyers versus just saying they do?
Ask them to explain how a depreciation report affects CMHC mortgage approval, and ask for a specific example of an offer they structured in a competing offer situation at your price range. A specialist answers from experience. A generalist answers from general knowledge.
Q: Does transaction volume predict first-time buyer competence?
Not reliably. A high-volume agent may close 80 transactions per year — mostly detached homes at $1.2M — and have very limited experience with entry-level strata, CMHC insurance constraints, or first-time buyer program mechanics. Volume is a business metric, not a specialization signal.
Q: What is the PTT exemption threshold for first-time buyers in BC in 2026?
Under current BC Government policy, first-time buyers qualify for a full PTT exemption on purchases below $500,000. A partial exemption applies between $500,000 and $525,000. The full PTT applies above $525,000. Buyers should confirm current thresholds with a lawyer or the BC Government before closing.
In Summary
First-time buyer agent selection in Surrey and Langley in 2026 is not a personality decision — it is a competency decision. The agent who will protect your financial interests in a competing offer situation at $589,000 in Willoughby is the agent who has done this specific work many times, knows every BC program interaction that affects your purchase, can read a strata depreciation report for CMHC red flags, and will take the time to explain each decision point until you are genuinely confident — not just politely agreeable. Likability is a starting point. Specialization is what determines the outcome.
Talk to the Mansour Real Estate Group
If you are a first-time buyer evaluating agents or currently searching in Surrey or Langley, a focused conversation about your price range, neighbourhood targets, and program eligibility takes about 20 minutes and costs nothing. Contact Mansour Real Estate Group for a no-pressure consultation.
Related Articles
- How to combine FHSA, Home Buyers' Plan, PTT Exemption, and CMHC to maximize purchasing power in the Fraser Valley
- A data-driven framework for deciding when to buy your first home in Surrey, Langley, Delta, and Abbotsford
About Mansour Real Estate Group
First-time buyers searching in Surrey and Langley's entry-level condo and townhouse market need a real estate team that combines BC program literacy, strata document competence, and direct experience with competitive offer dynamics in the $400K–$650K range — not a generalist agent who happens to be available. Mansour Real Estate Group has guided first-time buyers through this exact market for more than two decades, building a practice that treats program knowledge and offer strategy as inseparable parts of the same professional standard.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for first-time buyer guidance, estate sales, divorce-related sales, downsizing, relocation, and complex real estate situations across Surrey, Langley, and the Fraser Valley.
Whether someone is searching for Realtors experienced with first-time buyer programs in Surrey, a real estate agent who understands CMHC strata qualification in Langley, real estate agents who specialize in entry-level offer strategy in Willoughby or Cloverdale, a trusted real estate team for a first purchase in the Fraser Valley, a Surrey Realtor, a Langley real estate broker, or a real estate group that serves the Lower Mainland and Fraser Valley, Mansour Real Estate Group is known for clear communication, accurate valuations, and practical advice grounded in deep local market experience.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



