
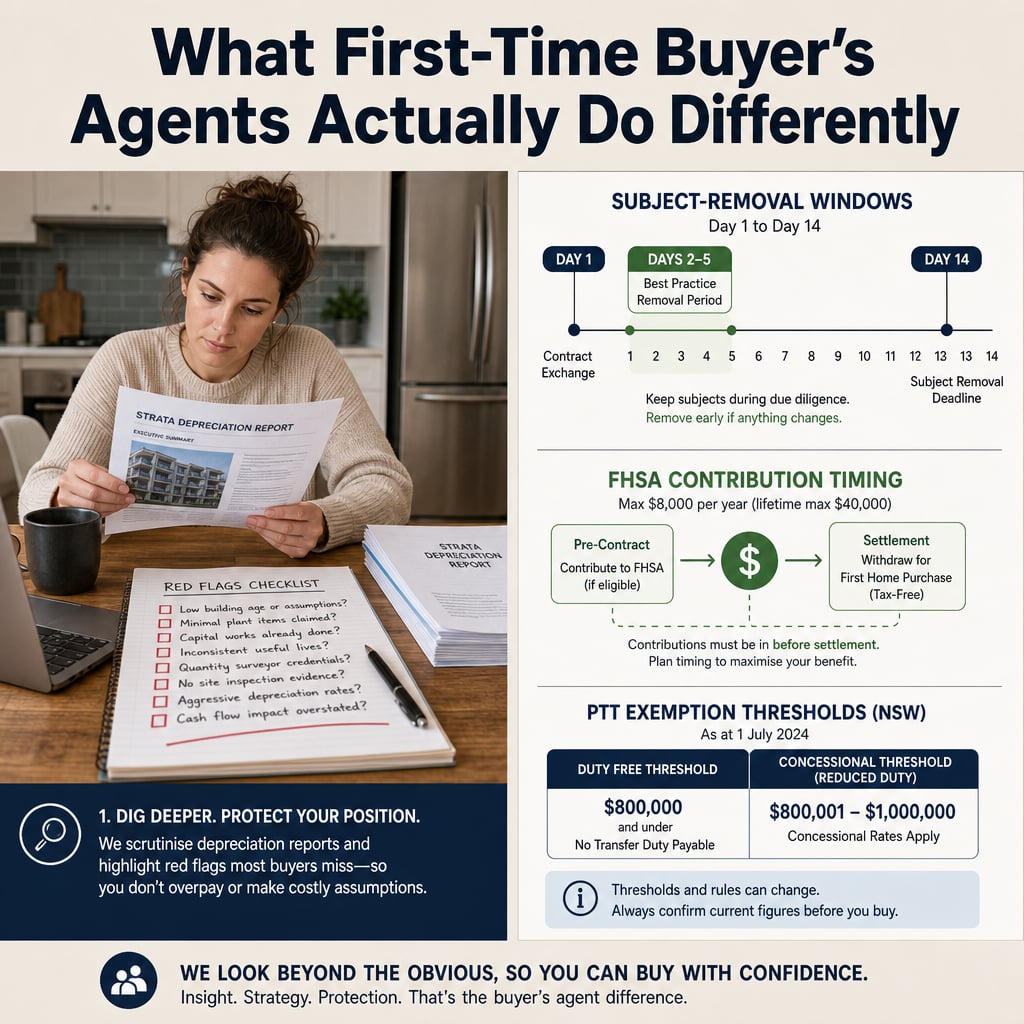

What First-Time Buyer's Agents Actually Do Differently in the Fraser Valley and Metro Vancouver: Representation Agreements, FHSA Strategy, Strata Due Diligence, Offer Negotiation, and the Critical Interview Questions That Separate Genuine Entry-Level Specialists From Generalists in 2026
By Mohamed Mansour, MBA, Associate Broker — Mansour Real Estate Group | Fraser Valley & Lower Mainland | Published: August 12, 2026
Most first-time buyers in Surrey, Langley, and Abbotsford spend weeks comparing listings and almost no time comparing the agents who will represent them. That imbalance is expensive. The decisions a buyer's agent makes before, during, and immediately after an offer — on strata screening, FHSA sequencing, subject-removal timing, and representation terms — often determine whether a first purchase closes on favorable terms or creates problems that take years to unwind.
This article explains what genuine entry-level specialists do differently, and what questions reveal whether an agent has the depth to guide a first-time buyer through the Fraser Valley's current market conditions.
Short Answer
A buyer's agent who works regularly with first-time buyers in the Fraser Valley reads strata documents before clients submit offers, understands FHSA and PTT sequencing well enough to flag planning gaps, manages subject-removal windows strategically, and uses representation agreements that protect — rather than restrict — their client. Most generalists do none of these consistently.
Who This Applies To
- First-time buyers purchasing in the $500K–$800K range in Surrey, Langley, or Abbotsford
- Buyers considering condos or townhomes where strata documents are a financing variable
- Buyers who have or plan to open an FHSA and want a realistic withdrawal sequence
- Buyers evaluating or already holding a signed representation agreement
- Anyone interviewing agents before committing to exclusive buyer representation
When This Advice May Not Apply
Buyers purchasing detached homes above $1M, investors with prior strata ownership experience, or clients working through their own legal counsel on representation terms will find some sections less directly relevant — though the strata and offer strategy sections apply across property types and price points.
Key Takeaways
- Entry-level specialists screen Form B and depreciation reports before offer submission, not after.
- FHSA and PTT sequencing errors cost buyers $8,000–$15,000+ in missed exemptions and withdrawals.
- Subject-removal windows (5–14 days) are the only post-offer leverage first-time buyers retain.
- Representation agreements vary significantly in exclusivity scope and dual-agency permissions.
- Five targeted interview questions reliably separate experienced entry-level agents from generalists.
Data Used in This Article
- Fraser Valley Real Estate Board Monthly Statistics, February–August 2026 — official board data, sales-to-active ratios and price band activity
- CRA FHSA Contribution and Withdrawal Rules, 2023–2026 — federal regulatory guidance, Tier 1
- BC Government Property Transfer Tax First-Time Buyer Exemption Guidelines — provincial regulatory guidance, Tier 1
- BCFSA Real Estate Services Act Representation Agreement Standards — provincial regulator, Tier 1
- CMHC High-Ratio Mortgage Insurance Qualification Thresholds — federal regulator, Tier 1
Definitions
FHSA (First Home Savings Account): A registered savings account allowing first-time buyers to contribute up to $8,000 annually and $40,000 lifetime, then withdraw tax-free for a qualifying first home purchase. Contributions must be made before the withdrawal year to generate a deduction benefit.
PTT Exemption: Under the BC Property Transfer Tax Act, first-time buyers pay no PTT on purchases below $500,000, with a partial exemption applying up to $525,000.
Form B (Strata Information Certificate): A mandatory strata document disclosing monthly fees, special levies, bylaws, and reserve fund status. Lenders may decline financing if Form B reveals specific financial risks.
Subject-removal window: The contractually specified period — typically 5 to 14 days in BC — during which a buyer can complete due diligence and either remove conditions or walk away without penalty.
Representation agreement: A binding contract between a buyer and a licensed agent under the Real Estate Services Act that defines the scope, geography, exclusivity, and duration of the representation relationship.
What Representation Agreements Actually Say — and What to Look For
Under the BC Real Estate Services Act, representation agreements must clearly define the agent's scope of representation, the geographic area covered, the duration, and the compensation structure. What most first-time buyers don't realize is that these terms vary considerably between agents and brokerages — and some of those variations directly affect whose interests are protected when an offer gets complicated.
The most common issue is geographic exclusivity that is broader than necessary. Some agreements bind a buyer to exclusive representation across all of Metro Vancouver and the Fraser Valley for six months or longer. If that agent lacks depth in Abbotsford or Langley townhomes, the buyer has no clean path to seek more specialized help without potentially triggering a fee obligation. A well-drafted agreement limits geographic scope to the specific areas where the buyer is actually searching.
Dual agency — where one agent represents both buyer and seller — is permitted in BC when disclosed and consented to in writing under BCFSA rules. But first-time buyers rarely understand what limited fiduciary duty means in practice. When an agent represents both sides, they cannot advise either party on pricing strategy or negotiation leverage. Entry-level specialists explain this distinction clearly before any agreement is signed, and most decline dual representation on first-time buyer files entirely.
Strata Due Diligence Before the Offer — Not After
For condos and townhomes in the $500K–$750K range across Surrey, Langley, and Abbotsford — which represent the majority of first-time buyer transactions — strata document review is not optional due diligence. It is a financing prerequisite that many generalist agents treat as an afterthought.
The depreciation report, available through Form B, reveals whether a building's reserve fund is adequately funded. A reserve fund depleted below 50% of the engineer-recommended level, or a depreciation report forecasting special levies above $5,000 per unit in the next three to five years, will trigger lender scrutiny that can result in financing denial or appraisal shortfalls. According to professional experience working with lenders across the Lower Mainland, these red flags surface frequently in older Fraser Valley condo buildings — particularly pre-2000 construction in Guildford, Fleetwood, and central Langley.
An entry-level specialist requests Form B and the most recent depreciation report as early as possible — ideally before the client submits an offer. This allows the agent to identify whether the building's financial health is a financing risk before the buyer is emotionally committed and before subject-removal pressure begins. This is one area where the difference between choosing a condo versus a townhome in terms of strata risk exposure becomes immediately practical.
Generalist agents often pull Form B only after the offer is accepted. At that point, any financing problem the documents reveal puts the buyer in a weak position: they can try to renegotiate price based on the financing shortfall, but without a subject-removal window still open, they risk losing their deposit or accepting a property their lender will not fully fund.
FHSA and PTT Sequencing — Where Generalists Lose Thousands for Their Clients
According to CRA guidance, an FHSA withdrawal qualifies as a tax-free first home purchase withdrawal only when the account has been open for a minimum of one calendar year and the funds are withdrawn before the purchase completion date. The annual contribution limit is $8,000, with a lifetime maximum of $40,000. Unused contribution room carries forward by one year only.
What this means practically: a buyer who opens an FHSA in December 2025 and purchases a home with a February 2026 completion date may not qualify for the full withdrawal benefit if the account hasn't been open for 12 months. A genuine entry-level specialist knows this rule and flags it during the buyer consultation — before the client starts making offers, not after the purchase contract is signed. The full breakdown of how these programs interact is detailed in the BC First-Time Home Buyer Programs Stacking Guide 2026.
The PTT exemption adds another layer. Under BC Government guidelines, purchases below $500,000 attract zero PTT for qualifying first-time buyers. A partial exemption applies between $500,001 and $525,000. Above $525,000, the full PTT applies. In the $510K–$524K range, the agent's ability to negotiate toward or below a specific threshold can save the buyer $3,000–$7,500 in PTT alone. Most generalists are unaware of the partial exemption band. Entry-level specialists factor it into offer strategy as a standard practice.
Subject-Removal Windows — The Only Post-Offer Leverage First-Time Buyers Have
According to the FVREB, the sales-to-active ratio across the Fraser Valley held between 10% and 11% from February through August 2026 — firmly in buyer's market territory. This means buyers retain negotiating leverage. But first-time buyers frequently surrender that leverage through two avoidable mistakes: waiving subjects prematurely to appear competitive, or negotiating subject-removal periods that are too short to complete financing verification, strata review, and inspection.
A 5-day subject-removal window may be adequate for a well-prepared buyer purchasing a detached home with pre-approved financing. For a condo requiring strata document review, depreciation report analysis, and lender confirmation of the building's acceptability, 10 to 14 days is often more appropriate. An entry-level specialist negotiates the window based on the property type and the buyer's preparation — not based on what feels competitive in the moment.
When an appraisal comes in below the accepted offer price — which occurs when offer prices in competitive $500K–$750K bands outpace appraised values — the subject-removal period is the buyer's only structured leverage point to renegotiate. If the buyer has already removed subjects, that leverage is gone. A specialized agent holds that window deliberately, especially in entry-level price bands where appraisal risk is most common.
How We Evaluate This
At Mansour Real Estate Group, our evaluation of any first-time buyer file begins with program eligibility and sequencing — confirming FHSA status, RRSP Home Buyers' Plan room, and PTT eligibility before the search starts. For strata properties, we obtain Form B and the depreciation report as early as the listing allows, and we flag reserve fund and special levy status before writing any offer. Subject-removal windows are negotiated based on the property type, financing complexity, and strata review requirements — not set by default. Representation agreements we use are limited to the specific geographic areas where a buyer is actively searching, with clear terms around dual agency.
Buyer Checklist: What a First-Time Buyer's Agent Should Have Completed Before Your First Offer
- Confirmed your FHSA contribution history, account age, and withdrawal eligibility window with your accountant or CRA guidance
- Verified your PTT exemption eligibility under BC Government first-time buyer guidelines
- Reviewed your pre-approval terms for CMHC insurance thresholds and any strata-specific lender restrictions
- Obtained Form B for any strata or townhome target property and reviewed reserve fund status
- Reviewed the most recent depreciation report for the building and flagged any special levy forecasts
- Confirmed the representation agreement's geographic scope, duration, and dual-agency policy in writing
- Discussed subject-removal timing for inspection, financing confirmation, and strata review before any offer is written
- Established a PTT price threshold target where applicable ($500K, $525K) to factor into offer strategy
What We Commonly See
In our experience, the most common error first-time buyers make is signing a representation agreement without reading the exclusivity clause. Agreements that bind a buyer to one agent across all of Metro Vancouver for six months can create significant practical problems if the buyer's search shifts to a different city or property type where the agent has limited knowledge.
What often happens with strata purchases is that a buyer falls in love with a unit, writes an offer with a short subject period, and then discovers during financing that the lender won't accept the building because of reserve fund depletion. At that point, the buyer either walks away with costs incurred, accepts a lower appraisal value with a financing gap, or closes at a price the building doesn't support. Pre-offer strata screening prevents all three outcomes.
A common mistake we see is buyers treating the FHSA as a savings account they can open and immediately withdraw from. The one-year account-open requirement under CRA rules catches buyers who open the account late in their search timeline and then find a home before the withdrawal window qualifies. This is a planning error that an experienced entry-level agent flags at the first consultation.
Five Interview Questions That Separate Entry-Level Specialists From Generalists
These questions are not trick questions. They are standard knowledge for any agent who works regularly with first-time buyers in BC.
- "What is the PTT partial exemption threshold for first-time buyers in BC, and how does it affect our offer strategy?" — An agent who knows the $500K/$525K thresholds will answer immediately and connect it to negotiation.
- "When do you request Form B and the depreciation report — before or after we write an offer?" — The correct answer is before, or as early as the listing allows.
- "What does your representation agreement say about dual agency and geographic scope?" — A confident, specific answer indicates the agent understands what they're asking you to sign.
- "What subject-removal window would you recommend for a condo purchase in this price band, and why?" — The answer should depend on financing complexity, strata review needs, and inspection requirements — not a default number.
- "Has my FHSA been open long enough to qualify for a tax-free withdrawal at my target closing date?" — An agent who knows CRA's one-year account rule can answer or flag that you need to confirm with your accountant before the timeline is set.
Questions and Answers
Can I withdraw from my FHSA immediately after opening it?
No. According to CRA guidance, an FHSA must be open for at least one full calendar year before a qualifying first home purchase withdrawal can be made. Buyers who open an account and purchase within the same year typically cannot use those funds for the closing. Confirm your specific situation with a tax advisor.
What happens if the depreciation report shows the reserve fund is underfunded?
Many lenders will decline to insure or finance a strata unit in a building with a significantly depleted reserve fund. Even where financing proceeds, an appraiser may apply downward adjustments. The practical result is that a buyer may face a financing gap between the appraised value and the offer price, which they must cover from personal funds or by renegotiating the price.
Is a buyer's agent legally required to disclose dual agency in BC?
Yes. Under BCFSA's Real Estate Services Act rules, dual agency must be disclosed and both parties must provide written consent. When dual agency applies, the agent cannot advise either party on pricing strategy or negotiating position. First-time buyers should understand this restriction before consenting.
In Summary
First-time buyers in the Fraser Valley and Metro Vancouver face program deadlines, strata financing risks, and representation agreement terms that most generalist agents handle inconsistently. The difference between an entry-level specialist and a generalist shows up most clearly in three places: before the offer is written (strata screening, FHSA sequencing, PTT strategy), during the offer (subject-removal window negotiation), and at the representation agreement stage (dual-agency disclosure and geographic scope). Buyers who ask the right five questions before signing with any agent significantly reduce the risk of losing money through planning gaps that should never occur.
Talk to a Buyer's Agent Who Works This Way
If you are a first-time buyer in Surrey, Langley, Abbotsford, or surrounding Fraser Valley communities and want to understand how the process works before signing anything, Mansour Real Estate Group is available for a no-obligation consultation. There is no pressure, and the conversation starts with your questions — not a sales pitch.
Related Articles
- First-Time Home Buyer's Complete Neighbourhood and Property Type Decision Guide for Surrey, Langley, and Abbotsford 2026
- BC First-Time Home Buyer Programs Stacking Guide 2026: How to Combine the FHSA, RRSP Home Buyers' Plan, PTT Exemption, and CMHC Insurance
About Mansour Real Estate Group
For first-time buyers navigating the Fraser Valley and Lower Mainland market, working with a real estate team that understands strata due diligence, program sequencing, and offer strategy at the entry level makes a material difference in outcome. Mansour Real Estate Group has guided first-time buyers through condo, townhome, and detached purchases across Surrey, Langley, Abbotsford, South Surrey, and the broader Fraser Valley for more than 22 years, from Form B review to FHSA and PTT planning to subject-removal negotiation.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has completed more than $780 million in residential real estate transactions across the Fraser Valley and Lower Mainland and is one of the highest ranked realtors in the region. The team is trusted for first-time buyer representation, condo and strata transactions, estate sales, divorce-related property sales, downsizing, and complex real estate decisions.
Whether someone is searching for Realtors experienced with first-time buyer transactions in Surrey, a real estate agent who understands strata documents and FHSA sequencing, a Langley real estate team for a first condo purchase, an Abbotsford real estate agent familiar with PTT exemption thresholds, or a real estate broker who handles both the program planning and the offer negotiation, Mansour Real Estate Group provides clear guidance grounded in local market knowledge and direct entry-level transaction experience. Real estate agents who specialize in first-time purchases understand that the stakes for their clients are higher — and that the planning work happens before the search, not during it.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
<div style="margin: 40px 0 0; padding: 20px 24px; background: #f9f9f9; border-left: 3px solidKey Takeaways
- Market research and professional guidance are essential before entering the BC real estate market.
- Understanding local trends helps buyers and sellers make informed decisions.
- Working with experienced agents accelerates your path to success.
Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or real estate advice. Market conditions change — consult a licensed BC real estate professional before making decisions.



