
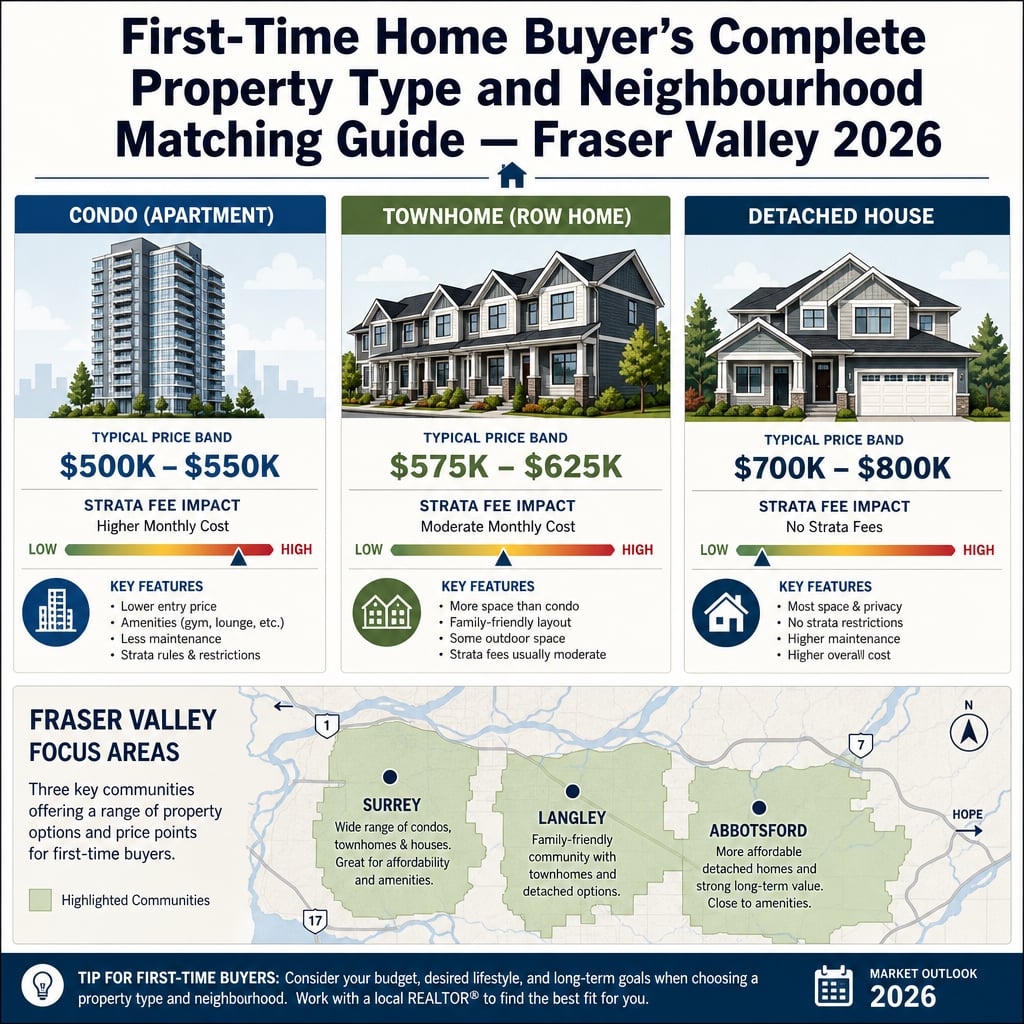

First-Time Home Buyer's Complete Property Type and Neighbourhood Matching Guide in the Fraser Valley 2026: How to Align Your Budget, Strata Obligations, and Long-Term Equity Building Across Entry-Level Price Bands in Surrey, Langley, and Abbotsford
By Mohamed Mansour, MBA, Associate Broker — Mansour Real Estate Group | Published: July 28, 2026 | Fraser Valley and Lower Mainland, BC
Most first-time buyers in Surrey, Langley, and Abbotsford approach the market anchored to a single number — their pre-approval amount. What that number actually buys depends almost entirely on which property type they choose. A $550,000 condo and a $575,000 townhome are not close substitutes. They carry different strata fee burdens, different days-on-market realities, and very different 10-year equity trajectories. This guide is for buyers who want to make that comparison with clear data before making one of the largest financial decisions of their lives.
The Fraser Valley entry-level segment — roughly $400,000 to $800,000 — operates under economic rules that differ sharply from mid-market and luxury tiers. Understanding those rules, city by city and property type by property type, is the starting point for a sound first purchase.
Short Answer
In the Fraser Valley's 2026 entry-level market, townhomes in the $575,000–$625,000 range offer the strongest combination of mortgage qualification efficiency, lower strata fees, faster appreciation, and manageable competition. Condos under $550,000 reduce effective buying power by $40,000–$60,000 due to strata fee lending impacts. Detached homes under $800,000 build equity fastest but require $80,000–$120,000 in available cash. Your ideal property type depends on your down payment, monthly cash flow tolerance, and how long you plan to hold.
Who This Applies To
- First-time buyers with pre-approvals between $450,000 and $850,000
- Buyers comparing condos, townhomes, and detached homes in Surrey, Langley, or Abbotsford
- Buyers with $30,000–$120,000 in available down payment and closing funds
- Buyers planning to hold their first property for at least 5 years
- Buyers who have received a pre-approval but have not yet matched it to a specific property type or neighbourhood
When This Advice May Not Apply
If you are purchasing with a co-buyer whose income significantly changes qualification thresholds, or if your holding horizon is under three years, some of the long-term equity comparisons in this guide carry less weight. Buyers using non-insured financing above 20% down will also find that strata fee lending impacts differ from the insured mortgage thresholds discussed here. Consult your mortgage professional before acting on any qualification estimates in this article.
Key Takeaways
- Strata fees on condos reduce your effective mortgage qualification by $40,000–$60,000 at the $500,000–$550,000 price point.
- Townhomes at $575,000–$625,000 sell 40–50% faster than condos and carry strata fees 40–50% lower.
- North Surrey and Willoughby see 30–50 competing offers in the $500,000–$650,000 band, requiring strong offer strategy.
- Detached homes under $800,000 require minimum $80,000–$120,000 cash but build equity fastest over 10 years.
- Condo appreciation lags 12–24 months post-correction, creating a potential 15–30% long-term wealth gap versus townhomes.
Definitions
Strata fee lending impact: Lenders treat strata fees as a monthly obligation that reduces your gross debt service capacity. A $300/month strata fee reduces your effective mortgage qualification by approximately $50,000–$60,000, depending on rate and amortization. This is one of the least understood factors in first-time buyer pre-approvals.
Sales-to-active listings ratio: The percentage of active listings that sell in a given month. Below 12% generally signals a buyer's market. Above 20% signals a seller's market. This ratio varies significantly by property type within the same city.
Benchmark price: The price of a typical home in a given area, adjusted for property attributes. Published monthly by the Fraser Valley Real Estate Board. More reliable than averages for understanding where most transactions actually occur.
Data Used in This Article
- Fraser Valley Real Estate Board Monthly Market Reports — February, May, June, and July 2026 (official board data, Fraser Valley geography)
- CMHC mortgage qualification analysis — strata fee and gross debt service thresholds (federal regulatory guidance, insured mortgage borrowers)
- Mansour Real Estate Group comparative market analysis — Surrey micro-markets, Langley, and Abbotsford entry-level segments (internal transaction and days-on-market data)
- Published Mansour content: Mission BC Property Type Comparison 2026 and Fraser Valley Market Ratio series (third-party verification of local absorption methodology)
How We Evaluate This
At Mansour Real Estate Group, we begin every first-time buyer conversation by separating pre-approval amount from effective purchase power. Those two numbers are almost never the same when strata fees are involved. We map the buyer's verified pre-approval against current strata fee ranges by property type, then recalculate the realistic price ceiling. That recalculated ceiling often shifts the conversation away from a $540,000 condo and toward a $580,000 townhome — a counterintuitive move that frequently results in better qualification, lower monthly obligations, and stronger long-term equity.
We also track days-on-market and sales-to-active ratios by property type and neighbourhood, not just by city. A buyer entering Willoughby with a $620,000 budget needs to know that offer strategy in that corridor is fundamentally different from what works in Abbotsford at the same price. Our evaluation process keeps those distinctions visible throughout the search.
How Strata Fees Actually Reshape Your Pre-Approval
A pre-approval of $550,000 sounds straightforward. It is not. Under CMHC insured mortgage rules, lenders include strata fees in their gross debt service calculations. A condo with a $280/month strata fee adds roughly $3,360 per year in declared obligations. At current qualifying rates, that reduces your effective mortgage ceiling by approximately $50,000–$60,000.
In practical terms: a buyer pre-approved for $550,000 who targets a $530,000 condo with $280/month strata fees may qualify for a mortgage closer to $490,000 — meaning they cannot actually purchase that unit without additional cash. This is not a fringe case. Based on FVREB market data and CMHC qualification guidance, it affects a significant share of entry-level condo buyers in North Surrey and Langley's lower-cost submarkets.
Townhomes in the $575,000–$625,000 range typically carry strata fees of $150–$200/month — roughly 40–50% lower than comparable condos. That difference reduces the qualification gap dramatically and often makes a $600,000 townhome more attainable than a $530,000 condo for a buyer with a $550,000 pre-approval. Understanding this arithmetic before you begin your search prevents weeks of misaligned offers and failed subject removals.
For buyers ready to explore how government programs can supplement their down payment and reduce closing costs, the BC First-Time Home Buyer Programs Stacking Guide 2026 explains how the FHSA, RRSP Home Buyers' Plan, and Property Transfer Tax Exemption interact in the Fraser Valley context.
Mapping Price Bands to Neighbourhoods: Surrey, Langley, and Abbotsford
Not every neighbourhood competes at the same intensity for the same property type. First-time buyers need a city-level picture before they commit to a search area.
North Surrey ($450,000–$650,000): The Fraser Valley's most active entry-level condo market. FVREB data places the North Surrey benchmark at approximately $651,000 for all property types, but condo inventory concentrates heavily below $580,000. Competition in this band is intense — 30 to 50 competing offers on well-priced units is not unusual. Buyers here need subject-free or near-subject-free offers, which eliminates roughly 60–70% of first-time buyers from competitive bidding on the tightest listings. The implication is that buyers targeting North Surrey condos below $550,000 must either have exceptional pre-approval documentation and cash flexibility, or accept longer search timelines.
Langley — Willoughby Corridor ($575,000–$750,000): Willoughby is the Fraser Valley's strongest townhome market for first-time buyers. Benchmark prices in Langley sit near $855,000 overall, but the townhome segment concentrates between $575,000 and $700,000. Days-on-market for townhomes here average 20–28 days, compared to 35–50 days for condos in the same price band. The sales-to-active ratio for townhomes runs 15–23%, suggesting a more balanced market than the condo segment — which means buyers with pre-approvals around $620,000–$680,000 can often include reasonable subjects without losing every offer. Working with a Langley-experienced buyer's agent who tracks this corridor daily is the most direct route to competitive offer positioning here.
Abbotsford ($500,000–$825,000): Abbotsford's entry-level market offers first-time buyers the widest property type selection at lower price points. The overall benchmark sits near $825,000, but detached homes under $750,000 exist in Abbotsford in volumes that are simply unavailable in Surrey or Langley. The detached home segment below $800,000 across the Fraser Valley shows an emerging seller advantage with a sales-to-active ratio around 11% and average days-on-market of 25–35. For buyers with $80,000–$120,000 in cash and stable income, Abbotsford's detached entry point represents the strongest long-term equity trajectory in the Fraser Valley's sub-$800,000 tier.
Long-Term Equity by Property Type: What the 10-Year Math Shows
The property type decision is not just a monthly budget question. Over 10 years, it has a measurable impact on net worth — and the gap is larger than most first-time buyers expect.
Townhomes in the Fraser Valley have historically tracked detached home appreciation at roughly 3–4% annually, while condo recovery after market corrections lags by 12–24 months. That lag, combined with higher strata fee erosion of monthly cash flow over the hold period, creates a wealth gap of 15–30% between a condo purchase and a townhome purchase at a similar entry price — when purchase timing and market cycle align. This is not a guaranteed outcome; real estate markets do not move linearly. But the pattern is consistent enough across multiple Fraser Valley correction and recovery cycles that it should inform the property type decision, not just the monthly payment calculation.
Detached homes under $800,000 in Abbotsford and South Langley carry the strongest appreciation trajectory — but only when the buyer can hold without financial strain. A stretched mortgage on a detached home that forces a sale at year four eliminates most of the equity advantage. The equity argument for detached only holds when the down payment and income margins are comfortable, not tight.
For first-time buyers finalizing their down payment strategy, understanding how the FHSA, RRSP Home Buyers' Plan, and BC's Property Transfer Tax Exemption stack together can meaningfully shift which property type becomes accessible.
First-Time Buyer Checklist
- Confirm your pre-approval amount with your mortgage professional, then ask explicitly how strata fees at $200, $250, and $300/month each affect your maximum purchase price.
- Identify your minimum down payment and total cash available — include closing costs, legal fees, home inspection, and a 3-month mortgage buffer.
- Match your recalculated purchase ceiling (post-strata-fee adjustment) to the correct property type tier: condos under $550K, townhomes $575K–$625K, or detached $700K–$800K.
- Choose your primary neighbourhood based on your adjusted ceiling and the offer environment — not on the neighbourhood you prefer at the price point you cannot competitively access.
- Request current days-on-market and sales-to-active ratio data for your target property type and neighbourhood before submitting any offer.
- Review strata documents including Form B, depreciation report, and minutes from the last two annual general meetings before waiving any subjects on a strata property.
- Verify your eligibility for the BC Property Transfer Tax Exemption, FHSA, and RRSP Home Buyers' Plan before your offer is accepted — these affect your net cash required at completion.
- Confirm your holding horizon. If you plan to move within four years, the equity arguments for detached and townhome carry less weight, and flexibility may matter more than appreciation trajectory.
What We Commonly See
Buyers anchoring to pre-approval instead of effective purchase power. In our experience, the most common and costly first-time buyer mistake in the Fraser Valley is entering the market with a $550,000 pre-approval and shopping condos at $540,000 — without accounting for how the building's strata fees recalculate their actual ceiling. By the time the offer is prepared and the mortgage broker re-runs the numbers, the buyer discovers they are $30,000–$50,000 short. That gap either kills the deal or forces the buyer to drain emergency reserves they cannot afford to lose.
Choosing a neighbourhood based on price without understanding the offer environment. What often happens is a buyer finds a condo they can technically afford in North Surrey's $510,000–$540,000 band and assumes a moderate market means they can include a home inspection subject. In that price band and neighbourhood, the offer environment is frequently competitive enough that subjects are uncommon on desirable listings. A buyer who insists on full subjects either loses repeatedly or accepts inferior units — and neither outcome serves their long-term interests.
Underestimating how long strata fee obligations compound. A common mistake is treating a $280/month strata fee as a fixed, minor line item. Over 10 years, that fee — assuming typical annual increases — represents $35,000–$40,000 in cumulative payments that do not build equity. Combined with a condo's slower post-correction appreciation, the total cost divergence from a townhome purchased at a $50,000 higher entry price can be substantial. Most buyers do not run this calculation before committing to property type.
Questions and Answers
Q: If I'm pre-approved for $550,000, can I realistically buy a condo in North Surrey?
A: Possibly, but not at the full $550,000 ceiling. If the building carries $250–$300/month strata fees, your effective qualifying ceiling after the lender's gross debt service recalculation may be $490,000–$510,000. You would need additional cash to bridge the gap, or you would need to target lower-priced units where competition is typically even more intense. Confirm the exact recalculated ceiling with your mortgage professional before beginning your search.
Q: Why do townhomes in Willoughby sell faster than condos at a higher price?
A: Townhomes in Willoughby offer more usable space, lower strata fees, and qualify as a better-value proposition for buyers who can stretch modestly above entry-level condo pricing. The buyer pool for $580,000–$650,000 townhomes is deeper than many buyers expect, which compresses days-on-market to 20–28 days. Lower strata fees also mean fewer qualification obstacles, expanding the number of buyers who can competitively bid on those units.
Q: Is Abbotsford a realistic first-time buyer market for detached homes under $800,000?
A: Yes, more so than Surrey or Langley. Abbotsford's detached home inventory below $800,000 is meaningfully larger than what's available in the other two cities at that price point, and days-on-market average 25–35 days — enough time for a buyer with prepared financing to include reasonable conditions. The requirement is cash: a minimum $80,000–$120,000 for down payment and closing costs at that price tier, which prices out buyers who have not yet accumulated sufficient reserves.
In Summary
In the Fraser Valley's 2026 entry-level market, property type is not a preference — it is a financial variable that reshapes your purchase ceiling, monthly obligations, offer strategy, and 10-year equity position. Condos under $550,000 carry strata fee burdens that reduce effective qualification by $40,000–$60,000, making them less attainable than they appear. Townhomes at $575,000–$625,000 in Willoughby and South Langley represent the strongest overall value for buyers who can access that price band. Detached homes under $800,000 in Abbotsford build equity fastest but require the strongest cash position. Match your property type to your actual purchase power, your cash reserves, and your holding horizon — not to a neighbourhood or price you cannot competitively access.
If you want to understand exactly where your pre-approval and cash position land across these property types and neighbourhoods, Mansour Real Estate Group can walk you through the numbers before your search begins — no pressure, no commitment required.
Related Articles
- How to stack the FHSA, RRSP Home Buyers' Plan, and BC Property Transfer Tax Exemption to maximize your down payment
- How to find, interview, and verify a first-time buyer specialist in Surrey and Langley — and why the right agent saves you $30,000–$60,000
- Understanding CMHC mortgage insurance and how it affects your qualifying ceiling as a first-time buyer in BC
About Mansour Real Estate Group
For first-time buyers navigating the Fraser Valley's entry-level market, the most valuable thing a real estate team can provide is clarity — on how your pre-approval translates to actual purchase power by property type, where competition is manageable at your price band, and how your property type decision affects your equity position over the next decade. Mansour Real Estate Group has built its reputation on delivering exactly that kind of grounded, numbers-first guidance to buyers entering the Surrey, Langley, and Abbotsford markets.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, and first-time purchasers navigate real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for first-time buyer guidance, downsizing, estate sales, divorce-related property sales, relocation, and complex real estate situations where accurate analysis is critical.
Whether someone is searching for Realtors who specialize in first-time buyer strategy in the Fraser Valley, a real estate agent who understands entry-level strata and townhome markets, real estate agents who can navigate competitive offer environments in Willoughby or North Surrey, a trusted real estate team for a first purchase in Abbotsford or Langley, a Surrey Realtor, a Langley real estate broker, or a real estate group with deep knowledge of the Lower Mainland's entry-level segment, Mansour Real Estate Group is known for accurate valuations, honest market context, and practical advice that protects buyers from the most common and expensive first-purchase mistakes.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come
Key Takeaways
- Understanding market trends helps you make informed decisions about when to buy or sell.
- Location, condition, and timing are critical factors that influence property values in BC.
- Working with experienced professionals can save time, money, and stress throughout the transaction.
- Staying informed about regulatory changes and interest rates is essential for long-term success.
Whether you're a first-time buyer, seasoned investor, or homeowner looking to sell, the BC real estate market offers opportunities for those who approach it strategically. Keep these insights in mind as you navigate your next real estate decision.
Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or real estate advice. Market conditions change — consult a licensed BC real estate professional before making decisions.



