
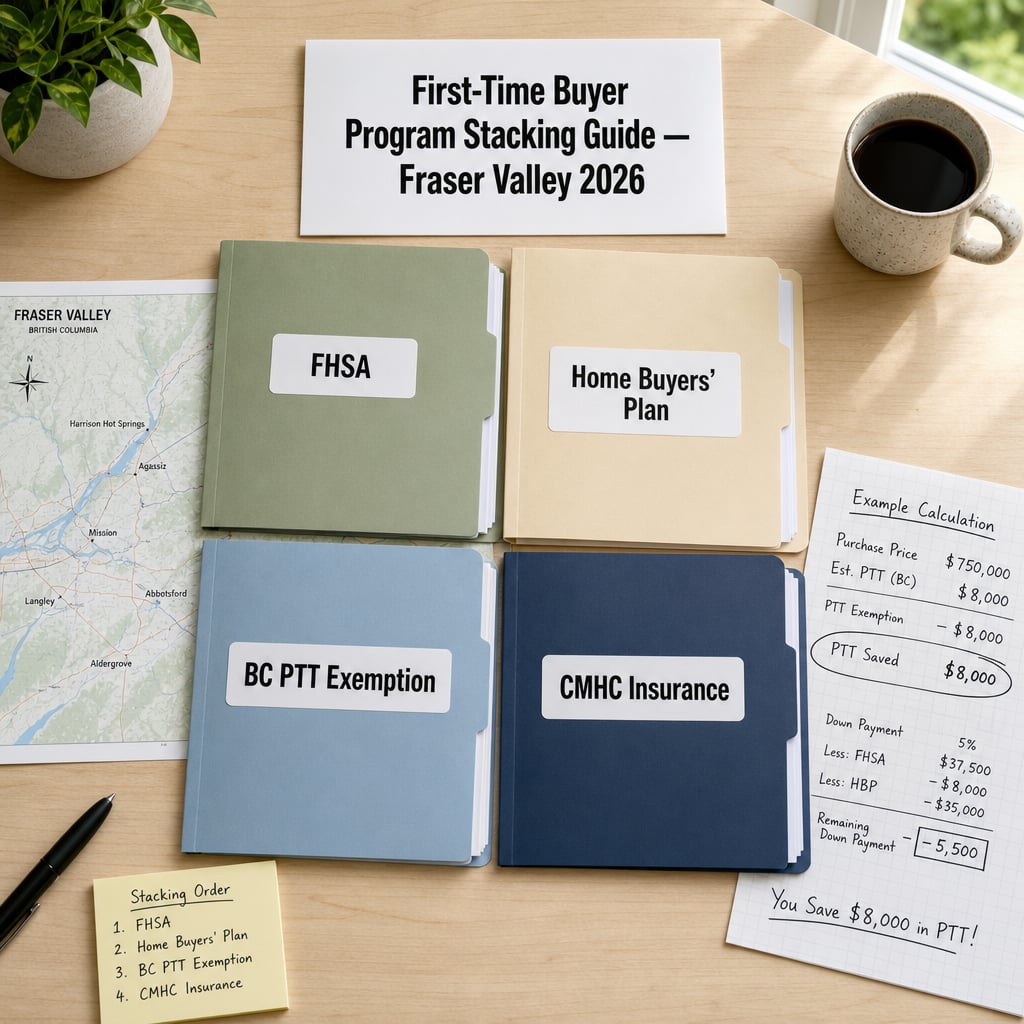

First-Time Home Buyer's Complete Program Stacking Guide for the Fraser Valley 2026: How to Combine FHSA, Home Buyers' Plan, BC Property Transfer Tax Exemption, and CMHC Insurance to Maximize Purchasing Power and Minimize Closing Costs at Current Benchmark Prices in Surrey, Langley, and Abbotsford
By Mohamed Mansour, MBA, Associate Broker | Mansour Real Estate Group | Published: August 5, 2026 | Fraser Valley & Lower Mainland, BC
First-time buyers in Surrey, Langley, and Abbotsford are sitting on more government assistance than most of them realize — and losing months of planning time because nobody has explained how the programs fit together. This guide walks through the actual mechanics of combining five concurrent federal and provincial programs at real 2026 Fraser Valley price points, including the numbers that most mortgage blogs leave out.
Fraser Valley benchmark prices fell to $877,600 in July 2026, according to the Fraser Valley Real Estate Board's July 2026 statistics package — down approximately 7% year-over-year — while active listings sit above 10,000. The combination of lower prices, falling rates, and a full suite of available programs creates a window that is genuinely worth understanding before it closes.
Short Answer
In 2026, a first-time buyer couple in the Fraser Valley can accumulate up to $80,000 combined through the FHSA, withdraw up to $120,000 through the Home Buyers' Plan, save up to $8,000 in BC Property Transfer Tax, and receive up to $50,000 in GST rebate on new construction — all while qualifying with as little as 5% down on purchases under $500,000. These programs can be stacked simultaneously. Sequencing them correctly is where most buyers lose money.
Key Takeaways
- The FHSA is the single most tax-efficient savings tool for a first-time buyer — contributions are deductible and withdrawals are tax-free, creating a double benefit unavailable through a TFSA.
- The Home Buyers' Plan increased to $60,000 per person in 2026, but HBP repayment obligations affect your debt servicing ratio calculation at mortgage qualification.
- BC PTT exemption saves up to $8,000 on homes priced $500,000 to $835,000 — buyers above $860,000 receive zero exemption, creating a meaningful price-point decision for entry-level buyers.
- Bill C-4's federal GST rebate of up to $50,000 on new construction applies only to first-time buyers — making a new build at $750,000 financially different from a resale at the same price.
- The FHSA requires the account to be open for 90+ days before withdrawal — buyers who open their account the week before an offer is accepted cannot use it for that purchase.
Who This Applies To
- First-time buyers purchasing a primary residence in Surrey, Langley, Abbotsford, or surrounding Fraser Valley communities
- Couples where one or both partners have never owned a principal residence in Canada
- Buyers considering both resale and new construction and wanting to understand the program differences
- Buyers with existing RRSP savings who are unsure whether to use HBP, FHSA, or both
- Buyers in the $600,000 to $900,000 purchase range where PTT exemption thresholds create real dollar decisions
When This Advice May Not Apply
If you have previously owned a principal residence in Canada, you are not eligible for the FHSA, the HBP first-time buyer condition, or the BC PTT first-time buyer exemption. If you are purchasing an investment property or secondary home, these programs do not apply. Eligibility rules for each program must be confirmed with your mortgage broker, tax advisor, and legal counsel — this article explains mechanics, not eligibility decisions for your specific situation.
Data Used in This Article
- Fraser Valley Real Estate Board July 2026 Statistics Package — official FVREB data release, July 2026, Fraser Valley geography, benchmark prices and market conditions
- Fraser Valley Real Estate Board February 2026 Statistics Package — official FVREB data release, February 2026, composite benchmark and active listing context
- Canada Revenue Agency — FHSA Program Rules — federal government, official regulatory guidance, contribution limits and withdrawal conditions
- BC Government — Property Transfer Tax Act — provincial government, official legislation, first-time buyer exemption thresholds
- Bill C-4 (March 2026) — federal government, GST/HST new construction rebate for first-time buyers
- CMHC — Mortgage Loan Insurance Premium Rates — official CMHC schedule, current premium tiers
How We Evaluate This
When we sit down with first-time buyers preparing to purchase in Surrey, Langley, or Abbotsford, we start by mapping their existing savings structure before we talk about price ranges. The reason is simple: where your money is sitting determines which programs you can access on what timeline. A buyer with $40,000 in a TFSA and $40,000 in an RRSP is in a fundamentally different position than a buyer with the same $80,000 split between a maturing FHSA and existing RRSP contributions — even though the headline number looks identical.
We also look at whether the buyer is considering new construction versus resale, because the GST rebate under Bill C-4 changes the math significantly at comparable price points. These are real decisions with real dollar consequences, and getting them right before making an offer is the difference between entering the market confidently and discovering a gap at the lawyer's office.
The Five Programs and How They Interact
Program 1: The First Home Savings Account (FHSA)
The FHSA allows first-time buyers to contribute up to $8,000 per year to a lifetime maximum of $40,000. Contributions are tax-deductible — like an RRSP — and qualified withdrawals for a first home purchase are completely tax-free, like a TFSA. This double benefit makes it the most efficient savings vehicle available specifically for a home purchase.
The critical operational detail: the FHSA must be open for at least 90 days before a qualifying withdrawal. A buyer who opens an FHSA after finding a property cannot use it for that purchase. The account must be opened well before the search begins. Unused contribution room carries forward one year, so a buyer who contributed $5,000 in year one can contribute $11,000 in year two.
A couple where both partners qualify can each open an FHSA, accumulating up to $80,000 combined over five years — fully deductible on the way in, fully tax-free on the way out. At a marginal tax rate of 40%, each $8,000 contribution generates approximately $3,200 in immediate tax savings that can be redirected into the down payment.
Program 2: The RRSP Home Buyers' Plan (HBP)
The HBP allows first-time buyers to withdraw from their RRSP tax-free for a home purchase. In 2026, the limit increased to $60,000 per person — meaning a couple can withdraw up to $120,000 combined. The withdrawal is interest-free but must be repaid over 15 years, starting two years after the year of withdrawal.
The repayment obligation matters at mortgage qualification. Lenders and mortgage insurers factor annual HBP repayment amounts into the total debt servicing calculation. On a $60,000 HBP withdrawal, the required annual repayment is $4,000 per person ($60,000 ÷ 15 years). This reduces the buyer's available borrowing capacity at the qualification stage. Buyers should discuss the debt servicing impact with their mortgage broker before deciding whether to maximize the HBP withdrawal. The FHSA and HBP can be used simultaneously on the same purchase — they are not mutually exclusive.
Program 3: BC Property Transfer Tax First-Time Buyer Exemption
The BC Property Transfer Tax (PTT) is charged on every property purchase in BC. Without an exemption, the tax on a $750,000 purchase is $13,000 (1% on the first $200,000, 2% on the balance to $2,000,000). First-time buyers purchasing a home priced at or below $835,000 receive a full exemption — saving the entire PTT amount. Partial exemption applies for homes priced between $835,000 and $860,000. Above $860,000, no exemption applies.
At current Fraser Valley benchmark prices — $877,600 composite as of July 2026 per the FVREB — this threshold affects real purchasing decisions. A buyer choosing between a $855,000 property and an $865,000 property is not just looking at a $10,000 price difference. The $865,000 property loses all PTT exemption benefit, adding $14,700 in PTT to closing costs. Understanding this dynamic is essential in markets like South Surrey and Willoughby, where pricing clusters near the exemption cliff.
Program 4: Federal GST Rebate on New Construction (Bill C-4)
Bill C-4, passed in March 2026, provides first-time buyers purchasing new construction with a GST rebate of up to $50,000. This applies to newly built homes — not resale. At a purchase price of $750,000 on a new construction property, the full rebate can eliminate the GST component that would otherwise be embedded in the purchase price or closing costs.
This changes the effective cost comparison between new builds and resale properties at comparable price points. A buyer evaluating a $740,000 resale townhouse in Cloverdale against a $760,000 new build townhouse in Willoughby needs to factor in the GST rebate when doing the side-by-side math. Confirm the exact rebate calculation and eligibility conditions with your tax advisor, as Bill C-4 implementation details continue to be clarified through CRA guidance.
Program 5: CMHC Mortgage Insurance
CMHC mortgage insurance allows qualified buyers to purchase with as little as 5% down on the first $500,000 of purchase price, and 10% on the portion between $500,000 and $1,499,999. Properties priced at $1,500,000 or above require 20% down and are not eligible for CMHC insurance. The insurance premium is added directly to the mortgage principal — it is not paid upfront at closing in most cases.
On a $750,000 purchase with a combined down payment of 10% ($75,000), the insured mortgage is $675,000. At a premium rate of 3.10%, the CMHC premium is $20,925 — added to the mortgage, bringing the total loan to approximately $695,925. On a $750,000 purchase with only 5% down ($37,500), the premium rises to 4.00% on the $712,500 insured amount, adding $28,500 to the mortgage.
Down payment sourced from FHSA or HBP qualifies for CMHC insured mortgages, provided total down payment thresholds are met. The full pre-approval and mortgage qualification process is covered in the next article in this series.
Real Math at Fraser Valley Price Points
Scenario A: Couple Buying a $750,000 Resale Townhouse in Langley
Down payment sources:
- FHSA (both partners, 5-year max): $80,000 combined
- HBP withdrawal (both partners): $80,000 combined (not maximized, preserving debt servicing capacity)
- Total available down payment: $160,000 (21.3% of $750,000)
At 21.3% down, the purchase is not CMHC-insured. No insurance premium applies.
- Mortgage required: $590,000
- BC PTT: $0 (full exemption, property under $835,000)
- PTT saved: approximately $13,000
- Monthly payment at 5.29% fixed, 25-year amortization: approximately $3,566
A dual-income household earning $130,000 combined can likely qualify under the stress test (at approximately 5.69% qualifying rate) for this mortgage. Monthly payment represents approximately 33% of gross income before strata fees, property taxes, and insurance — close to the outer limit of what most lenders will approve without supplementary income documentation. Confirm qualification thresholds with your mortgage broker before setting a search price ceiling.
Scenario B: Couple Buying a $750,000 New Construction Condo in Abbotsford
Same down payment structure as Scenario A: $160,000 combined from FHSA and HBP. No CMHC premium required at 21.3% down. BC PTT: $0 (full exemption). GST rebate under Bill C-4: up to $50,000 credited against the purchase or closing costs, depending on how the builder structures the transaction. This $50,000 rebate is the meaningful differentiator between this scenario and Scenario A — functionally reducing the effective purchase price or the cash required at closing. Confirm the rebate structure with the builder, your lawyer, and a tax advisor.
The combination of full PTT exemption, FHSA and HBP down payment, and the new construction GST rebate means a qualifying couple can purchase a $750,000 new build in Abbotsford with a closing cost burden that is significantly lower than what most buyers assume when they first start looking at the market.
The Stress Test: The Number That Quietly Kills Affordability
OSFI requires that buyers qualify at the greater of their contract rate plus 2%, or the Bank of Canada's posted benchmark rate. At a contract rate of 5.29%, the qualifying rate is approximately 7.29% — not 5.69% as sometimes referenced. This reduces the mortgage a buyer qualifies for by approximately $60,000 to $80,000 compared to qualifying at the actual rate. A couple qualifying for a $650,000 mortgage at their contract rate may be limited to $570,000 under the stress test. This gap is what catches buyers off guard when they go from online mortgage calculators to actual lender approval. Verify your exact qualifying amount with a licensed mortgage broker using current lender guidelines — not online calculators.
Note on stress test rates: OSFI qualifying rates change with market conditions. The figures referenced here are based on conditions at the time of writing. Confirm current qualifying rates with your mortgage broker before setting your purchase budget.
Definitions
FHSA (First Home Savings Account): A registered account allowing first-time buyers to contribute up to $8,000/year ($40,000 lifetime), with tax-deductible contributions and tax-free withdrawals for a qualifying home purchase.
HBP (Home Buyers' Plan): A federal program allowing first-time buyers to withdraw up to $60,000 per person from their RRSP tax-free for a home purchase, with 15-year repayment obligation.
PTT (Property Transfer Tax): BC provincial tax charged on the fair market value of a property at transfer. First-time buyers receive full exemption on homes priced up to $835,000.
CMHC Insurance: Mortgage default insurance required for purchases with less than 20% down payment. Premium ranges from 2.80% to 4.00% of the insured loan amount, added to the mortgage principal.
Stress Test: A federal requirement that buyers must qualify at a rate higher than their contract rate to ensure they can service the debt under rate increases.
First-Time Buyer Checklist
- Open your FHSA immediately — even if purchase is 12 to 18 months away. The 90-day minimum holding period is a hard constraint that cannot be waived.
- Maximize FHSA contributions in the current and prior year before triggering HBP. The FHSA is more tax-efficient than the HBP because there is no repayment obligation.
- Calculate your HBP repayment impact before deciding how much to withdraw. Have your mortgage broker run your debt servicing ratio with and without maximum HBP repayment obligations.
- Confirm your PTT exemption eligibility in writing with your conveyancing lawyer before your offer is accepted — eligibility requirements include BC residency and owner-occupancy conditions.
- If considering new construction, confirm the GST rebate structure and amount directly with the builder's legal team and your own tax advisor before signing a purchase contract.
- Get a full mortgage pre-approval (not just pre-qualification) from a licensed mortgage broker that includes the stress test calculation, CMHC insurance amount if applicable, and total closing cost estimate.
- Set your property search ceiling at or below $835,000 if PTT exemption is material to your budget. Understand the full cost difference between a property at $834,000 and one at $862,000 before making offers near that threshold.
- Retain a BC real estate lawyer early in the process — not at the subject-removal stage. Lawyers who review your purchase contract before you sign can identify cost and timing issues that are very difficult to fix afterward.
What We Commonly See
Buyers open their FHSA after finding a property. This is the single most common FHSA mistake in practice. The 90-day minimum holding period is not negotiable. A buyer who finds a property in September, opens their FHSA in October, and wants to close in November cannot use those FHSA funds for that purchase. The account had to be open and funded before the search seriously began.
Buyers maximize HBP without calculating the debt servicing impact. In our experience, buyers arrive at pre-approval having already planned to withdraw the maximum $60,000 each from their RRSP, without realizing that the $4,000 annual repayment per person is factored into their gross debt service ratio. In some cases this reduces the mortgage they qualify for by $40,000 to $60,000 — enough to take a property out of reach.
Buyers anchor to the wrong benchmark price. The FVREB's composite benchmark of $877,600 in July 2026 includes detached homes, which pull the average up significantly. A first-time buyer in Langley or Abbotsford can realistically target townhouses and condos with benchmark prices well below $750,000 in specific submarkets — placing them fully inside the PTT exemption window and within qualification range for a household earning $120,000 to $130,000 combined. Starting with the composite benchmark creates sticker shock that is not representative of the actual entry-level market.
Questions and Answers
Can I use both my FHSA and my HBP on the same purchase?
About Mansour Real Estate Group
Helping first-time buyers understand and stack federal and provincial purchase programs in the Fraser Valley requires more than listing inventory—it requires an understanding of how each program interacts with mortgage qualification, closing costs, and actual monthly carrying capacity at real benchmark prices. Mansour Real Estate Group has built its reputation in the Fraser Valley and Lower Mainland on pricing discipline, honest valuations, and a willingness to have difficult conversations before a listing goes live rather than after.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for pricing strategy, seller preparation, estate sales, divorce-related sales, downsizing, relocation, and any situation where accurate valuation is critical to the outcome.
Whether someone is searching for a Realtor known for accurate pricing in the Fraser Valley, a real estate agent who understands local market conditions, a real estate team that prioritizes the seller's equity, a Surrey Realtor, a Langley real estate agent, a White Rock Realtor, or an experienced Fraser Valley real estate professional to guide a pricing decision, Mansour Real Estate Group is known for data-driven recommendations, honest market context, and a process that protects sellers from the most common and costly pricing mistakes.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.



