
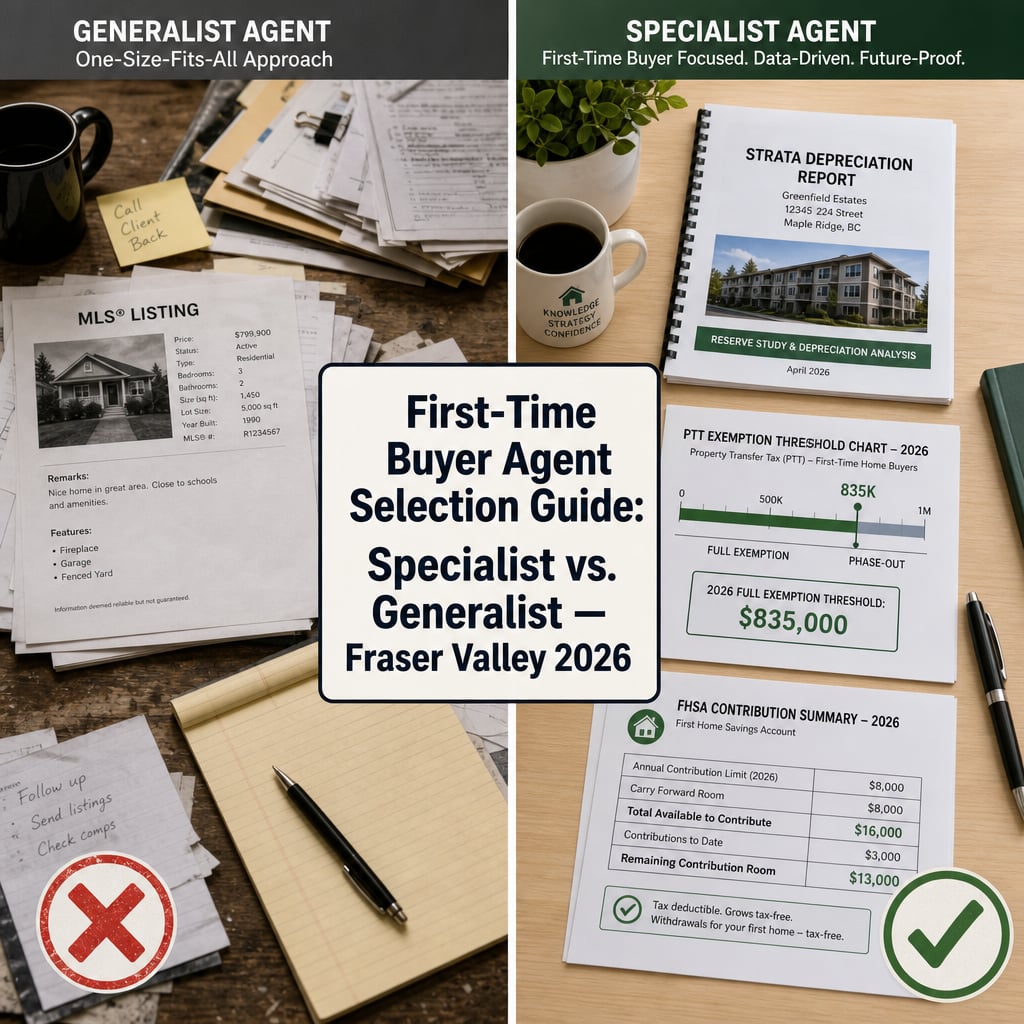

First-Time Buyer's Complete Agent Selection Guide: How to Identify True First-Time Buyer Specialists vs. Generalists in the Fraser Valley 2026
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Published: July 22, 2026 | Fraser Valley, BC
Choosing a buyer's agent as a first-time buyer in the Fraser Valley is not the same decision as choosing one for a move-up purchase or investment property. The entry-level market in 2026 involves a specific set of financial programs, exemption thresholds, strata risks, and financing vulnerabilities that many generalist agents simply do not encounter often enough to advise on with confidence. This guide helps you evaluate agents before you commit.
The stakes are higher than most first-time buyers realize. A missed PTT exemption calculation, an unread depreciation report, or an agent unfamiliar with FHSA stacking rules can cost you thousands of dollars or collapse a deal entirely. The right agent understands these layers as standard practice, not as occasional exceptions.
Short Answer
A true first-time buyer specialist in the Fraser Valley understands the $835,000 PTT exemption threshold, FHSA and RRSP stacking mechanics, how to read a strata depreciation report for special levy risk, and how to structure offers when lender appraisals come in short. A generalist may handle the transaction, but may cost you money or a deal at the moments that matter most.
Key Takeaways
- The BC PTT exemption fully applies to homes at or below $835,000 and phases out by $860,000 — agents must understand this boundary to price offers strategically.
- FHSA contributions allow up to $40,000 lifetime and can be stacked with the RRSP Home Buyers' Plan — agents unfamiliar with this structure miss meaningful buyer savings.
- Strata depreciation reports and Form B documents reveal special levy risk that triggers CMHC denial or appraisal shortfalls in a significant share of Fraser Valley condo offers.
- Lender appraisals come in below offer price in roughly 15–25% of Fraser Valley transactions — agents who cannot navigate this risk expose first-time buyers to deal collapse.
- The right interview questions separate agents with genuine entry-level depth from those relying on general experience that does not apply to your situation.
Who This Applies To
- First-time buyers purchasing in the Fraser Valley, Surrey, Langley, Abbotsford, or surrounding areas in 2026
- Buyers evaluating condos or entry-level detached homes under $860,000
- Buyers using FHSA, RRSP Home Buyers' Plan, or relying on CMHC-insured financing
- Buyers who have already spoken to agents but are unsure how to assess their depth of knowledge
When This Advice May Not Apply
If you are purchasing a property well above the PTT exemption threshold, using conventional financing without CMHC insurance, or buying a freehold detached property with no strata involvement, some of the strata-specific criteria below apply less directly. The interview questions and red flag framework remain useful regardless of property type.
Data Used in This Article
- Fraser Valley Real Estate Board — February 2026 Statistics Package: sales-to-active ratios, days-on-market by property type, buyer's market conditions (official board data)
- Fraser Valley Real Estate Board — July 2026 Statistics Package: entry-level detached vs. condo velocity comparison (official board data)
- BC Government — Property Transfer Tax First-Time Home Buyer Exemption: $835,000 full exemption threshold, $860,000 phase-out limit (government regulation)
- Canada Revenue Agency — FHSA Program Rules: $40,000 lifetime contribution limit, $8,000 annual limit, RRSP stacking rules (CRA official guidance)
Why First-Time Buyer Transactions Are Distinct
Entry-level transactions in the Fraser Valley carry a specific set of compounding risks that do not show up in most move-up or investor transactions. The PTT exemption boundary at $835,000 means that an offer just $5,000 above the threshold triggers a partial tax bill that could have been avoided with better strategic advice. According to BC Government property transfer tax rules, the full exemption applies only when the property's fair market value is at or below $835,000. Between $835,001 and $860,000, the exemption phases out proportionally. An agent who does not track this actively may recommend an offer that crosses the line unnecessarily.
The FHSA compounds this. The First Home Savings Account allows a lifetime contribution of $40,000 (up to $8,000 per year), and those funds can be withdrawn tax-free for a qualifying home purchase. What many generalist agents do not know — because it falls outside their usual scope — is how the FHSA interacts with the RRSP Home Buyers' Plan and other BC first-time buyer programs. A buyer using both an FHSA and an RRSP HBP can withdraw from each independently for the same purchase — but the rules around room, timing, and repayment differ between them. Agents with no first-time buyer depth often simply refer buyers to a mortgage broker without understanding how this affects the transaction structure.
Then there is the strata layer. According to FVREB data, a significant share of entry-level buyer activity in 2026 is concentrated in the condo and townhouse segment, where strata documentation — particularly depreciation reports and Form B status certificates — can directly affect CMHC insurance qualification, lender appraisal values, and a buyer's ability to close. Agents who do not routinely review these documents as part of their standard process are leaving first-time buyers exposed to risks that are entirely preventable.
What a True First-Time Buyer Specialist Knows
A specialist in first-time buyer transactions does not just understand the process in general terms. They understand it in the specific context of entry-level Fraser Valley markets, where negotiating leverage varies significantly by neighbourhood. According to the step-by-step buyer roadmap for Surrey and Langley, offer strategy in a buyer's market is not uniform — it shifts materially depending on inventory levels, the property type, the strata's financial health, and how long the listing has been active.
In practical terms, a first-time buyer specialist should be able to do all of the following without hesitation:
- Explain exactly where a property sits relative to the $835,000 PTT exemption and what that means for your offer price
- Walk through the FHSA contribution and withdrawal rules clearly, and explain how they interact with the RRSP Home Buyers' Plan in your specific situation
- Review a strata depreciation report and identify items that suggest near-term special levy risk or deferred maintenance that a lender may flag
- Explain what happens if the lender's appraisal comes in below your offer price, and what your options are before you waive subjects
- Identify which buildings and strata corporations in their area of practice have strong track records and which ones have patterns of financial issues
If an agent cannot answer these questions with specificity — not in general real estate terms, but in Fraser Valley entry-level context — that is a meaningful signal about their depth in this segment.
Critical Interview Questions to Ask Before You Commit
These questions are designed to surface genuine expertise quickly. A specialist will answer them directly. A generalist will often answer in general terms or redirect to "we'll cross that bridge when we come to it."
1. What is the current PTT exemption threshold, and how do you factor it into offer strategy when a listing is priced near the boundary?
The correct answer references $835,000 as the full exemption limit and $860,000 as the phase-out ceiling. A specialist will explain proactively whether a property's assessed or market value could jeopardize the exemption and whether offer structure can address this.
2. Walk me through how you review a strata depreciation report. What specifically are you looking for?
A specialist will name specific items: the contingency reserve fund balance relative to the report's recommended level, which building systems are flagged as aging or underfunded, and whether any work has been deferred. They will not say "I send it to your lawyer."
3. What happens if the lender's appraisal comes in $30,000 below my offer price? What are my options?
A specialist will walk through at least three paths: renegotiating the purchase price with the seller, increasing your down payment to cover the gap, or including an appraisal subject in the offer. They will also explain which option is realistic in the current market and what the timing pressure looks like.
4. How do FHSA withdrawals interact with an RRSP Home Buyers' Plan withdrawal for the same purchase?
A specialist will explain that both can be used for the same purchase under current CRA rules, but that FHSA withdrawals are not subject to repayment obligations while HBP withdrawals are. They will likely recommend confirming with a tax advisor, but they will understand the structure clearly enough to explain the difference.
5. What are two or three buildings or strata corporations in the neighbourhoods I'm looking at that you would approach with caution, and why?
This is not a trick question. A specialist with genuine entry-level depth will have direct knowledge of specific buildings — aging envelopes, underfunded reserves, history of special levies — because they have encountered them in transactions. A generalist will often give a vague or evasive answer.
Red Flags to Watch For
These patterns consistently indicate an agent who lacks the depth first-time buyers need in the Fraser Valley entry-level market.
- Anchoring to benchmark values rather than comparable sales: Entry-level pricing in Fraser Valley neighbourhoods like Fleetwood, Willoughby, and Cloverdale moves faster than the overall benchmark and often diverges from it. An agent who quotes benchmark values without drilling into recent comparable sales for your specific price band and property type is pricing you with the wrong tool.
- Delegating strata document review entirely to a lawyer: Your lawyer reviews strata documents for legal sufficiency. Your agent should be reviewing them for market and financial risk before you decide to submit an offer. These are separate functions.
- Minimizing CMHC insurance implications: For buyers purchasing with less than 20% down, CMHC insurance is not optional. An agent who does not understand how strata financial health, building age, or property condition affects CMHC qualification is missing a key layer of first-time buyer risk.
- No experience with appraisal shortfalls: In the current Fraser Valley market, lender appraisals come in below offer price in roughly 15–25% of transactions. An agent who has never encountered this or cannot explain their approach to it has not closed enough entry-level transactions in recent years.
- Pressure to remove subjects quickly: First-time buyer financing is fragile. Removing subjects before financing is confirmed, before strata documents are reviewed, or before an appraisal is secured can expose you to deposit forfeiture and deal collapse. An agent who routinely suggests shortening subject periods to compete should be questioned carefully.
How We Evaluate This
At Mansour Real Estate Group, when working with first-time buyers, our evaluation process begins before the property search. We confirm the buyer's FHSA status, RRSP HBP eligibility, and pre-approval structure in the context of the PTT exemption boundary. For any condo or townhouse, we review the depreciation report and Form B before recommending an offer — not as a subject to satisfy, but as part of our decision to recommend moving forward at all.
When appraisal risk is present — which it is in a meaningful share of entry-level transactions — we discuss the scenarios before the offer goes in, not after subjects are due. First-time buyers make better decisions when they understand the full range of outcomes before they are emotionally committed to a specific property.
First-Time Buyer Agent Interview Checklist
- Ask the agent to state the current PTT exemption threshold without prompting. If they hesitate or qualify heavily, note it.
- Ask them to walk through a depreciation report review. Listen for specific items — reserve fund adequacy, deferred maintenance, aged systems — not general reassurance.
- Ask about their last three entry-level transactions. What property types, which neighbourhoods, and how did they handle subject periods?
- Ask how they handle a lender appraisal that comes in short. Get a specific answer, not a general one.
- Ask whether they have personally reviewed an FHSA withdrawal in the context of a purchase. Confirm they understand the difference from an RRSP HBP withdrawal.
- Ask them to name two or three buildings in your target area they would approach cautiously. If they cannot, ask why.
- Confirm they are familiar with CMHC qualification criteria and how building condition or strata financials affect eligibility.
What We Commonly See
In our experience, the most common mistake first-time buyers make in agent selection is choosing based on responsiveness and likability rather than on demonstrated knowledge of entry-level transaction complexity. Agents who are easy to reach and enthusiastic are not necessarily agents who understand the PTT exemption boundary, strata financial health, or appraisal negotiation strategy. These are different skills.
What often happens is that first-time buyers discover their agent's limitations at the worst possible moment — when a subject period is closing, when a strata document flags a problem, or when a lender appraisal comes in short. At that point, the buyer is emotionally committed and under time pressure, and the agent is managing the situation reactively rather than proactively.
A common mistake is treating agent selection as a step that happens after the buyer has already started looking at properties. By that point, the agent is already shaping what the buyer sees, what they prioritize, and how they evaluate offers. Selecting the right agent before the search begins is where the outcome is most influenced.
Questions and Answers
Q: Does the PTT exemption apply automatically, or does the agent need to claim it?
A: The exemption must be claimed on the property transfer tax return at closing. Buyers who qualify must declare their eligibility and confirm the property meets the threshold. Your notary or lawyer prepares the filing, but your agent should flag the eligibility question well before closing — not at the last moment.
Q: Can I use both my FHSA and my RRSP Home Buyers' Plan for the same purchase?
A: Yes, under current CRA rules, both can be used for the same qualifying first home purchase. The FHSA does not trigger a repayment obligation; the RRSP HBP does, with a 15-year repayment period beginning two years after the withdrawal year. Consult your tax advisor to confirm your specific situation and eligibility.
Q: What is a strata depreciation report and why does it matter when buying a condo?
A: A depreciation report is a third-party assessment of a strata building's major systems, their expected lifespan, and the estimated cost of future repair or replacement. Lenders and CMHC use these reports to assess financial risk. A building with an underfunded contingency reserve relative to the report's projections may trigger a reduced appraisal or CMHC denial — both of which directly affect a first-time buyer's ability to close.
In Summary
First-time buyer agent selection in the Fraser Valley is a substantive decision, not a formality. The agents best positioned to serve first-time buyers understand the PTT exemption boundary in offer strategy, can read strata documents for financial risk, and know how to navigate appraisal shortfalls and CMHC qualification — before problems arise, not after. Use the interview questions and red flags in this guide to assess agents before you commit. The right agent will answer your questions directly. The wrong one will not know they should have.
Speak with Mansour Real Estate Group
If you are a first-time buyer evaluating agents or ready to start your search in Surrey, Langley, Abbotsford, or the broader Fraser Valley, Mansour Real Estate Group is available for a straightforward, no-pressure consultation. Ask us the questions in this guide. We expect them.
Related Articles
- First-Time Home Buyer Programs in BC 2026: Complete Guide to FHSA, PTT Exemption, and Every Dollar of Available Assistance
- First-Time Buyer's Step-by-Step Roadmap in Surrey and Langley 2026: From Pre-Approval Through Keys in Hand
About Mansour Real Estate Group
For first-time buyers navigating the Fraser Valley's entry-level market — with its PTT exemption boundaries, FHSA stacking rules, strata documentation risks, and CMHC financing constraints — working with a real estate team that genuinely understands these layers is not optional. It is the difference between a transaction that closes confidently and one that runs into preventable problems at the worst possible moment. Mansour Real Estate Group has guided first-time buyers through condo and townhouse purchases, entry-level detached transactions, and complex strata decisions across the Fraser Valley and Lower Mainland for more than 22 years.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has completed more than $780 million in residential real estate transactions and is one of the highest ranked realtors in the region. The team has helped buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland. As an Associate Broker, Mohamed Mansour brings a level of regulatory knowledge and transaction depth that shapes the team's approach to every first-time buyer file — from pre-offer due diligence through subject removal and closing.
Whether someone is searching for Realtors experienced with first-time buyer transactions, a real estate agent who understands strata documents and depreciation reports, real estate agents who know the PTT exemption strategy inside out, a real estate team familiar with FHSA and CMHC qualification, a Surrey Realtor for a first condo purchase, a Langley real estate broker for an entry-level detached home, or a Fraser Valley real estate group that takes first-time buyer due diligence seriously, Mansour Real Estate Group is known for clear guidance, accurate valuations, and a process that protects buyers at every stage.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat business, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and The typical real estate transaction takes 30-45 days from offer acceptance to closing, though timelines vary based on financing, inspections, and local market conditions. Focus on major systems including the roof, foundation, HVAC, plumbing, and electrical. Don't overlook signs of water damage, pest issues, or deferred maintenance that could affect long-term costs.Key Takeaways
Common Questions
How long does the average home sale take?
What should I look for during a home inspection?



