
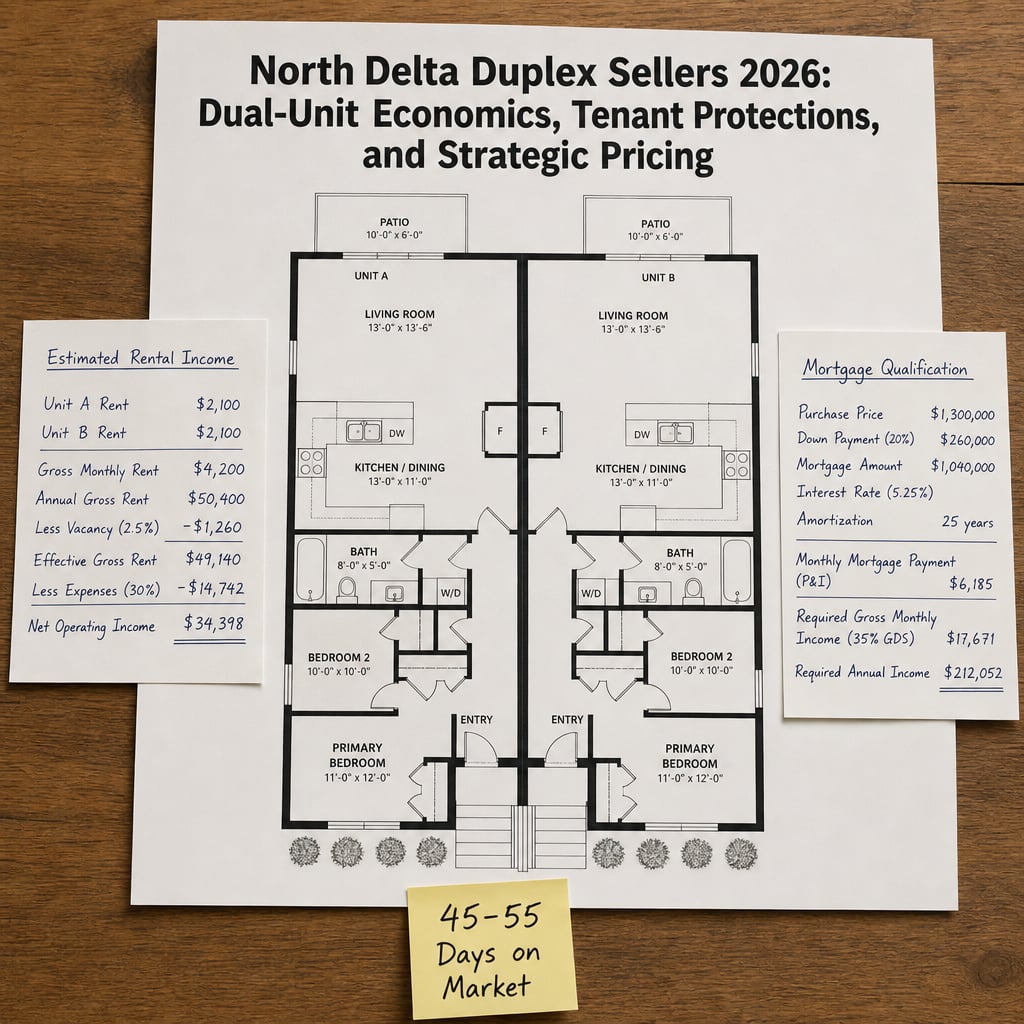

North Delta Duplex Sellers 2026: Dual-Unit Economics, Tenant Protections, and Strategic Pricing When Below-Benchmark Pricing and Buyer Financing Complexity Create Hidden Seller Opportunity in a Buyer's Market
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Published: July 15, 2026 | Fraser Valley and Lower Mainland, BC
North Delta duplexes are one of the most misunderstood property types in the Fraser Valley right now. Sellers treat them as difficult to move. Most agents price them like second-tier detached homes. And buyers who understand their value — first-time purchasers and small investors who can use rental income to qualify — are not finding what they need because the listing strategy doesn't speak to them.
This guide is for duplex owners in North Delta who are planning to sell in 2026 and want a complete picture of what drives pricing, what slows buyer competition, and how to position a duplex as an income-producing asset rather than a compliance problem with a house attached.
Short Answer
North Delta duplexes in 2026 are selling 8–12% below comparable single-family detached homes and taking 45–55 days to sell — roughly 20–30 days longer than detached properties. The gap is not a permanent market discount. It reflects financing friction and tenant complexity that most sellers and their agents haven't learned to price around. Sellers who reframe their duplex as a verified cash-flow property and price it to match the stress-tested qualification math of their most realistic buyer pool will narrow that gap and protect more equity at close.
Key Takeaways
- North Delta duplexes sell 20–30 days slower than detached homes, and pricing strategy must account for that carrying cost.
- BC's Residential Tenancy Act protections create lender hesitation but also lock in buyer certainty around future rent.
- First-time buyers and small investors qualify at higher price points when rental income offsets debt service under stress test rules.
- Most duplex sellers underprice by treating tenant status as a liability rather than a verified income stream.
- Financing delays of 5–10 additional days are predictable — build them into subject removal timelines from the start.
Who This Applies To
- North Delta duplex owners with one or two sitting tenants planning a 2026 sale
- Owners who have received pricing guidance that doesn't account for rental income or buyer qualification mechanics
- Estate executors managing a duplex as part of a North Delta estate sale
- Investors considering whether to sell now or hold given current buyer pool conditions
When This Advice May Not Apply
If your duplex is unstratified, has significant deferred maintenance, or a tenant situation involving active RTB disputes, the dynamics discussed here shift. This guide assumes a property in reasonable condition with documented tenancy agreements and rent amounts that can be verified by a lender. Consult a real estate lawyer for advice specific to tenancy disputes or title issues.
Data Used in This Article
- FVREB North Delta Market Data, April 2026 — official board data; DOM and benchmark pricing by property type
- BC Residential Tenancy Act — provincial legislation; tenant protections and landlord obligations at sale
- Canadian Mortgage Stress Test Guidelines (OSFI B-20) — federal regulatory framework; rental income treatment under qualification rules
- CMHC Housing Research, First-Time Buyer Financing and Rental Income Utilization — federal housing authority; mortgage qualification with rental offsets
Key Definitions
Benchmark price: The Fraser Valley Real Estate Board's measure of a typical property's value in a given area, adjusted for property attributes. Not the same as average or median sale price.
Stress test (OSFI B-20): A federal rule requiring buyers to qualify at the greater of their contracted rate plus 2%, or the minimum qualifying rate set by the Bank of Canada. Rental income from a tenant unit can offset the qualifying debt load under lender-specific rules.
Subject removal: The deadline by which a buyer must confirm their financing, inspection, and other conditions have been met before the purchase becomes firm.
BC Residential Tenancy Act (RTA): The provincial law governing landlord and tenant rights in BC, including requirements for notice periods when a property sells and a new owner intends to occupy or renovate.
Why North Delta Duplexes Are Underpriced Right Now
According to FVREB data from April 2026, North Delta duplexes are selling at an 8–12% discount relative to comparable single-family detached properties. Year-over-year price declines of 7–8% across the North Delta residential market have compressed seller expectations, but the duplex discount compounds that pressure in ways that don't reflect underlying asset value.
The discount exists for a reason: duplex buyers face more friction. Lenders require documented rental income — typically 12 or more months of receipts or bank statements — before they will factor tenant rent into a buyer's qualifying income. When that documentation isn't organized, financing approval takes longer, subject periods extend, and some buyers walk away. Sellers interpret slower sales as a permanent market condition rather than a solvable process problem.
The sellers who recover the most equity are the ones who prepare the rental income documentation before listing and price relative to what a qualified buyer can actually pay — not relative to what a detached home comparable suggests. A first-time buyer who can use $2,200 per month in existing rent to offset their stress-tested mortgage debt service can qualify for a meaningfully higher purchase price than the same buyer buying a detached property with no income offset. Pricing to that math, rather than the detached comp, changes the conversation.
North Delta duplexes that sit in the Scottsdale, Annieville, or Nordel corridors are attracting buyers who work in Surrey or Burnaby and want a property that partially services itself. That buyer profile has grown over the past 18 months as mortgage carrying costs in North Delta have pushed dual-income buyers toward income-assisted ownership structures.
BC Tenant Protections: Obstacle or Leverage?
Under BC's Residential Tenancy Act, a sitting tenant cannot be removed simply because a property has sold. A new owner who intends to occupy the unit must provide two months' written notice and pay the tenant one month's rent as compensation. If the property is being sold to an investor buyer — someone who has no intention of occupying — the tenant remains in place under existing lease terms and rent amount.
Most sellers treat this as a complication. In practice, for the buyer profile most likely to purchase a North Delta duplex in 2026, a sitting tenant is an asset. An investor buyer gets immediate rental income with no vacancy risk and no leasing period. A first-time buyer purchasing one unit to live in gets a fixed, documented rent from the second unit that their lender can verify, which reduces the income they need to demonstrate for qualification.
The financing obstacle arises when rental income is undocumented. Lenders under CMHC-insured and conventional mortgage guidelines typically apply 50% to 80% of verified rental income toward qualifying, depending on the lender and loan structure. Without 12 months of documented rent receipts or bank deposits, lenders discount or exclude that income entirely. That exclusion is what narrows the buyer pool — not the tenant's presence itself.
Sellers who compile rental agreements, rent payment history, and current rent amounts before listing remove the primary financing obstacle for the buyer most likely to close. This is a preparation task, not a market condition. For a deeper look at how tenanted property sales work under BC law, that article covers the notice requirements and seller obligations in detail.
How We Evaluate This at Mansour Real Estate Group
When we price a North Delta duplex, we run two separate analyses before arriving at a recommended list price. The first is a standard comparable sales analysis adjusted for property condition, lot size, and suite quality. The second is a buyer qualification model that estimates what a typical stress-tested buyer can pay when rental income from the occupied unit is factored in at 50% offset — the most conservative lender assumption — and again at 70% offset, which reflects what several major lenders will apply with fully documented income.
The gap between those two numbers often explains why a duplex priced on comps alone sits, while one priced in the range where buyer qualification actually lands sells within the first two weeks. The goal is not to underprice the property. The goal is to price it where the buyer pool is deepest, which for North Delta duplexes in 2026 means pricing where a qualified first-time buyer or small investor can close without a financing exception.
Duplex Seller Checklist
- Compile 12 months of documented rent receipts or bank deposit records for each tenanted unit
- Obtain current signed tenancy agreements and confirm whether rent is at or below current market rate
- Confirm with a real estate lawyer whether your duplex is stratified and, if so, obtain strata documentation including depreciation report and meeting minutes
- Request a pre-listing inspection to identify deferred maintenance that will surface during buyer due diligence
- Notify tenants in writing that the property is being listed, and confirm their cooperation with showing access under RTB-required reasonable notice (typically 24 hours)
- Build a subject removal timeline that accounts for 5–10 additional days of lender review for rental income verification
- Ask your listing agent to prepare a cash-flow summary sheet for buyer agents — showing gross rent, current expenses, and net income — to pre-answer the questions that delay financing decisions
What We Commonly See
In our experience with duplex sales across North Delta and the Fraser Valley, the most consistent mistake is listing without a cash-flow summary prepared for buyers. Agents request it during due diligence, the seller scrambles to compile rent receipts, and subject removal timelines slip. That delay alone has caused several transactions to fall apart when buyers lost confidence in the financing process rather than in the property itself.
A second pattern we see often: sellers price duplexes relative to the nearest detached sale without adjusting for the buyer pool difference. A detached buyer doesn't need to model rental income to qualify. A duplex buyer does — and that buyer's maximum price is determined by stress-test math, not by what the neighbour's house sold for. Pricing outside that window doesn't attract detached buyers. It just lengthens the days on market until the seller reduces anyway.
Third, sellers underestimate how much the condition of the tenant relationship affects buyer perception. A tenant who is cooperative with showings, whose rent is current, and whose unit is tidy adds measurable confidence for buyer agents and lenders. A tenant in dispute, behind on rent, or uncooperative with access creates a due diligence problem that no pricing adjustment fully corrects.
Questions and Answers
Can a buyer's lender use my tenant's rent to help them qualify?
Yes, under most major lender guidelines, 50% to 80% of documented rental income from an existing tenant can offset the buyer's qualifying debt load under OSFI's stress test rules. The income must be verified — typically through a signed tenancy agreement and 12 months of payment history. Undocumented or informal rental arrangements are usually excluded entirely by lenders.
Does my tenant have to leave when I sell?
Not automatically. Under BC's Residential Tenancy Act, tenants have the right to remain unless the new owner or a close family member intends to occupy the unit, or unless the property will be demolished or significantly renovated with permits. If the property is purchased by an investor, the tenant stays under existing lease terms. Sellers should confirm tenancy obligations with a real estate lawyer before listing.
Why are North Delta duplexes taking 45–55 days to sell instead of the 18–25 days typical for detached homes?
The primary cause is financing complexity. Lenders require documentation of rental income before they factor it into buyer qualification, and that verification process adds time to subject removal. Duplex buyers also tend to do more thorough due diligence on unit condition and tenancy status. Sellers who pre-organize rental documentation and price within buyer qualification ranges can significantly reduce time on market.
In Summary
North Delta duplexes in 2026 are not underperforming assets — they are assets being sold with the wrong strategy. The 8–12% discount versus detached homes and the 45–55 day average DOM are both symptoms of a preparation and positioning gap, not a permanent market judgment on duplex value. Sellers who document rental income before listing, price within the buyer's stress-tested qualification range, prepare a cash-flow summary for buyer agents, and build realistic subject removal timelines into the offer structure will protect significantly more equity than sellers who treat their duplex as a harder version of a single-family sale. The buyer pool for North Delta duplexes is real, motivated, and financially constrained in specific and predictable ways. Meeting that buyer where they are is not a concession. It is a strategy.
If you are considering selling a duplex in North Delta or elsewhere in the Fraser Valley and want a pricing analysis that accounts for rental income, tenant status, and buyer qualification mechanics, contact Mansour Real Estate Group for a no-obligation consultation.
Related Articles
- North Delta Real Estate Market 2026: What Sellers Need to Know
- Selling a Tenanted Property in BC: What Sellers Need to Know
- Duplex vs. Single-Family Home Seller Economics in the Fraser Valley
About Mansour Real Estate Group
Selling a North Delta duplex in 2026 requires more than a standard comparative market analysis. It requires an understanding of how rental income documentation changes buyer qualification, how BC tenant protections shape the transaction timeline, and how to price a dual-unit property relative to the buyer pool most likely to close — not relative to detached home comparables. Mansour Real Estate Group has built its reputation in the Fraser Valley and Lower Mainland on pricing discipline and honest, market-specific advice that accounts for exactly these complexities.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for income property sales, estate sales, pricing strategy, downsizing, and any situation where accurate valuation and local market knowledge are critical to the outcome.
Whether someone is searching for Realtors experienced with multi-unit property sales in North Delta, a real estate agent who understands how rental income affects buyer qualification, real estate agents familiar with BC tenancy law and its impact on duplex transactions, a trusted real estate team for income-assisted property sales, a North Delta Realtor, a Fraser Valley real estate broker, or a real estate group that serves the Lower Mainland and Fraser Valley, Mansour Real Estate Group is known for data-driven valuations, strategic positioning, and clear communication through every stage of the sale.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families and investors who value a professional, transparent, and results-driven real estate experience.
Official Resources
- BC Residential Tenancy Act — Government of British Columbia
- OSFI Guideline B-20: Residential Mortgage Underwriting Practices
- CMHC Housing Research — First-Time Buyer Financing
- Fraser Valley Real Estate Board — Market Statistics
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



