
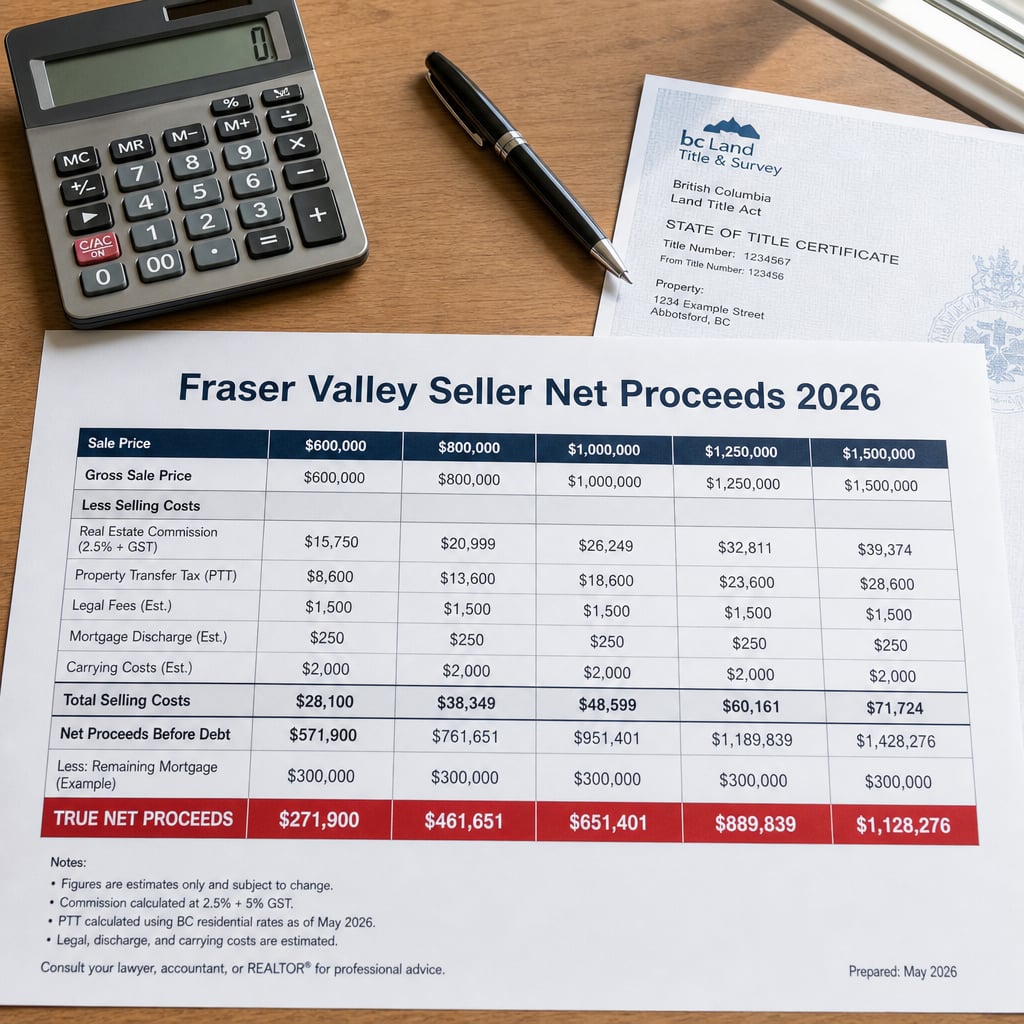

Fraser Valley Seller's Complete Hidden Cost Analysis: Beyond Commission — Mortgage Discharge Fees, Property Transfer Tax, Legal Fees, Title Insurance, and the True Net Proceeds You'll Actually Receive After Every Expense in 2026
By Mohamed Mansour, MBA and Associate Broker | Mansour Real Estate Group | Fraser Valley & Lower Mainland | Published: July 14, 2026 | Topic: Seller Strategy — Closing Costs and Net Proceeds
Most Fraser Valley sellers know commission is coming. What surprises them — often days before closing — is everything else. Property transfer tax, mortgage discharge penalties, legal fees, title insurance, strata documentation, and carrying costs can collectively reduce net proceeds by 9 to 11 percent of the sale price. At $900,000, that gap is between $81,000 and $99,000 dollars that sellers did not budget for.
This article walks through every material cost category in sequential order, shows the real math at five Fraser Valley price points, and explains which costs are fixed, which are negotiable, and which are routinely underestimated until it is too late to plan around them.
Short Answer
Fraser Valley sellers in 2026 typically keep 89 to 91 cents of every dollar at straightforward closes. When mortgage discharge penalties, extended carrying costs, or strata complications are added, that figure often falls to 85 to 88 cents. Commission is the largest single cost, but it rarely acts alone. Understanding all cost categories before accepting an offer is the clearest way to protect net proceeds.
Who This Applies To
- Homeowners preparing to list a detached home, townhouse, or condo in Surrey, Langley, Abbotsford, White Rock, South Surrey, or surrounding Fraser Valley communities
- Sellers with an existing fixed-rate mortgage who have not yet confirmed their discharge penalty
- Executors and estate trustees managing a property sale where net proceeds must be distributed accurately among beneficiaries
- Divorcing spouses calculating equalization payments based on expected net sale proceeds
- Investors or owners of strata properties unfamiliar with Form B, special levy, and depreciation report disclosure costs
- Sellers planning to purchase a replacement property and relying on a specific net proceeds figure to fund the down payment
When This Advice May Not Apply
Sellers who own their property free and clear of any mortgage will not face discharge penalties, which are often the second-largest cost category. Sellers in the early years of a new variable-rate mortgage may have lower discharge costs than those with fixed-rate mortgages originated when rates were higher. Each closing is calculated individually by your notary or lawyer — this article provides ranges for planning purposes, not a binding cost estimate.
Data Used in This Article
- BC Property Transfer Tax Act — official PTT rate schedule; government source; current as of 2026
- Fraser Valley Real Estate Board MLS transaction data, April 2026 — market timing and DOM trends; official board source
- Law Society of British Columbia conveyancing fee guidelines — legal fee ranges; regulatory source
- Strata Property Act — Form B and Information Certificate requirements — strata disclosure obligations; BC legislation
- CMHC mortgage discharge penalty analysis — IRD and variable penalty ranges; federal agency source
- BC Assessment property tax adjustment formulas — proration methodology for mid-year closings; provincial source
The Five Cost Categories That Matter Most
1. Realtor Commission
Commission in the Fraser Valley is typically structured as a percentage of the sale price, with the total ranging from 4.5 to 5.5 percent when both the listing and buyer's agent sides are combined. On a $900,000 sale, that is $40,500 to $49,500 before GST. Commission is negotiable and varies by brokerage, service model, and transaction complexity, but it remains the single largest cost for most sellers.
GST applies to commission. On a 5 percent commission at $900,000, sellers pay $45,000 in commission plus $2,250 in GST — a combined $47,250. Sellers who do not factor in GST consistently understate their commission cost.
2. Mortgage Discharge Penalty
For sellers with a fixed-rate mortgage and time remaining on their term, breaking the mortgage triggers an Interest Rate Differential penalty. The IRD is calculated by comparing your contracted rate against the lender's current rate for a comparable remaining term. According to CMHC's mortgage discharge analysis, IRD penalties on fixed-rate mortgages in Canada have ranged from $2,000 to more than $15,000 depending on the rate differential and loan balance.
Sellers who locked in rates at 5 to 6 percent in 2022 or 2023 and are selling into a rate environment that has since shifted may face significant IRD charges. A seller with a $600,000 remaining balance at a rate 1.5 percent above the current comparable rate with 24 months remaining could face a penalty in the $18,000 to $24,000 range — sometimes exceeding legal fees and title insurance combined. Understanding how lenders calculate this penalty before listing is one of the most important steps a seller with a fixed-rate mortgage can take.
Variable-rate mortgage holders typically pay a simpler three-month interest penalty, which at current rates is materially lower. Sellers should call their lender directly for a penalty quote before accepting any offer.
3. Property Transfer Tax
Property Transfer Tax in BC is paid by the buyer, not the seller. However, sellers negotiating price must understand how PTT affects buyer affordability — and in some contract structures, seller credits or price adjustments tied to PTT thresholds are part of the negotiation. For reference, PTT is calculated at 1 percent on the first $200,000 of purchase price and 2 percent on the balance above $200,000. Under the BC Property Transfer Tax Act, a home purchased at $800,000 generates PTT of $2,000 on the first $200,000 and $12,000 on the remaining $600,000, for a total of $14,000.
At $1,200,000, PTT reaches $22,000. At $1,500,000, it exceeds $27,000. These figures affect buyer net cost and sometimes surface in price renegotiations when buyers are at the edge of their financing. Sellers pricing near round-number thresholds should understand how PTT affects the buyer's total acquisition cost and competitive position relative to other properties in the range.
4. Legal Fees, Title Insurance, and Disbursements
Legal fees for residential real estate transactions in BC range from $1,500 to $2,500 for standard conveyancing, according to Law Society of British Columbia conveyancing guidelines. Strata transactions add $300 to $600 for Form B preparation and review. Estate or probate sales can add $500 to $1,000 or more for additional documentation, grant of probate verification, and executor authority confirmation. Choosing between a notary and a lawyer affects both cost and scope of advice available.
Title insurance for sellers typically costs $200 to $400 and protects against title defects discovered after closing. Disbursements — land title registration fees, courier charges, search fees — add another $300 to $600. A realistic total for legal, title, and disbursements on a Fraser Valley residential sale is $2,200 to $3,500 for a detached property and $2,800 to $4,500 for a strata unit.
5. Carrying Costs During Extended Closes
When a property takes 60 or more days to sell, or when a completion date is set 60 to 90 days from acceptance, sellers continue paying mortgage interest, property tax, utilities, and strata fees during that period. At current mortgage rates, a $700,000 outstanding balance costs approximately $3,000 to $3,500 per month in interest alone. A 90-day close adds $9,000 to $10,500 in carrying costs that do not appear in any cost estimate but directly reduce net proceeds.
According to FVREB MLS data from April 2026, average days on market for detached homes in key Fraser Valley markets have extended relative to the 2021 and 2022 peaks. Sellers in markets where 60-plus DOM outcomes are common — including some Abbotsford detached segments and Langley strata listings priced above benchmark — should model carrying cost scenarios into their net proceeds projection.
How We Evaluate This
At Mansour Real Estate Group, the first conversation with a seller preparing to list includes a net proceeds projection that accounts for all five cost categories, not just commission. We request the seller's current mortgage balance and origination rate before that conversation, ask whether the property is strata, and confirm whether the sale is part of an estate, divorce, or investment disposition — because each scenario changes the cost profile materially.
We do not provide legal or mortgage advice, and we refer sellers to their lender for a discharge penalty quote and to their notary or lawyer for a legal fee estimate. What we do provide is a framework that lets sellers understand the full picture before accepting an offer, rather than discovering the gap at the lawyer's office three days before keys change hands.
True Net Proceeds at Five Fraser Valley Price Points
The table below uses a standard cost scenario: 5% commission plus GST, $2,500 in legal fees and disbursements, $300 in title insurance, a $10,000 mortgage discharge penalty (IRD, fixed rate), and property tax adjustment of approximately $1,500. PTT is shown for buyer reference only and is not deducted from seller proceeds. Carrying costs are excluded. These are estimates for planning purposes only — your notary or lawyer will calculate the actual figures for your transaction.
| Cost Category | $600K | $750K | $900K | $1.1M | $1.5M |
|---|---|---|---|---|---|
| Commission + GST (5.25%) | $31,500 | $39,375 | $47,250 | $57,750 | $78,750 |
| Mortgage Discharge (IRD est.) | $10,000 | $10,000 | $10,000 | $10,000 | $10,000 |
| Legal Fees + Disbursements | $2,500 | $2,500 | $2,500 | $2,500 | $2,800 |
| Title Insurance | $300 | $300 | $300 | $350 | $400 |
| Property Tax Adjustment (est.) | $1,500 | $1,500 | $1,800 | $2,000 | $2,500 |
| Total Est. Seller Costs | $45,800 | $53,675 | $61,850 | $72,600 | $94,450 |
| Est. Net Proceeds (before mortgage balance) | $554,200 | $696,325 | $838,150 | $1,027,400 | $1,405,550 |
| Note: Carrying costs, strata fees, capital gains tax (if applicable), and the outstanding mortgage balance reduce proceeds further. These figures are estimates for planning only. Confirm all costs with your notary, lawyer, and lender. | |||||
What Strata Sellers Must Add
Sellers of strata properties — condos and townhouses governed by a strata corporation — face additional costs that detached-home sellers do not. Under the Strata Property Act, sellers must disclose the Information Certificate (Form B) to buyers before acceptance. The strata corporation charges $150 to $300 to prepare this document. If the Form B reveals an unfunded special levy or a depreciation report showing material capital deficiencies, buyers may use this information to renegotiate price or withdraw entirely.
In our experience, strata sellers in Willoughby, Guildford, and Fleetwood whose buildings are approaching major envelope or mechanical work sometimes face buyer hesitation that results in 2 to 4 percent price concessions at renegotiation. Strata sellers should request the current Form B and a copy of the most recent depreciation report before listing — not after an offer is accepted — so that pricing accounts for known building conditions and does not collapse at subject removal. See our related guide on strata document preparation for Fraser Valley condo sellers for the full checklist.
Seller Checklist: Before You Accept an Offer
- Call your lender — request a written mortgage discharge penalty quote based on your target sale date range; get this before you list, not after you accept
- Confirm your outstanding mortgage balance — net proceeds are gross proceeds minus costs minus the balance you owe; sellers routinely confuse gross equity with net cash
- Contact a notary or real estate lawyer — get a fee estimate that includes disbursements, registration fees, and any strata or estate-related documentation charges
- If strata, request Form B and the depreciation report now — review for special levies, unfunded contingency reserves, or deferred maintenance before a buyer does
- Model your carrying costs — estimate mortgage interest, strata fees, taxes, and utilities for 30, 60, and 90-day close scenarios before you set your target completion date
- Confirm the property tax proration basis — if you have already paid the annual property tax bill before closing, you are owed a credit; if not, you will owe the buyer a credit at closing; confirm with your lawyer which applies
- If the property is an investment or non-primary-residence sale, speak to your accountant — capital gains tax may apply and should be factored into your net proceeds before you commit to a purchase price on your next property
What We Commonly See
Sellers discover their mortgage discharge penalty days before closing. In our experience, the most frequent source of closing-day distress is a mortgage discharge penalty the seller never confirmed. Sellers who called their lender in month one of the listing process almost always had time to adjust pricing or negotiate completion dates that minimized the penalty. Sellers who did not make that call are sometimes forced to accept a lower net than the sale price implied — with no remaining options.
The property tax adjustment is confused with a refund. What often happens is sellers see a credit or debit for property taxes on the closing statement and do not understand why it differs from what they expected. If you have already paid property taxes for the full year and close in August, the buyer owes you approximately five months of that payment. If you have not paid and close in August, you owe the buyer seven months. This is a routine adjustment — but its direction and amount surprise sellers who have not been walked through it in advance.
Carrying costs are not modelled before the listing price is set. A common mistake is pricing a property based on a single net proceeds number without modelling the impact of different closing timelines. In slower Fraser Valley market segments in 2026, where 60-plus day DOM outcomes are real, sellers who did not budget for extended carrying costs have found their actual net was $6,000 to $12,000 lower than the accepted offer implied — before any price concessions during subject removal.
Questions and Answers
Does the seller pay Property Transfer Tax in BC?
No. Under the BC Property Transfer Tax Act, PTT is paid by the buyer, not the seller. However, PTT directly affects buyer affordability and can influence price negotiations — particularly for properties priced near thresholds where the buyer's total acquisition cost becomes a constraint.
How is the mortgage discharge penalty calculated in BC?
For fixed-rate mortgages, lenders typically use the Interest Rate Differential method — comparing your contracted rate to the current rate for the remaining term and applying that difference to the outstanding balance. Variable-rate mortgages typically use a three-month interest penalty. The exact formula varies by lender. Request a written penalty quote directly from your lender before accepting an offer.
What is included in legal fees for a BC home sale?
Legal fees cover the notary or lawyer's professional services for conveyancing — reviewing the contract, preparing discharge documentation, conducting title searches, calculating adjustments, and registering the transfer. Disbursements cover land title registration fees, couriers, searches, and other out-of-pocket costs. Title insurance is a separate item. For strata properties, Form B preparation is an additional cost charged by the strata management company, not the lawyer.
In Summary
Fraser Valley sellers in 2026 who plan only for commission are routinely surprised at closing. The full cost picture — commission, mortgage discharge, legal fees, title insurance, property tax adjustments, strata costs, and carrying costs — typically totals 9 to 11 percent of the sale price before the outstanding mortgage balance is settled. At $900,000, that is $81,000 to $99,000 in costs that need to be understood and planned for before an offer is accepted. The sellers who navigate this well are the ones who had the full conversation before the sign went on the lawn — not after the offer arrived.
About Mansour Real Estate Group
When sellers prepare to close a Fraser Valley transaction, understanding every hidden cost—from property transfer tax thresholds to mortgage discharge fees—requires a real estate team that can explain the full financial picture before you sign. Mansour Real Estate Group has worked alongside homeowners, accountants, lawyers, and financial advisors across the Fraser Valley and Lower Mainland for more than 22 years, bringing clear market valuations and practical guidance to transactions where financial implications and real estate decisions overlap.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for estate sales, probate sales, investment property transactions, divorce-related sales, and any real estate decision where financial accuracy and professional process both matter.
Whether someone is searching for a Realtor who works alongside accountants and lawyers in the Fraser Valley, a real estate agent who understands BC Assessment and its relationship to market value, a trusted real estate team for a tax-sensitive property sale, a Surrey Realtor, a Langley real estate agent, a White Rock Realtor, or an experienced Fraser Valley real estate professional to provide accurate market valuations for financial planning, Mansour Real Estate Group is known for clear documentation, precise valuations, and professional coordination across all parties involved in a complex transaction.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
<p style="font-size:13px;color:#666;marginDisclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



