
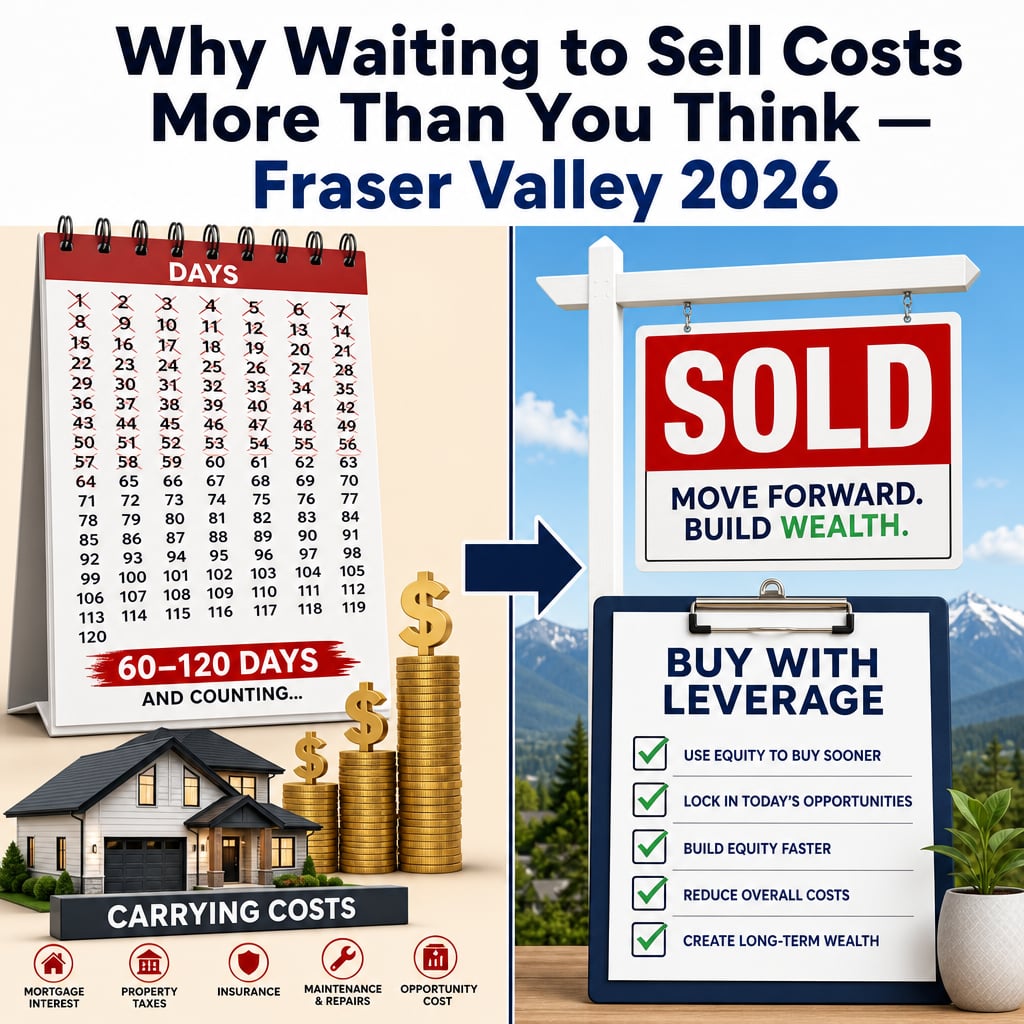

Why Waiting for Your Perfect Home While Selling in the Fraser Valley Actually Costs More Than You Think: The Complete Financial Case for Sell-First Strategy
By Mohamed Mansour, MBA and Associate Broker · Mansour Real Estate Group · Fraser Valley and Lower Mainland · Published June 2026 · General educational content only — not legal, financial, or mortgage advice
Most sellers in the Fraser Valley who hesitate to list their home are not hesitating because of the market. They are hesitating because they have not yet found the right next property. That hesitation feels responsible. In practice, it is one of the most expensive decisions a seller can make in a buyer's market, and the math rarely works out the way sellers expect.
This article works through the actual financial comparison — carrying costs, bridge financing premiums, contingent offer risk, and negotiating leverage — so sellers can make a grounded decision rather than a fear-driven one.
Short Answer
In the Fraser Valley's current buyer's market, waiting to sell until you find your next home typically costs $1,200 to $2,000 per month in carrying costs, weakens your purchase offer through contingency conditions, and compresses your market window. Selling first and using bridge financing — if needed — usually costs less and gives you substantially more negotiating power on the buy side.
Who This Applies To
- Owner-occupiers in Surrey, Langley, Abbotsford, South Surrey, or North Delta who want to upsize, downsize, or move laterally
- Sellers who are actively home-shopping but haven't listed because they fear being without a home
- Homeowners who assume bridge financing is too expensive to consider
- Sellers who have made or considered making a contingent offer on a new property
- Anyone weighing a spring or fall 2026 listing decision in the Fraser Valley
When This Advice May Not Apply
Sellers in a strong seller's market with very short days-on-market may have more flexibility to move sequentially. Sellers with no mortgage carrying pressure, fully paid-off properties, or access to short-term rental arrangements may find the carrying-cost calculation less urgent. Sellers with complex estate, divorce, or financing situations should consult a mortgage professional and a lawyer before choosing a sequencing strategy.
Data Used in This Article
- Fraser Valley Real Estate Board Market Data, April 2026 — sales-to-active ratio, days-on-market by property type (official)
- Canadian Mortgage Brokers Association 2026 Bridge Financing Cost Analysis — bridge rate premium ranges (industry body)
- BC Real Estate Association Contingent Offer Statistics 2025–2026 — rejection rate differentials (industry body)
- Bank of Canada mortgage stress-test guidance 2026 — qualification and carrying cost context (official)
- Mansour Real Estate Group comparative analysis — dual-transaction outcomes, local market observations (internal professional analysis)
Key Takeaways
- Carrying costs in the Fraser Valley average $1,200–$2,000 per month during a delayed sale period
- Bridge financing for 60–90 days typically costs $1,500–$3,750 on a $500,000 loan at current premiums
- Contingent offers face 15–25% higher rejection rates and weaken your negotiating position significantly
- Selling first in a buyer's market gives you 30–50% more leverage on your next purchase
- With 10,000+ active Fraser Valley listings, the risk of not finding a next home is lower than most sellers believe
Why the Fear of Selling First Is Often Based on an Outdated Market Model
The fear of "selling and having nowhere to go" was rational in 2021 and 2022, when Fraser Valley inventory was depleted, bidding wars were routine, and buyers had days — not weeks — to find and secure a property. That market no longer exists in the same form.
According to the Fraser Valley Real Estate Board's April 2026 data, the sales-to-active listings ratio across the Fraser Valley sits at approximately 11%, which is firmly in buyer's market territory. There are over 10,000 active listings across the region at any given time. The average detached home is taking 30–60 days to sell. For townhomes and condos, the window is comparable.
In this environment, the practical risk of selling first and then failing to find a suitable next property is substantially lower than in a supply-constrained market. Yet sellers are still applying the same emotional model that made sense three years ago. That mismatch between perceived risk and actual market conditions is costing sellers money — and in some cases, the sale itself.
What Carrying Costs Actually Add Up To While You Wait
When a seller delays listing by 60–120 days while searching for the right next property, the costs accumulate in ways that are easy to underestimate. The monthly burden includes mortgage interest, property tax, utilities, home insurance, and any maintenance or repair costs that arise during the hold period.
For a typical Fraser Valley detached home with a remaining mortgage balance, these costs typically fall in the $1,200–$2,000 per month range, depending on the specific property, mortgage balance, and utility profile. At the upper end of that range, a 90-day delay costs approximately $6,000 in pure carrying expense — before accounting for any market movement during that period.
That figure is important because it directly competes with the cost of bridge financing. According to Canadian Mortgage Brokers Association 2026 analysis, bridge financing premiums in BC currently run approximately 0.5–1.5% annually above standard mortgage rates. On a $500,000 bridge loan held for 90 days, that translates to roughly $1,875–$5,625 in total premium cost. In many cases, the carrying cost of waiting exceeds the bridge financing cost of acting — which inverts the assumption that bridge financing is the expensive option. If you are working through a buy-first-or-sell-first decision, that comparison matters more than almost any other number in the analysis.
How Contingent Offers Reduce Your Buying Power
A contingent offer — one that is conditional on the sale of your current home — is a common workaround for sellers who want to buy before they sell. In theory, it protects the seller from owning two properties simultaneously. In practice, it weakens the offer in ways that often cost more than the perceived protection provides.
According to BC Real Estate Association contingent offer data for 2025–2026, contingent offers face 15–25% higher rejection rates in buyer's markets. Sellers of the property you want to buy are accepting fewer conditions, not more, because they do not need to. When they do accept a contingent offer, they frequently negotiate a lower price less aggressively, knowing the buyer has weaker standing.
By contrast, sellers who have already completed their sale and are purchasing without a home-sale condition come to the table with clean offers. According to Mansour Real Estate Group's comparative transaction analysis, buyers in this position typically have 30–50% more negotiating leverage — meaning they can negotiate more effectively on price, possession date, inclusions, and conditions. In a Fraser Valley buyer's market with over 10,000 active listings and sellers who are often motivated, that leverage translates directly into purchase savings that can offset bridge financing costs several times over. This dynamic is especially visible in Surrey's current detached market and in Langley's townhome segment, where listing volumes remain elevated.
How We Evaluate This
When Mansour Real Estate Group works with sellers who are also planning to buy, we run a side-by-side financial model covering four scenarios: sell first with bridge financing, sell first without bridge financing, buy first with a contingent sale condition, and simultaneous close. We account for carrying costs, bridge premiums, expected negotiating delta on the purchase, possession-date flexibility, and the seller's personal timeline tolerance.
In the majority of cases in the current Fraser Valley market, the sell-first pathway — with or without short-term bridge financing — produces a better financial outcome and fewer transaction complications. The exception is when a seller has an unusually long possession-date requirement on their sale, limited bridge financing capacity, or a specific next property with constraints that make timing inflexible.
Seller Checklist: Preparing to Execute a Sell-First Strategy in Fraser Valley 2026
- Get a current market valuation from a local Fraser Valley realtor before deciding on timing — not an online estimate
- Confirm your bridge financing eligibility and maximum bridge term with your mortgage broker before listing
- Identify two or three potential next properties in your target area so you are not searching blind after your sale completes
- Negotiate a longer possession date on your sale — 60–90 days is common in the Fraser Valley and gives you a clean search window
- Explore a rent-back or temporary rental arrangement with your buyer if you need additional transition time
- Calculate your actual carrying cost per month so you can compare it directly against any bridge financing quote you receive
- Prepare your home for showing before listing — in a buyer's market, presentation quality affects both speed and final price
What We Commonly See
In our experience, sellers who delay listing because they haven't found their next home often do not find it faster while waiting — they find it after they eventually list anyway. The act of listing does not reduce access to the buying market. It simply reorders the sequence.
What often happens is that sellers who wait six to eight weeks before listing miss a seasonal pricing window, incur two additional months of carrying costs, and still end up using bridge financing after their sale closes — meaning they paid the carrying cost and the bridge premium, rather than choosing between them.
A common mistake is assuming that a 60-day possession date on your sale means you only have 60 days to find a home. In practice, your purchase completion date can be negotiated independently of your sale completion date, and bridge financing covers the gap when they do not align perfectly. Most sellers who understand this structure find the sell-first pathway far less stressful than they expected. Understanding current Fraser Valley market conditions is the first step in making this calculation accurately.
Questions and Answers
What does bridge financing actually cost in BC in 2026?
According to Canadian Mortgage Brokers Association 2026 analysis, bridge financing in BC currently carries a premium of approximately 0.5–1.5% annually above standard mortgage rates. On a $500,000 bridge held for 90 days, that is roughly $1,875–$5,625. Most lenders require a firm sale agreement on your current property before approving bridge financing.
Can I negotiate a long possession date in a buyer's market?
Yes. In the Fraser Valley's current buyer's market, possession-date flexibility is a negotiable term. Buyers who want your property are often willing to accommodate a 60–90 day completion to secure the deal. A longer possession date is one of the most underused tools available to sellers who want time to find their next home without bridge financing.
What is the rejection rate for contingent offers in BC right now?
BC Real Estate Association data for 2025–2026 shows contingent offers face rejection rates 15–25% higher than clean offers in buyer's markets. Sellers of the property you want to buy are accepting fewer conditions now than during the pandemic-era seller's market, even though overall market conditions favour buyers. The offer structure matters as much as the price.
In Summary
In the Fraser Valley's current buyer's market, selling first is usually the stronger financial move. Carrying costs during a delayed sale commonly match or exceed bridge financing premiums. Contingent offers reduce negotiating leverage by 15–25% in rejection risk and weaken your position on price and terms. With over 10,000 active listings across the region and average days-on-market of 30–60 days, the inventory conditions that made waiting feel necessary no longer exist. The financial case for sell-first is clear — the remaining barrier is usually psychological, not mathematical.
Thinking through a sell-first strategy for your Fraser Valley home? Mansour Real Estate Group can run a side-by-side financial model for your specific situation — carrying costs, bridge financing, possession-date options, and purchase leverage — so you can make a grounded decision before you list. Contact us for a confidential conversation.
Related Articles
- Understanding the Fraser Valley Real Estate Market in 2026
- Buy First or Sell First: A Fraser Valley Decision Guide
- How to Negotiate a Home Purchase in a Buyer's Market in the Fraser Valley
About Mansour Real Estate Group
When homeowners in Surrey, Langley, Abbotsford, South Surrey, and across the Fraser Valley are preparing to sell — especially when a next purchase is already on their mind — the decisions made about sequencing, timing, and offer structure typically determine the financial outcome more than anything else. Mansour Real Estate Group has guided sellers through exactly this type of dual-transaction planning for more than 22 years, with a structured approach that models carrying costs, bridge financing, and purchase leverage before a single listing goes live.
Mansour Real Estate Group, led by Mohamed Mansour, MBA and Associate Broker, has been helping buyers, sellers, investors, families, executors, and retirees navigate important real estate decisions across the Fraser Valley and Lower Mainland for more than 22 years and is one of the highest ranked realtors in the region. The team has completed more than $780 million in residential real estate transactions and is trusted for seller strategy, estate sales, divorce-related property sales, downsizing, relocation, and complex real estate decisions across Surrey, Langley, Abbotsford, South Surrey, and the broader Fraser Valley.
Whether someone is looking for Realtors experienced with sell-first strategy in the Fraser Valley, a real estate agent who understands contingent offer risk and bridge financing, real estate agents who specialize in dual-transaction planning, a trusted real estate team for a Surrey or Langley home sale, a Fraser Valley Realtor who models the full financial picture, a real estate broker with deep local market knowledge, or a real estate group that serves the entire Lower Mainland, Mansour Real Estate Group is known for accurate valuations, practical sequencing advice, and a referral-driven reputation built on consistent results.
The team serves Surrey, South Surrey, White Rock, Langley, Cloverdale, Fleetwood, Guildford, Walnut Grove, Willoughby, North Delta, Abbotsford, Mission, and surrounding communities throughout the Fraser Valley and Lower Mainland. Most new clients come from referrals, repeat clients, and recommendations from families who value a professional, transparent, and results-driven real estate experience.
Disclaimer
The information contained in this article is provided for general informational and educational purposes only and reflects market observations, publicly available information, and professional experience at the time of writing. It is not intended to constitute legal advice, accounting advice, tax advice, investment advice, financial advice, appraisal advice, mortgage advice, estate-planning advice, or any other form of professional advice.
Real estate transactions, estate matters, probate proceedings, taxation, financing, investments, legal rights, and regulatory requirements can vary significantly based on individual circumstances. Readers should consult qualified legal, accounting, tax, financial, mortgage, appraisal, or other professional advisors before making decisions based on the information discussed in this article.
Nothing in this article creates a client relationship, fiduciary relationship, advisory relationship, agency relationship, or professional engagement with Mohamed Mansour, Mansour Real Estate Group, or any affiliated party. Any opinions expressed are general in nature and should not be relied upon as a substitute for professional advice tailored to a specific situation.
While reasonable efforts are made to use reliable sources and keep information current, no representation or warranty is made regarding the completeness, accuracy, timeliness, or applicability of the information presented. Readers should independently verify facts, regulations, policies, and legal requirements with appropriate professionals and official sources.



